


EN
Merck (MRK) Stock Still Looks Like A Bargain On Its 113% Run
Merck has been a strong performer in recent years, and with fresh oncology data and new treatments moving through regulators, the question now is whether the current share price lines up with the cash the business can generate. For anyone looking at the stock today, the issue is less about headlines and more about what those developments mean for the underlying cash flows that a Discounted Cash Flow (DCF) model seeks to capture.
- Merck has delivered a 113.5% return over the past 5 years, which puts a lot of expectations into the price and makes the link to future cash generation especially important.
- Positive trial results for sacituzumab tirumotecan and KEYTRUDA in endometrial cancer, along with expanded treatment options in bladder cancer, can influence assumptions about the timing, durability, and scale of future cash flows from Merck's oncology portfolio.
- Prefer to judge Merck on sales? See what Merck's 5.5x P/S says about the price.
The issue now is whether that recent performance and oncology progress are fully, partly, or not yet reflected in Merck's intrinsic value based on its cash flows.
If you want more context around Merck's oncology driven cash flows, it can help to compare them with other established dividend payers by scanning 5 dividend fortresses.
Is Merck a Bargain on Cash Flow?
The Discounted Cash Flow (DCF) model here takes Merck's cash generation and projects it forward, then brings those future dollars back to today's terms. Latest twelve month free cash flow sits at about $16.1b, and the forecast path assumes that this cash pool keeps growing rather than shrinking over the next decade as oncology and other therapies contribute more.
Analyst projections feeding the DCF point to higher annual free cash flow by the early 2030s, which suggests the business is treated as a mature but still expanding cash engine rather than a turnaround story. Because the Discounted Cash Flow (DCF) projections put Merck's estimated intrinsic value substantially above the current share price of $149.52, the model implies investors are paying less for each forecast dollar of cash generation than those projections support. Because the positive Phase 3 results for sacituzumab tirumotecan in endometrial cancer underline potential longevity for Merck's oncology cash flows, that gap between projected value and the market price may be especially important for long term holders weighing today’s entry point. Find out what Merck could be worth using our Discounted Cash Flow (DCF) estimate.
The Merck Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where Merck's valuation puzzle leaves off by spelling out which expectations around growth, margins, and earnings would need to hold for the stock to be worth materially more or less than today’s price, and they sit on the platform’s Community page. Each one treats Merck's fair value as a clear, testable idea about the business that can be tracked over time rather than a one off snapshot.
Merck holders in the community are split between seeing a pipeline supported cushion for cash flows and worrying that a lot of that promise already looks reflected in the price.
Bull case: 6% undervalued
"Merck plans to bring over 20 new growth drivers to market in the coming years, and management now points to more than US$70b in non risk adjusted mid 2030s revenue potential from this next generation portfolio..."
Discover why this Narrative puts Merck at 6% undervalued.
Bear case: 24% overvalued
"The numbers implied by Merck’s current valuation and guidance, including mid 2030s non risk adjusted revenue ambitions of more than US$70b from new human health products, suggest the share price already reflects a high degree of confidence in successful delivery on most of this pipeline and diversification story..."
Explore why this Narrative puts Merck at 24% overvalued.
One more Merck signal to check before you move on
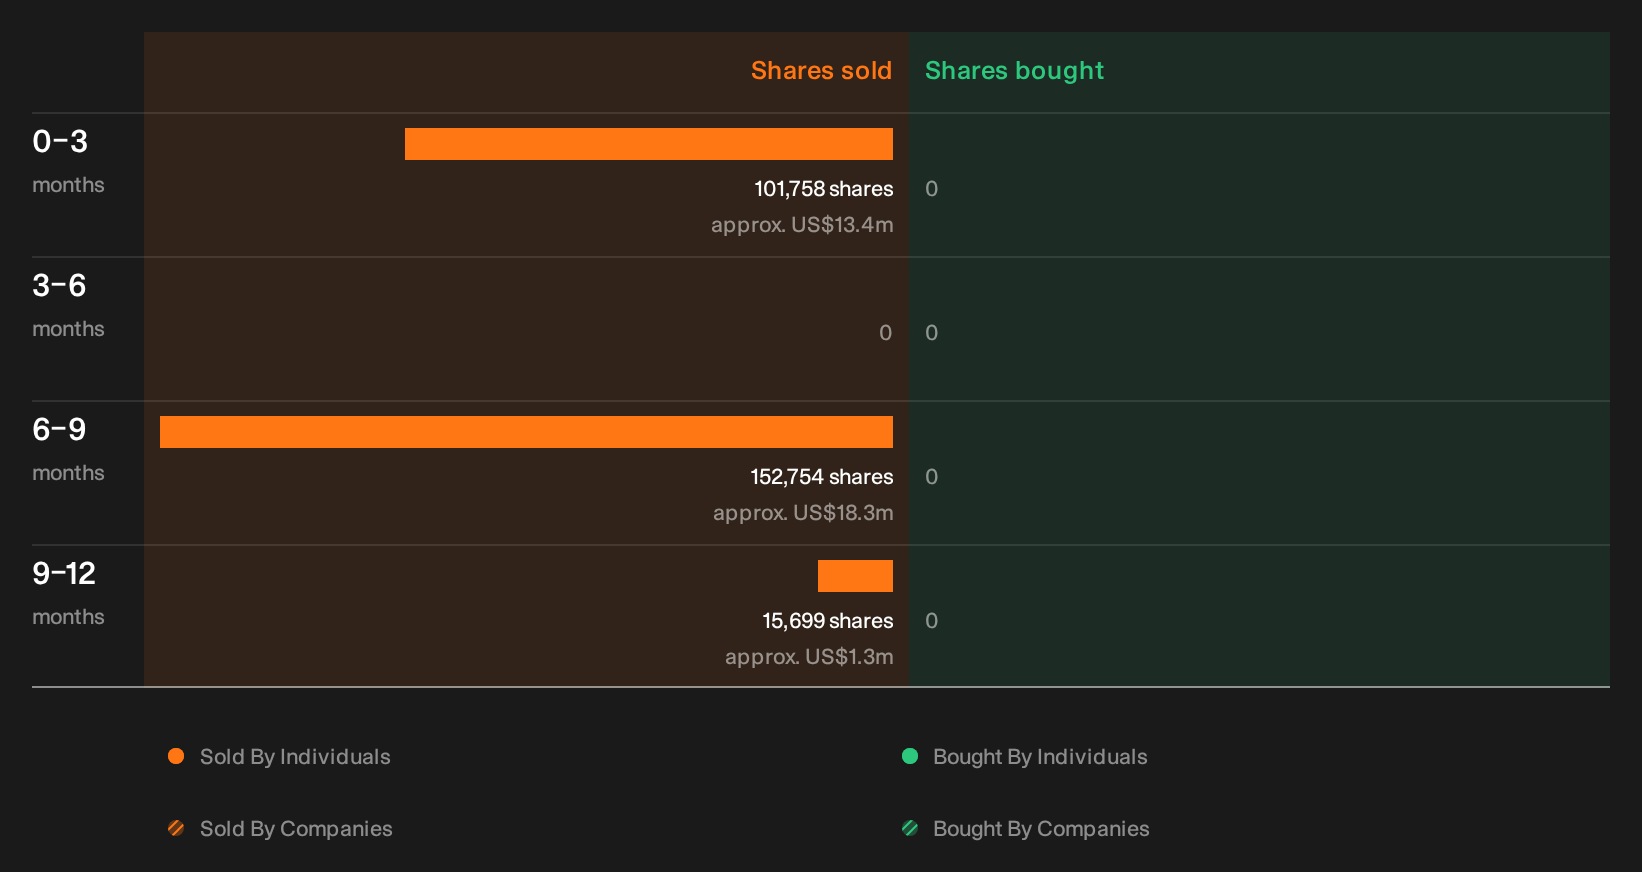
Before acting on any view of Merck's worth, it is worth knowing that recent trades by people inside the business have been flagged by our checks, with the individuals, size of sales and possible meaning left for you to review. See the recent insider selling flagged for Merck.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com