


EN
Learn Why The Bull Case For Lockheed Martin Stock Could Change Following Raised Guidance
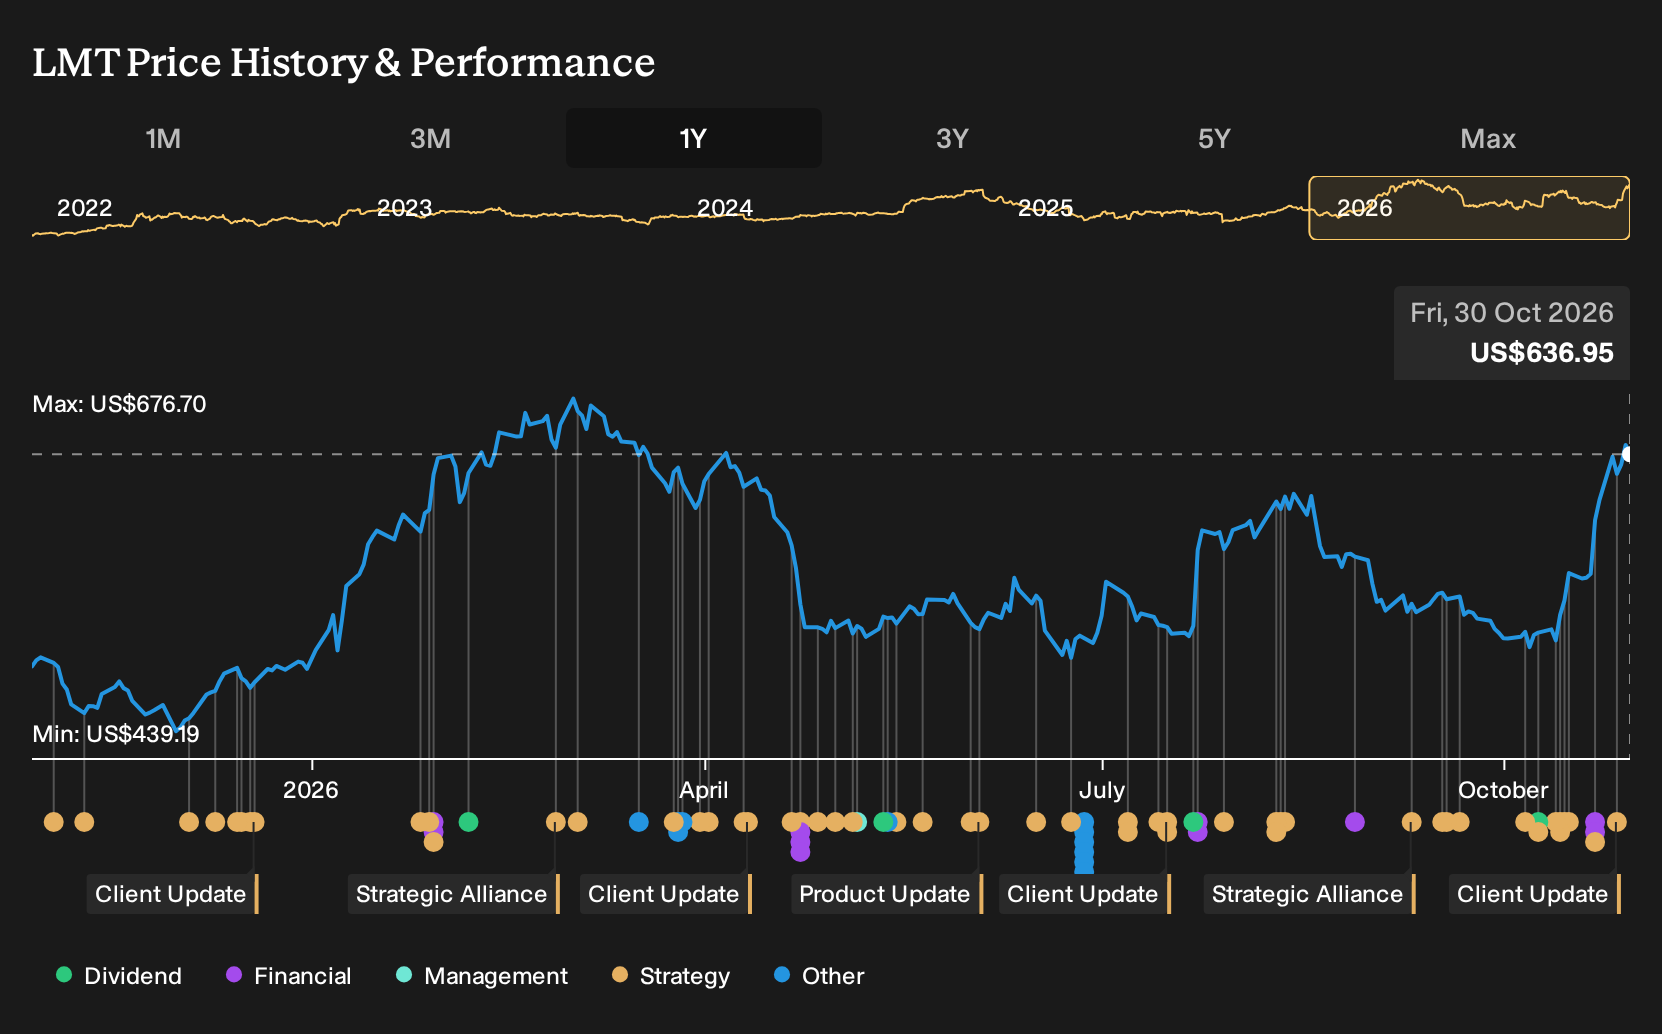
- Lockheed Martin reported higher third quarter 2026 revenue of US$20.71b and net income of US$1.85b, raised full year sales and earnings guidance, and secured large multiyear contracts, including a US$694m ARRW hypersonic weapon award and a long term F 35 production and sustainment framework.
- These awards and the record order pipeline, including a backlog reported at US$292b, point to extended production visibility across missiles, hypersonic systems and the F 35 program. This could influence how investors view Lockheed Martin’s ability to convert contracted work into future cash generation.
- We will now look at how Lockheed Martin’s raised guidance and record backlog could reshape the investment narrative around its cash generation.
Lockheed Martin Investment Narrative Recap
To remain a shareholder in Lockheed Martin, you need to be comfortable with a defense contractor that is focused on very long term, contract driven demand. The big near term swing factor is execution on this record US$292b backlog, particularly in high margin missiles and hypersonic programs, so that booked work reliably converts into cash.
The main risk at this point remains operational. Complex fixed price and legacy programs can produce cost overruns or technical issues that affect profits, while high debt leaves less room for error. Recent contracts and raised guidance do not remove that exposure, but they can give management more scale to absorb setbacks.
The F 35 framework agreement announced on 22 October appears most relevant to the current situation. A 10 year plan for 850 U.S. aircraft plus sustainment, tied to a steady 156 jets per year, increases visibility on production volume and aftermarket activity. That can matter if you are focused on how earnings and cash flows are supported by contracted demand.
There is still work to do. That framework depends on multiyear authority and final terms, and any regulatory or contractual change could alter timing or economics. If it is executed as outlined, the deal would sit alongside the ARRW hypersonic award and seven year munitions frameworks as a key element in how you may think about Lockheed Martin’s operating resilience and program risk.
How Analyst Expectations Frame Lockheed Martin’s Cash Story
Analysts are effectively telling you that Lockheed Martin’s current backlog and recent contracts only make sense if they translate into steady expansion in both sales and profitability over several years, not a one off bump. The projections in the latest consensus fold those multiyear missile and F 35 frameworks into a view of the business that assumes higher throughput and slightly richer margins, then discount those outcomes back into today’s share price.
On the top line, the forecast sits at 5.9% yearly revenue growth over the next three years. That pace, if achieved, would reflect consistent conversion of today’s US$292b order book into reported sales as PAC 3, THAAD, ARRW and F 35 related work move from contract to production and sustainment. The growth rate is not extreme. This means the focus shifts to how reliable that compounding can be given the mix of long cycle defense programs and framework agreements already in hand.
Earnings expectations give another lens on Lockheed Martin’s cash potential. Consensus points to profit margins rising from 8.2% today to 9.1% in three years, while earnings are projected to climb from US$6.5b today to US$8.6b by 2029. That is an increase of about US$2.1b in annual earnings tied to analysts’ view that higher volume on existing platforms, plus operational improvements and automation, can feed through to the bottom line over time.
Those earnings, combined with the assumed 5.9% annual revenue uplift, anchor the valuation work that analysts publish. Their models typically apply a target P/E multiple to the US$8.6b earnings figure for 2029, imply a share price for that year, and then discount it back using an 8.18% or 8.2% rate to judge whether today’s market value lines up with the forecast. The fact that this framework uses a 22.0x P/E on 2029 earnings, which is lower than the quoted P/E for the broader US Aerospace & Defense group at 31.5x, is an important part of how some investors interpret the relative pricing of the stock against peers.
Lockheed Martin's narrative projects US$94.0b revenue and US$8.6b earnings by 2029. This assumes 5.9% yearly revenue growth and about US$2.1b earnings increase from US$6.5b today.
Uncover why Lockheed Martin's fair value indicates a value that is roughly in line with its current price.
Exploring Other Perspectives
One big swing factor some of the most optimistic analysts focus on is Lockheed Martin’s munitions capacity build out. Before this ARRW contract and facility expansion, they were already modelling around 8.2% yearly revenue growth and about US$9.4b in 2029 earnings. You can treat this news as a fresh test of those higher expectations and compare it with more cautious views.
Explore 5 other Lockheed Martin fair value estimates, including one that suggests as much as 36% upside from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider forming your own view.
- A great starting point for your Lockheed Martin research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Lockheed Martin. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Lockheed Martin's overall financial health at a glance.
Looking for more Lockheed Martin style investment ideas?
If you want to apply the same kind of contract visibility and balance sheet focus used to assess Lockheed Martin to a wider watchlist, the Simply Wall St Screener can help you surface other opportunities that match your risk and income preferences.
- If capital preservation and resilience matter most to you, start with a curated set of companies flagged for their stability and lower overall risk profile through the 30 resilient stocks with low risk scores.
- For readers hunting for mispriced opportunities backed by solid fundamentals, use the screener to narrow in on 29 high quality undervalued stocks that may warrant a closer look.
- If dependable income is a priority, focus on businesses with higher payout levels and sturdier cash coverage by scanning our hand picked group of 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com