


EN
Katapult Holdings (KPLT) Sets Up Its Next Test On A Pricey P\E
Katapult Holdings (KPLT) has set a clear date for its next checkpoint. Third quarter 2026 results are scheduled before the market opens on 12 November, followed by an investor conference call and webcast.
Recent trading in Katapult Holdings has been volatile, with a 30 day share price return of 137.53% and a 7 day move of 32.40%, even after a 1 day decline of 17.09%. However, the 1 year total shareholder return is still down 8.87%, which points to strong short term momentum alongside a weaker long term record.
Scan how Katapult Holdings fits into the broader market by comparing it with a hand-picked 18 high quality undiscovered gems that shows strong fundamentals but has limited mainstream attention.
The question now is direct: Does Katapult Holdings’ sharp rebound signal a stronger underlying business or a short burst of changing sentiment that leaves the valuation stretched?
Preferred P/E of 15x: Is it justified?
Katapult Holdings currently trades on a P/E of 15x, which links the recent share price recovery to investor expectations for future profitability rather than just short term trading enthusiasm.
The P/E ratio compares what you pay per share with the earnings that Katapult Holdings generates per share. For a consumer finance platform, this measure often reflects how sustainable the profit stream looks and how much confidence the market has in that earnings profile.
Recent fundamentals provide mixed signals. Earnings grew 82.3% over the past year and the business is now profitable over a 5 year window, while net profit margins improved from 1.8% to 3.4%. At the same time, interest payments are not well covered by earnings, shareholders' equity is negative and all funding comes from higher risk external borrowing, with large one off items affecting reported profit quality.
Compared with the US Consumer Finance industry average P/E of 8.8x and a peer group average of 7.4x, Katapult Holdings trades on a clearly richer earnings multiple. The current ratio indicates the market is placing a much higher value on each dollar of profit than it does for similar lenders and finance platforms.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 15x (OVERVALUED)
Still, the weak 1 year and 5 year shareholder returns, along with reliance on higher risk external borrowing, could quickly pressure Katapult Holdings if sentiment or funding costs shift.
Find out about the key risks to this Katapult Holdings narrative.
Another view on Katapult Holdings’ value
The P/E ratio presents Katapult Holdings as expensive compared with US Consumer Finance peers. The SWS DCF model points in the opposite direction. On this measure, the shares trade at $10.38 against an estimated future cash flow value of $124.65, which implies a deep discount. The key issue is whether those underlying cash flow assumptions hold up.
Look into how the SWS DCF model arrives at its fair value.
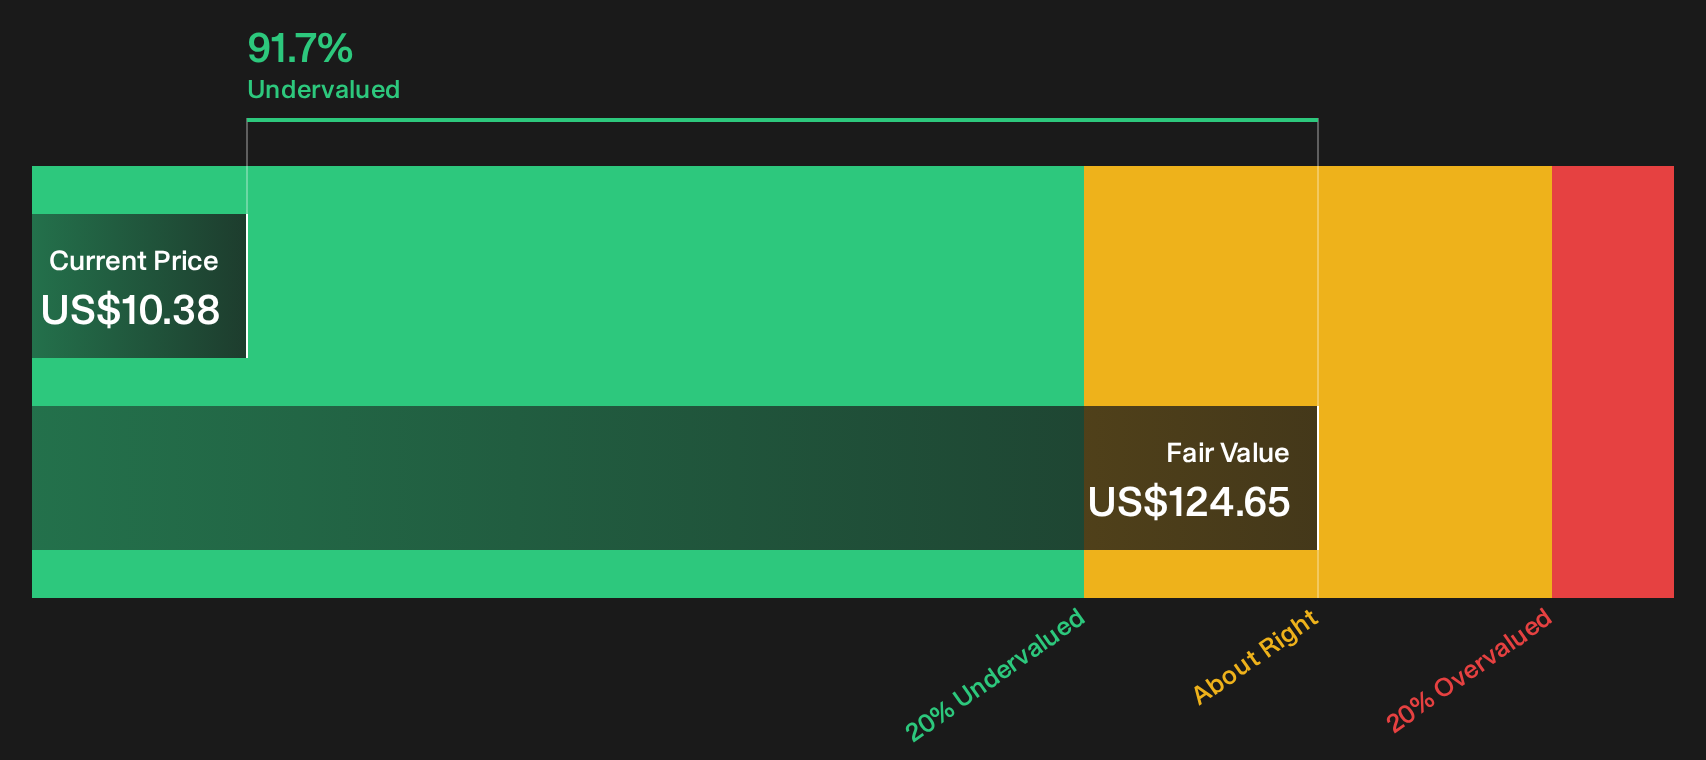
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Katapult Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals or an early inflection point: either way, Katapult Holdings now presents both risks and potential rewards, so consider acting promptly and review the full picture for yourself with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Katapult Holdings?
If Katapult Holdings has your attention, do not stop here. Broaden your watchlist and pressure test your thesis against other opportunities that fit different playbooks.
- Target potential bargains supported by strong fundamentals and disciplined balance sheets by scanning our 29 high quality undervalued stocks.
- Lock in potential income streams by reviewing companies with resilient payout profiles using the 5 dividend fortresses.
- Dial down portfolio risk by filtering for sturdier businesses with dependable finances through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com