


EN
How Lower Revenue Guidance Will Impact ATOSS Software Stock Investors
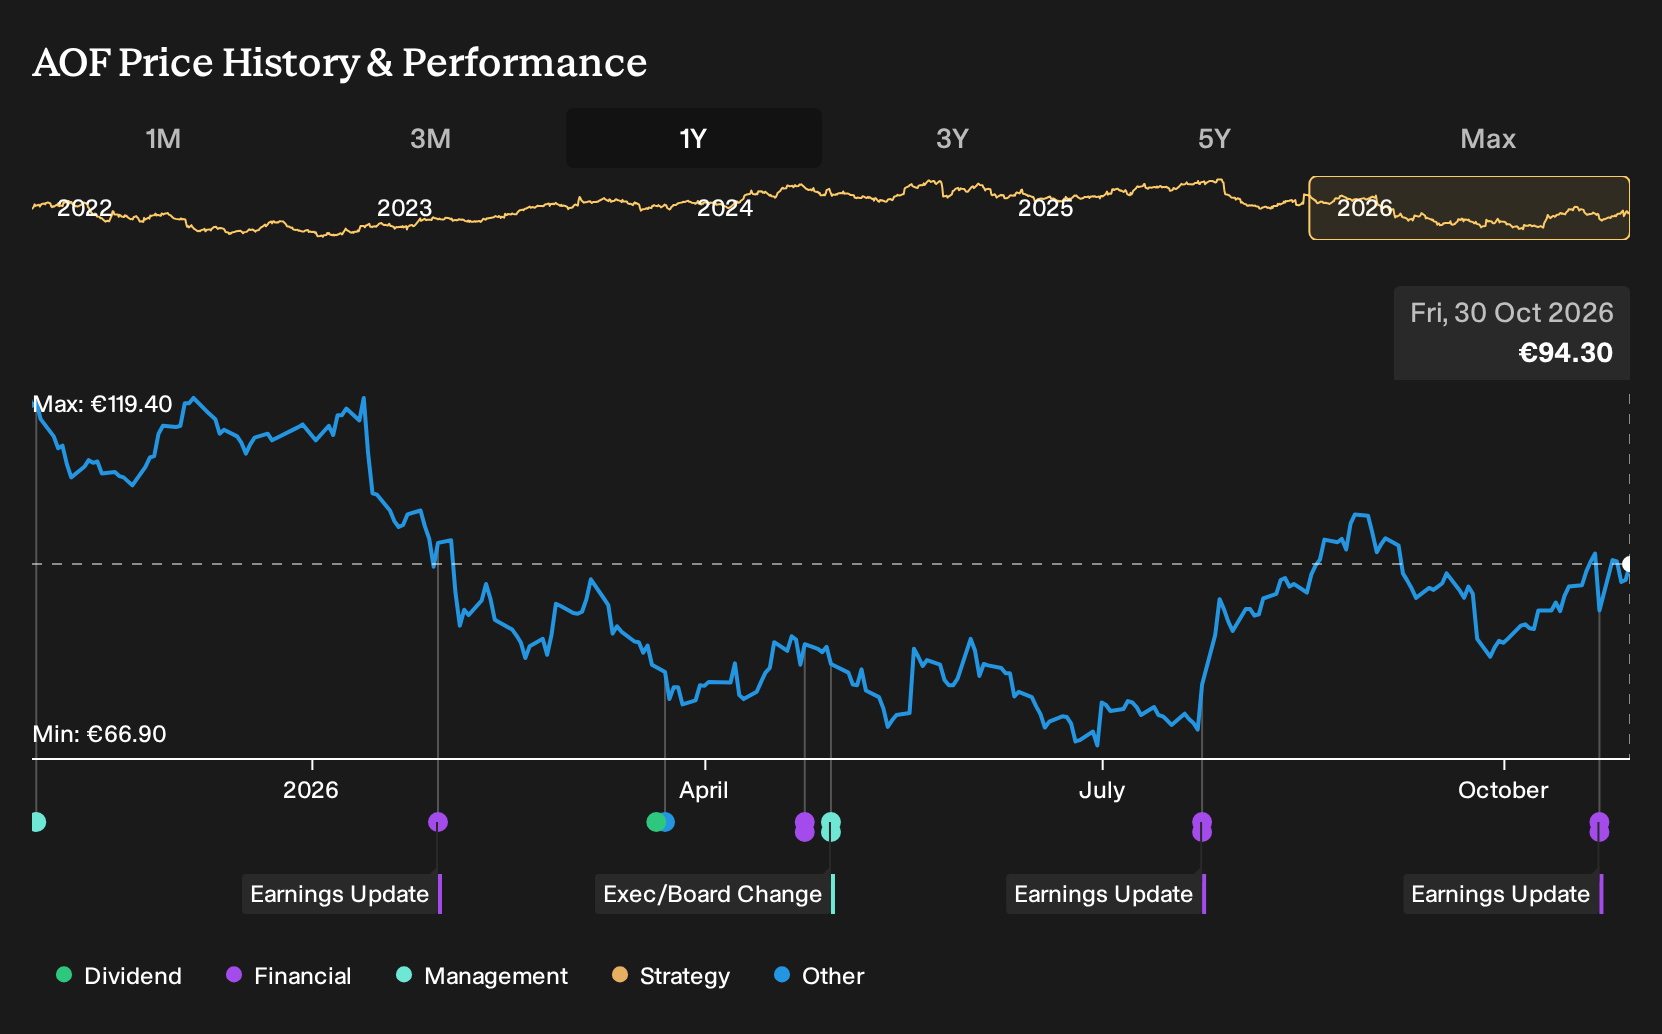
- ATOSS Software reported third quarter 2026 revenue of €52.57 million and net income of €14.4 million, alongside updated 2026 guidance that keeps sales at the lower end of the €210 million to €215 million range while lifting the EBIT margin target to around 37%.
- The mix shift toward recurring income and efficiency gains is now reflected in higher profitability guidance, even as ATOSS Software signals a more cautious top line outlook for 2026.
- This article will examine how ATOSS Software's investment narrative is influenced by higher 2026 EBIT margin guidance alongside revenue expectations at the bottom of the indicated range.
Compare ATOSS Software's mix of lower guidance and higher margins with other companies balancing top line expectations and profitability in our hand picked 194 high quality undervalued stocks.
ATOSS Software Investment Narrative Recap
To own ATOSS Software, you need to be comfortable with a story that prioritises recurring cloud and subscription income, supported by AI driven efficiency projects, while accepting a more measured view on near term demand. The confirmation that 2026 revenue should land at the lower end of the €210 million to €215 million range keeps contract conversion and macro exposed sectors, such as manufacturing and SMBs, in focus.
The raised EBIT margin target of around 37% signals that internal efficiency and a richer recurring mix are offsetting slower top line momentum. For the short term, the key catalyst is whether the existing pipeline converts into new cloud ARR. The main risk remains hesitant customer spending that delays migrations and new deals.
The third quarter 2026 earnings release is the clearest reference point for this guidance update. ATOSS Software reported €52.57 million in quarterly revenue and net income of €14.4 million, which shows the current profitability level that management is trying to protect through the upgraded EBIT margin outlook for the full year.
Those numbers for the first nine months of 2026, with €155.8 million in revenue and €38.96 million in net income, frame the rest of the year. Execution from here needs to hold EBIT discipline while still building cloud and subscription backlog. If contract signings soften further, the risk is that future growth ambitions tied to that backlog become harder to reach, even if margins remain healthy in the near term.
ATOSS Software's current analyst narrative points to revenues of €292.7 million and earnings of €72.9 million by 2029, based on an assumed yearly revenue growth rate of 13.5%. That profile is built on earnings today of €51.2 million, which implies an earnings increase of about €21.7 million by the 2029 forecast year.
Uncover why ATOSS Software's fair value indicates a 31% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate angle on ATOSS Software focuses on a slower payoff from AI and cloud. The most cautious analysts were working with revenue of about €287.8 million and earnings of €72.9 million by 2029, assuming 11.8% yearly sales growth. That is a much more restrained story than consensus, and this fresh guidance could easily reshape both views.
Explore 2 other ATOSS Software fair value estimates, including one that suggests it could be worth just €120.89.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ATOSS Software research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for ATOSS Software. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ATOSS Software's overall financial health at a glance.
Looking For More Investment Ideas Beyond ATOSS Software?
If you want to cross check ATOSS Software against other potential opportunities, a quick pass through the Simply Wall St Screener can help you line up companies with different risk and return profiles.
- For investors who care most about financial resilience and clean balance sheets, start with a list of solid balance sheet and fundamentals (200 results) that already filters for stronger fundamentals.
- If your priority is limiting downside risk while still staying in equities, consider our 216 resilient stocks with low risk scores to see which businesses have more measured risk scores.
- To surface less crowded ideas with stronger fundamentals, scan through the 602 high quality undiscovered gems and see which stocks deserve a place on your watchlist.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com