


EN
Johnson Controls International (JCI) Dropped, So What Is Behind The Attention Now?
Q3 beat and record backlog put Johnson Controls International (JCI) in focus
Johnson Controls International (JCI) moved into the spotlight after surpassing analyst forecasts for its latest calendar Q3, with demand tied to data centers, mission critical projects and a record backlog drawing investor attention.
Recent trading tells a mixed story. Johnson Controls International shares fell 5.84% on the day to US$149.03 but still show a 21.85% year to date share price return. The 1 year total shareholder return of 31.85% and very large 3 year total shareholder return above 200% point to momentum that has built over time around the business and its execution.
Scan how investors are pricing Johnson Controls International against peers by checking the hand picked 39 power grid technology and infrastructure stocks shaping the future of critical energy and data center infrastructure.
Johnson Controls International now trades below both analyst targets and an indicated intrinsic value, even after its Q3 beat and record backlog. Where does fair value actually fall inside that spread, and how wide is the margin of error?
Most Popular Narrative: 12% Undervalued
Johnson Controls International is framed as undervalued in the most widely followed narrative, with a fair value of $169.70 against the last close at $149.03, putting the gap between price and expectations into sharp focus.
The company has significant opportunities for cost reductions and process improvements through the implementation of Lean practices, supported by recent examples of plant capacity increasing several times over without major capital spending, which can help sustain operating leverage and earnings growth.
See why 25 investors see Johnson Controls International as 12% undervalued.
Result: Fair Value of $169.70 (UNDERVALUED)
Still, the Johnson Controls International narrative could be knocked off course if Fire and Security weakness persists or if operational complexity slows the margin work that investors are banking on.
Find out about the key risks to this Johnson Controls International narrative.
Another View: Johnson Controls International on Earnings Multiples
On a cash flow basis, Johnson Controls International screens as cheap, with our DCF work indicating the stock trades about 15.8% below an estimated future cash flow value of $176.91. That points to undervaluation if those long range assumptions hold.
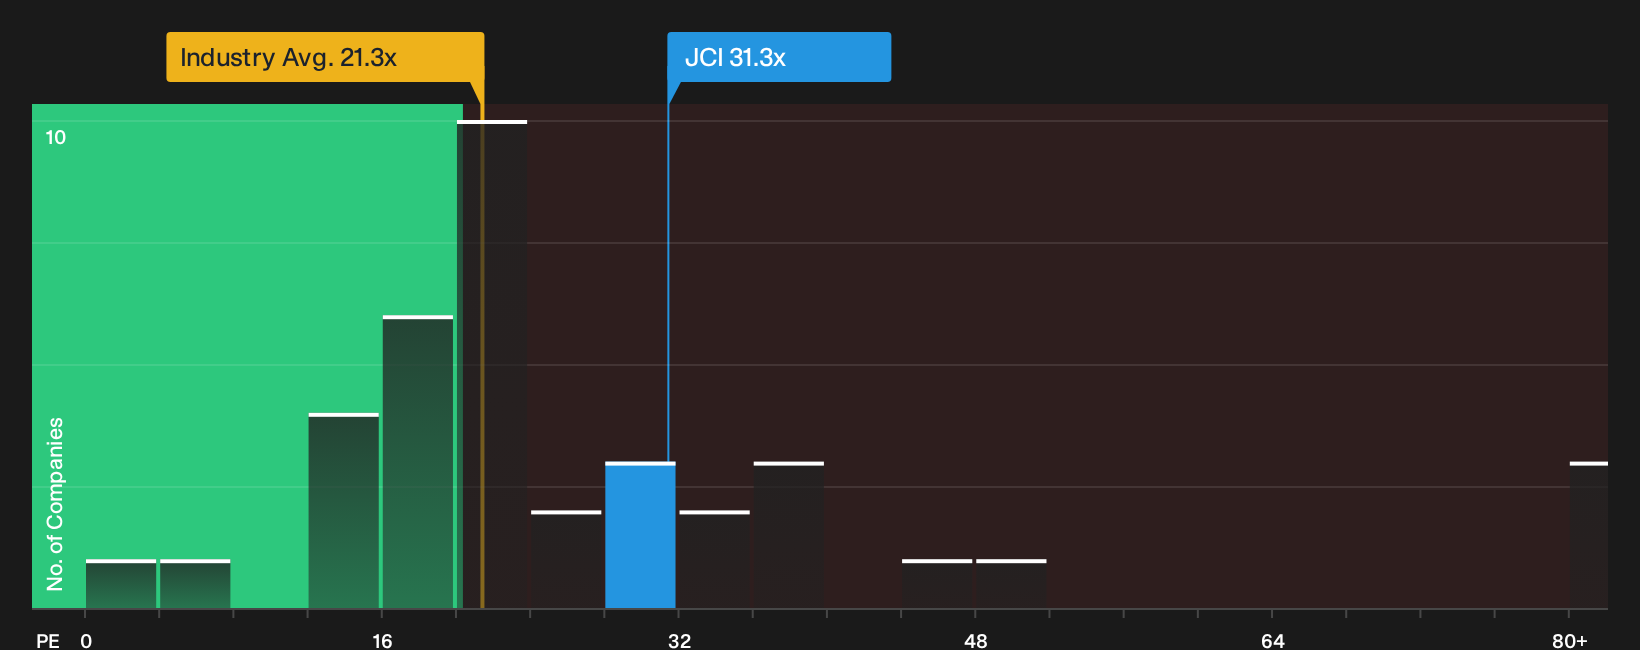
Earnings multiples tell a tighter story. JCI changes hands at a P/E of 31.3x, above both peers at 22x and the US Building industry at 21.3x, yet close to an estimated fair ratio of 32.8x. So is this a genuine discount or just a full price for quality and execution risk?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
There are mixed signals on Johnson Controls International so far. Consider reviewing the full data set yourself, weighing both sides, and then drilling into the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Johnson Controls International?
If Johnson Controls International has your attention, do not stop here. Broader context from other opportunities can sharpen your judgement and help you make better calls.
- Target resilient performance by scanning companies that score well on stability and fundamentals through the 30 resilient stocks with low risk scores.
- Hunt for mispriced opportunities by reviewing companies that appear attractively valued on quality and price in the 29 high quality undervalued stocks.
- Strengthen your watchlist with businesses that pair financial discipline with robust balance sheets by filtering through the list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com