


EN
Repsol (BME:REP) Looks 3% Overvalued As Earnings Beat And Buyback Lands
Repsol (BME:REP) just paired a sharp jump in third quarter earnings with a fresh share buyback and higher dividends, putting capital returns and energy transition spending in clear focus for investors.
The latest jump in Repsol’s third quarter earnings and fresh capital return plans arrives after a strong run in the shares, with a 90 day share price return of 16.49% and an 87.26% year to date move that points to firm momentum. Over a longer lens, total shareholder return of 102.49% over one year and 262.28% across five years signals that investors have already been rewarded for taking on the energy and policy risks tied to Repsol’s transition plans. Any future swings in sentiment are likely to track how sustainably this earnings power and buyback activity are perceived.
Scan for other energy players that are pairing strong earnings with active capital returns by running the hand picked 194 high quality undervalued stocks alongside Repsol’s latest move.
Repsol now combines a strong multi energy footprint with a share price that has already moved significantly. Do the current earnings and buybacks still leave enough value on the table today?
Most Popular Narrative: 3% Overvalued
Repsol last closed at €30.73, while the most followed narrative pegs fair value at about €29.97. The current rally prices in a small premium to that view and puts the focus on how durable its cash generation really is.
The main thing that has to go right is that Repsol continues to execute capital allocation with discipline, including its Venezuela ramp up, Alaska developments, renewables rotations, and industrial decarbonisation projects, without eroding returns.
Current numbers and analyst targets together imply a share price that already reflects a fairly valued bullish view on Repsol, with the market pricing in sustained cash returns and continued strength in refining, upstream, and customer businesses.
See why 80 investors see Repsol as 3% overvalued.
Result: Fair Value of €29.97 (OVERVALUED)
Still, heavy spending on long lead upstream projects, along with rising carbon and regulatory costs, could quickly test how secure the current Repsol narrative really is.
Find out about the key risks to this Repsol narrative.
Another View: What Repsol’s P/E Is Really Saying
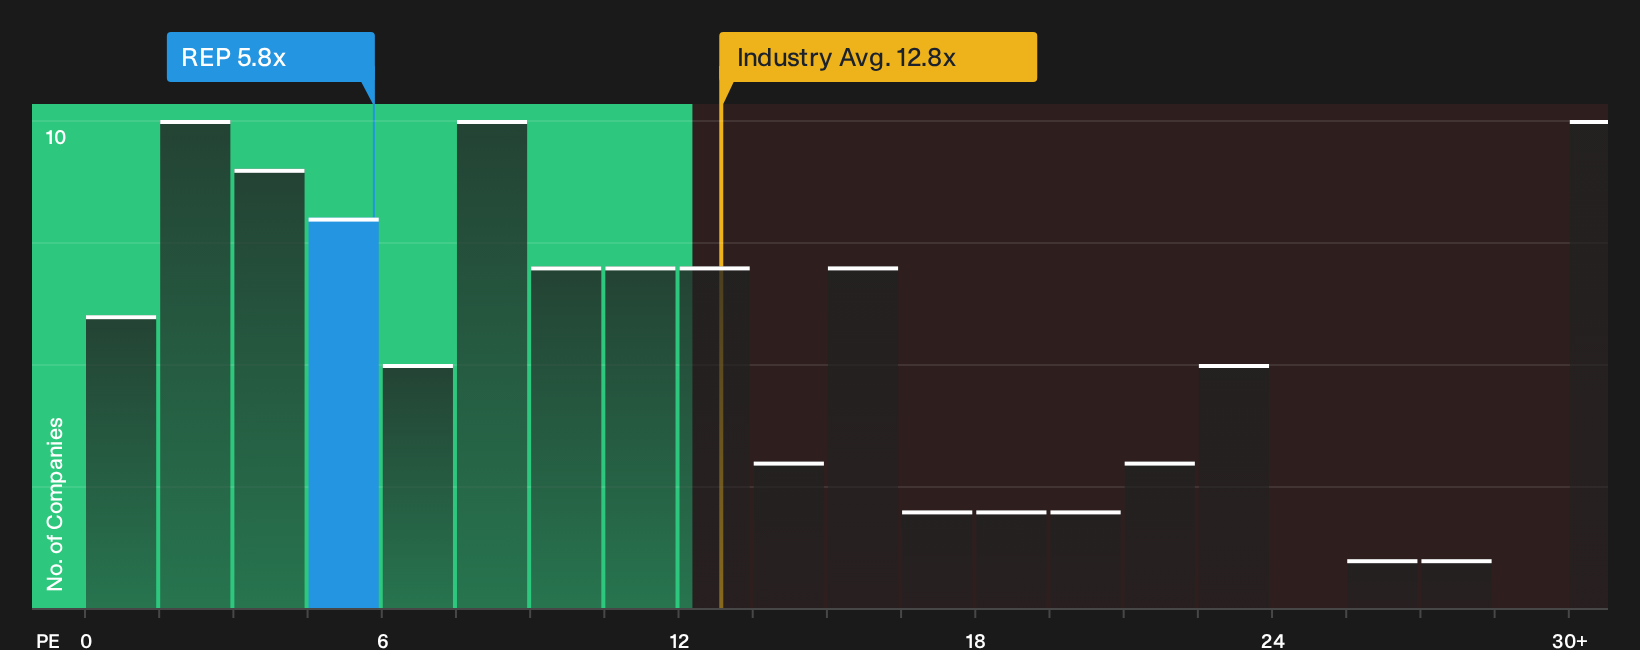
Repsol screens very differently when you switch from fair value models to a simple earnings multiple. The stock trades on a P/E of 5.8x, while peers on average sit near 9.2x and the fair ratio is 7.4x. That gap suggests investors are still pricing in meaningful risk, not a clean premium. The real question is whether that discount reflects caution or an opening for contrarian buyers.
See what the numbers say about this price in our valuation breakdown, then compare Repsol’s current multiple with See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed messages on Repsol so far. If you want to move beyond the headlines and weigh both sides quickly, start by reviewing the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Repsol?
If Repsol has sharpened your appetite for opportunities, do not stop here. Broader idea hunting can quickly highlight alternatives that better suit your goals and risk comfort.
Use the Simply Wall Street Screener to quickly compare different types of opportunities alongside Repsol and avoid missing out on ideas that fit you better.
- Target potential bargains by scanning a hand picked set of companies that screen as attractively priced using the 194 high quality undervalued stocks.
- Strengthen capital preservation by reviewing a 216 resilient stocks with low risk scores that filters for resilient balance sheets and steadier risk profiles.
- Spot under followed potential opportunities early by searching through a curated pool of 602 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com