


EN
Why Did Mitani (TSE:8066) Move Today?
Mitani (TSE:8066) moved into the spotlight after a recent article flagged the group as a top hydrogen stock pick, focusing on its fuel cell business and what were described as high-quality earnings.
Recent price action has been choppy for Mitani, with the share price falling about 18.6% over the past month even though the year-to-date share price return is 23.8% and the 1-year total shareholder return is 26.3%, suggesting longer term momentum has been stronger than the latest pullback.
Scan beyond Mitani and see how other hydrogen and fuel cell linked plays stack up in our hand picked 24 resilient stocks with low risk scores for comparison.
Mitani appears to be a solid, diversified operator, with fuel cells adding extra appeal, yet the share price has just fallen sharply following a period of strong gains. Is the market now presenting genuine value, or simply tempering earlier enthusiasm?
Preferred P/E of 9.8x: Is it justified?
On recent numbers, Mitani trades on a P/E of 9.8x, compared with 10.3x for the broader JP Trade Distributors group and 13x for its closest peer set. The last close at ¥2,833 sits against this lower earnings multiple, which suggests the market is pricing Mitani at a discount to similar businesses.
The P/E ratio compares the current share price with earnings per share. For a diversified group like Mitani, with exposure across information systems, corporate supply, and lifestyle services, this metric gives a quick yardstick of how much investors are paying for each unit of profit.
Mitani has earnings growth over the past year of 26.1%, ahead of its 5 year average of 12.8% and above the Trade Distributors industry at 11.7%. In that context, a P/E below both the industry average and the 13x peer level indicates the market is pricing these earnings more conservatively than many comparables.
That gap is not trivial. Trading on 9.8x against 10.3x for the wider industry and 13x for peers points to a clear discount on current earnings power, alongside reported earnings quality and an improved net margin of 7.1% compared with 5.7% last year.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-earnings of 9.8x (UNDERVALUED)
Still, Mitani faces real pressure if hydrogen projects scale more slowly than hoped or if its broad mix of businesses reduces its focus on fuel cells.
Find out about the key risks to this Mitani narrative.
Another View On Mitani: Cash Flows Paint A Different Picture
While the 9.8x P/E suggests Mitani trades on a modest earnings multiple, the SWS DCF model points to a different story. At a last close of ¥2,833 against an estimated future cash flow value of ¥5,510.17, the shares screen as materially undervalued. Is this a genuine disconnect, or does it reflect cash flow assumptions that may not play out?
Look into how the SWS DCF model arrives at its fair value.
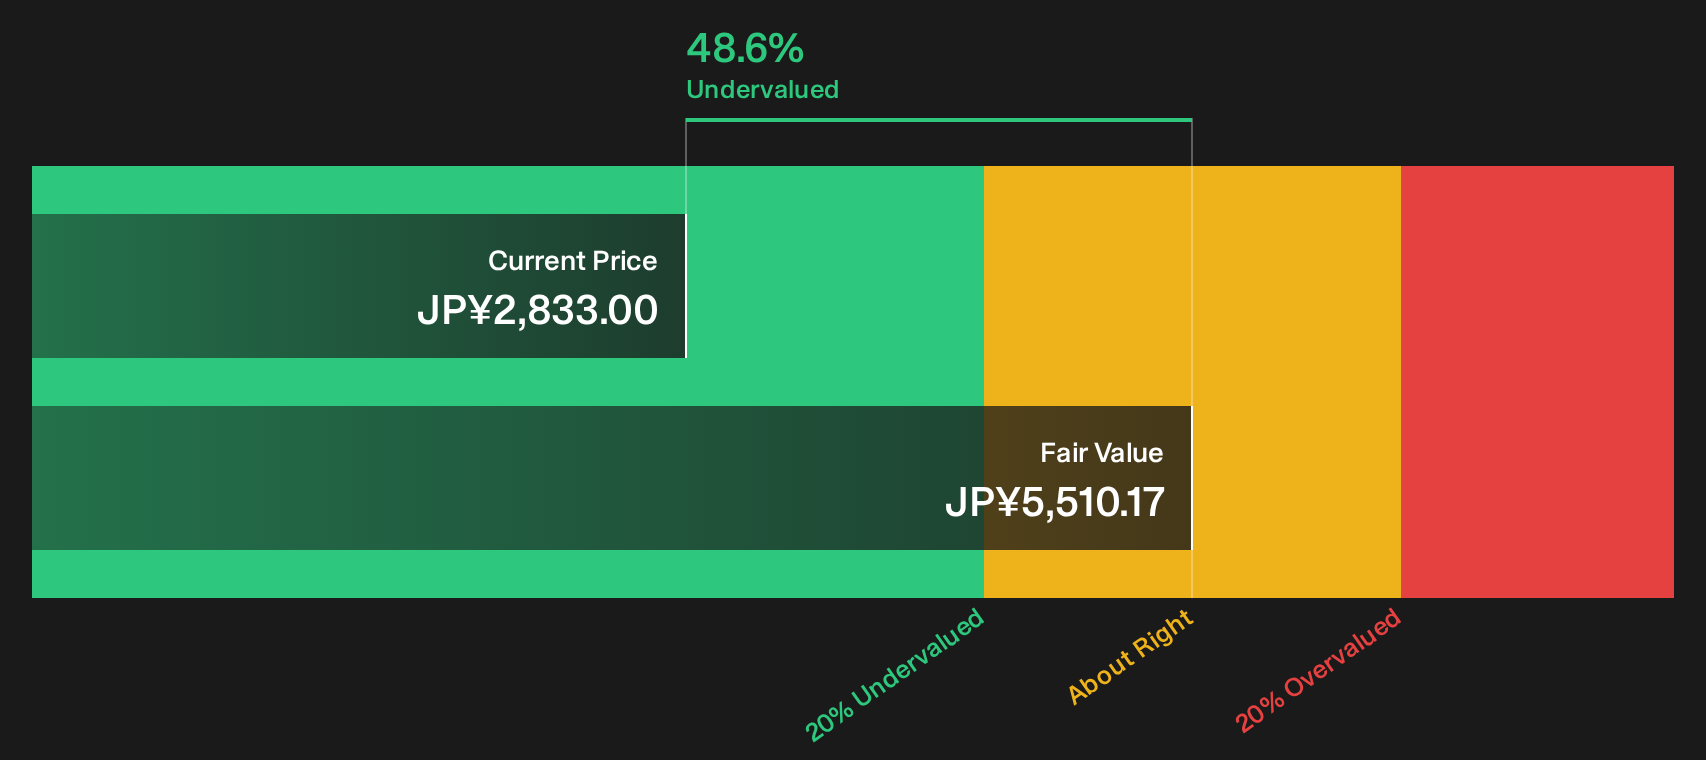
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Mitani for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Mitani so far. If you want to move beyond headlines and sentiment, review the data yourself and then check the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Mitani?
If Mitani has your attention, do not stop there. Broaden your watchlist with other clear setups that could suit different goals and risk levels.
- Hunt for mispriced quality by scanning our 15 high quality undervalued stocks that filters for robust fundamentals paired with restrained valuations.
- Strengthen your income stream by reviewing the 29 dividend fortresses that focuses on higher yielding businesses with the capacity to keep paying out.
- Prioritise resilience by running through the list of solid balance sheet and fundamentals (21 results) that highlights companies with sturdy finances and consistent fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com