


EN
Earnings Beat Might Change The Case For Columbia Sportswear Stock (COLM)
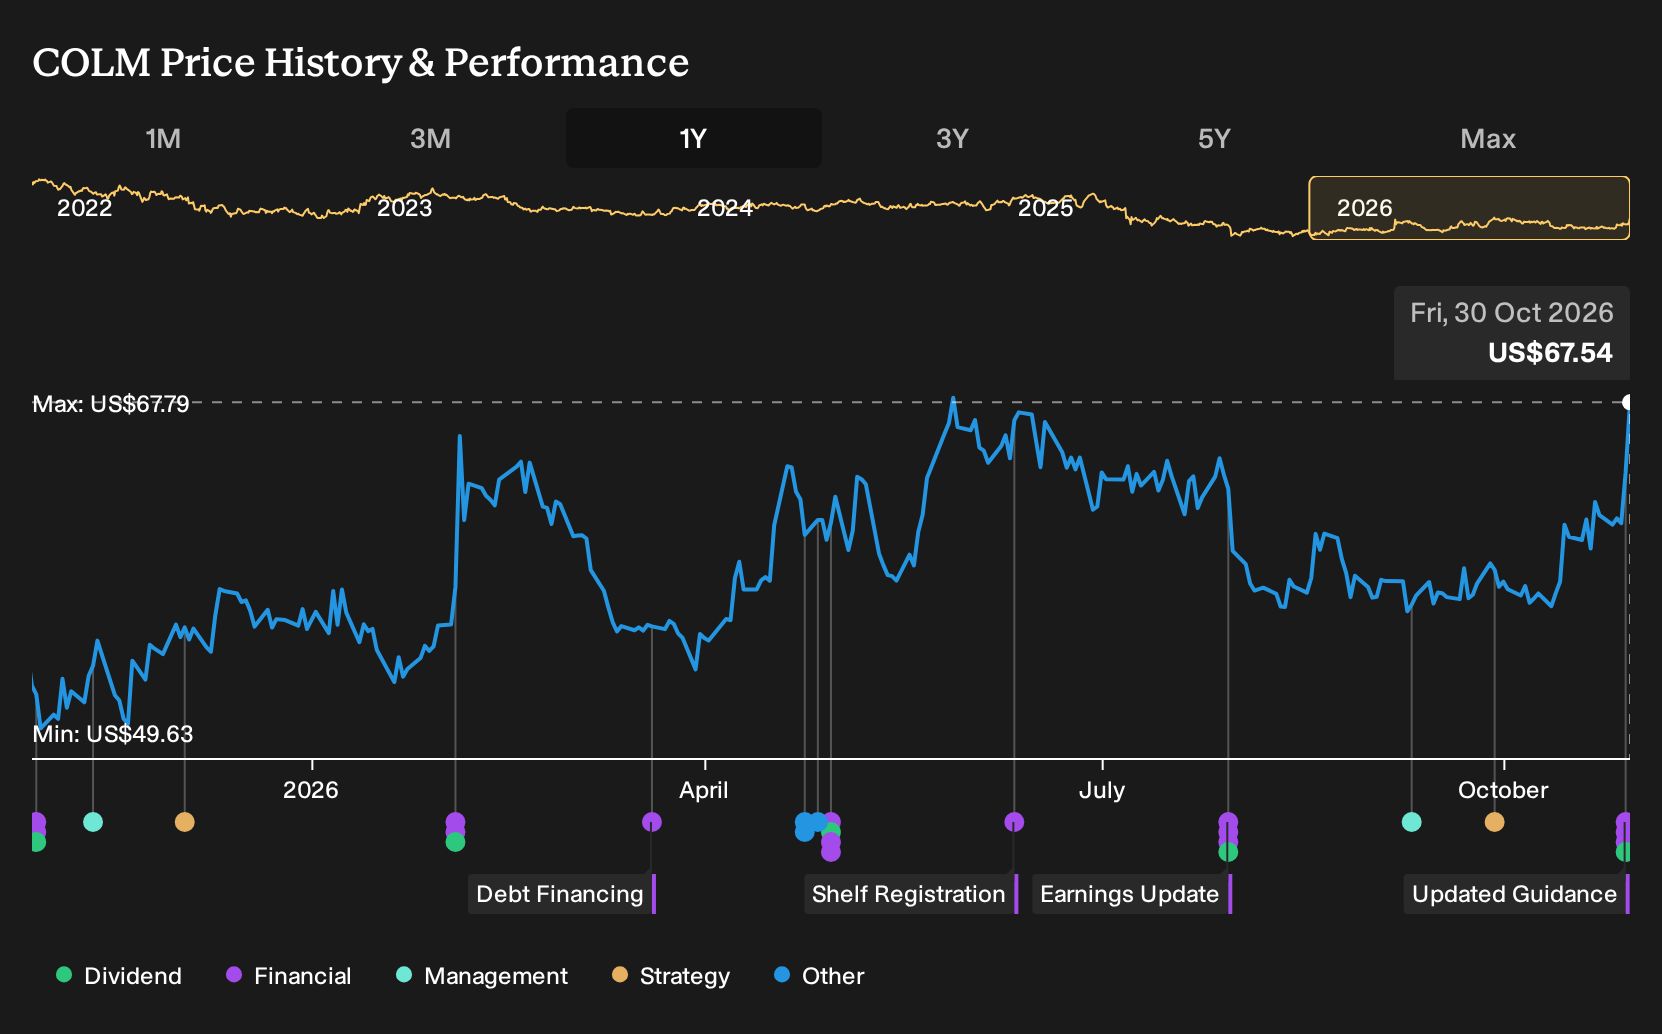
- Columbia Sportswear reported third quarter 2026 results with US$962.58 million in sales and US$84.74 million in net income, raised full year 2026 sales and EPS guidance, and issued detailed fourth quarter and full year outlook alongside a US$0.30 quarterly dividend declaration.
- The guidance now points to higher full year operating income of US$300 million to US$320 million and an operating margin range of 8.7% to 9.1%, supported in part by tariff refund benefits flowing through cost of sales and shipment timing that concentrates more Fall 2026 orders into the fourth quarter.
- Now the focus turns to how Columbia Sportswear's investment narrative adapts to raised 2026 earnings guidance built on stronger operating margins.
Columbia Sportswear Investment Narrative Recap
To own Columbia Sportswear, you need to believe the ACCELERATE and Profit Improvement efforts can keep turning into healthier orders, better product mix across footwear, women’s and PFG, and steadier direct to consumer economics. The raised 2026 outlook leans on higher operating margin, helped by tariff refunds and shipment timing, which supports that thesis but also concentrates execution risk into peak seasons.
The short term swing factor is whether U.S. softness stays manageable while international regions and e commerce keep doing more of the heavy lifting. The biggest risk still sits in margin pressure from tariffs, freight and promotions once the one time tariff benefits and timing boost roll off.
The most relevant fresh data point for that debate is the upgraded full year 2026 guidance. Columbia Sportswear now expects US$3.46b to US$3.50b in net sales and operating income of US$300 million to US$320 million, with an 8.7% to 9.1% operating margin and EPS of US$4.65 to US$4.90. Those numbers rely on cleaner execution through Fall and holiday, plus the remaining tariff refunds embedded in inventory.
That updated outlook ties straight into the main catalysts. It gives you a more concrete test of whether international strength, newer product platforms and the ACCELERATE brand work can offset U.S. pressure and cost inflation. It also frames the risk that once tariff refunds fade and shipment timing normalizes, underlying gross margin resilience and wholesale demand will have to do more of the work on their own.
Columbia Sportswear's current analyst narrative points to revenues of US$3.7b and earnings of US$211.3 million by 2029, based on assumptions that the top line will expand by 3.0% per year and that profit will rise by about US$5.3 million from US$206.0 million today to the 2029 consensus figure.
Uncover why Columbia Sportswear's fair value indicates a 3% potential upside to its current price that could close more quickly than many investors expect.
Exploring Other Perspectives
One alternate view focuses on tariff risk for Columbia Sportswear. The most bearish analysts were modelling only 2.7% annual revenue growth and earnings of about US$183.6 million by 2029 before this guidance, which is well below the baseline. That group effectively assumes that U.S. demand and higher trade costs have a greater negative impact. You can use today’s raised outlook as a fresh reference point and explore which version of the story aligns more closely with your own expectations.
Explore 2 other Columbia Sportswear fair value estimates, including one that suggests it could be worth just $69.83.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Columbia Sportswear research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Columbia Sportswear. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Columbia Sportswear's overall financial health at a glance.
Looking for more investment ideas beyond Columbia Sportswear?
Once you understand how Columbia Sportswear's story fits your portfolio, it can help to line it up against a few very different types of opportunities using the Simply Wall St Screener.
- If you want to stay focused on quality and valuation, compare Columbia Sportswear against a broader 29 high quality undervalued stocks that combine earnings support with disciplined balance sheets.
- For investors who care most about resilience, sort through a 30 resilient stocks with low risk scores that may better match a capital preservation mindset.
- If you are hunting for under the radar stories, scan a 18 high quality undiscovered gems that the wider market may not be paying much attention to yet.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com