


EN
Has VNET Group (NasdaqGS:VNET) Fallen Far Enough To Look Cheap On Sales?
VNET Group has seen its share price slide sharply in recent years, even as the business remains closely tied to China’s expanding data center and AI infrastructure build out. That disconnect puts a very specific question in front of you as an investor: whether today's valuation makes sense when judged against the sales the company is generating.
- Over the past 5 years, VNET Group's stock has fallen 80.2%, which puts the current price under a spotlight when you compare it to the revenue base behind the business.
- VNET Group's role in developing large scale data centers in Ulanqab for AI workloads can shape how investors think about the durability and potential growth of its sales over the coming years.
- Your read on VNET Group is one view; the desks covering it have another. See what analysts think VNET Group's shares could be worth.
The issue now is whether the current share price is adequately supported by VNET Group's sales when set against the Fair Ratio benchmark.
If you want to test the same sales based valuation question you are asking of VNET Group across a wider AI infrastructure theme, it can help to compare it with 54 AI infrastructure stocks.
Is VNET Group Still Cheap on Sales?
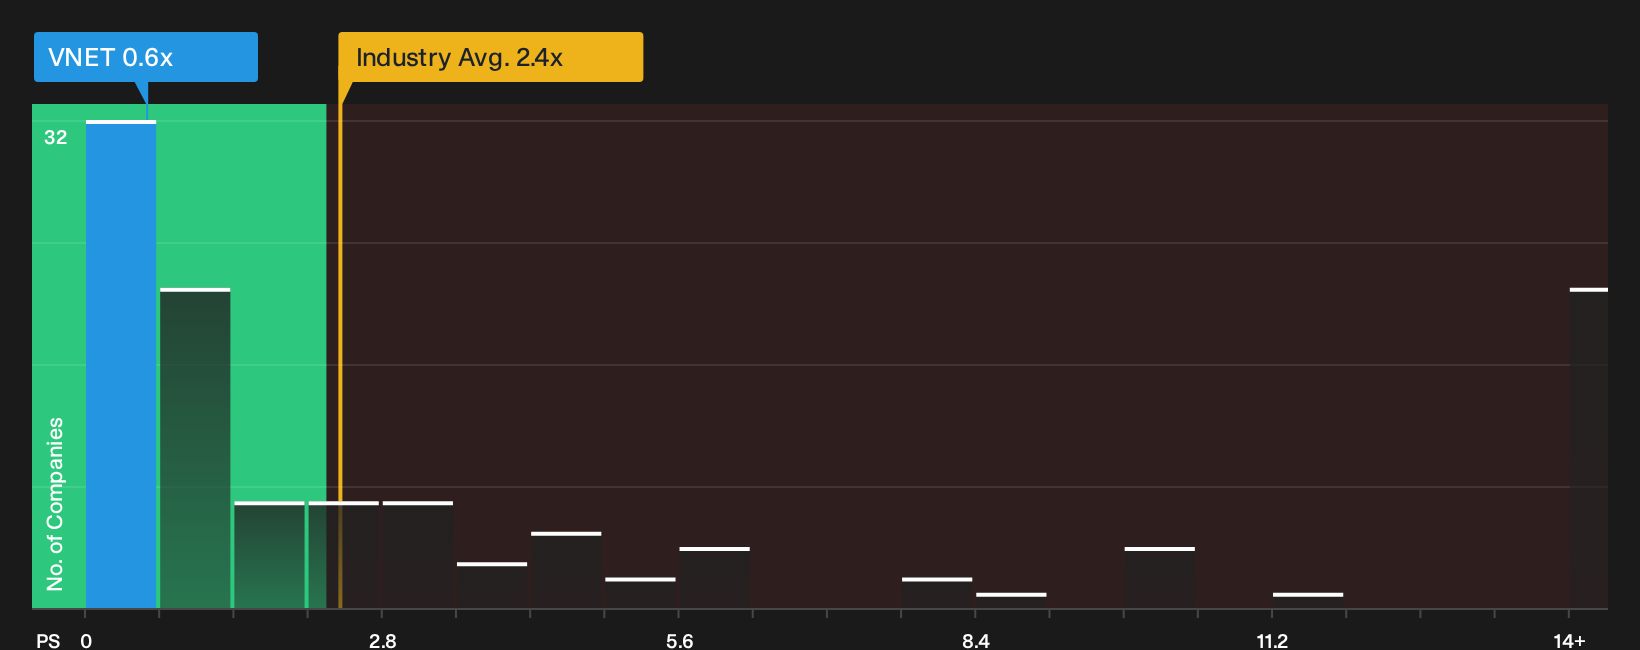
P/S is a useful lens for VNET Group because data center operators are often valued on revenue long before free cash flow turns positive. On this measure, the stock trades on a P/S of 0.6x, well below the IT industry average of 2.4x and under the peer group at about 1.8x. That puts a low price tag on each dollar of sales generated by the business today.
Because the Fair Ratio framework suggests VNET Group could justify a higher P/S given its mix of risks and fundamentals, the current 0.6x screens as undervalued on this method. News that Ulanqab is becoming an AI hub, with VNET involved in large scale data center projects, has highlighted the revenue base. Yet the P/S still sits at a meaningful discount to both the tailored Fair Ratio and sector benchmarks. Explore the numbers behind VNET Group's P/S valuation.
The VNET Group Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where VNET Group's valuation puzzle leaves off and explain which potential paths for future growth, margins and earnings would need to occur for the stock to be worth materially more or less than it is today. Instead of focusing on a single multiple or one model outcome, each narrative sets out the key assumptions behind its view of fair value so you can compare them with the actual results as they are reported on the Community page.
One of the top community narratives on VNET Group: 75% undervalued
"Active engagement with innovative financing mechanisms increases financial flexibility and can boost shareholder returns, while prudent debt management and strong liquidity help safeguard earnings..."
Discover why this Narrative puts VNET Group at 75% undervalued.
Before Acting On VNET Group's Valuation, There Is One More Piece To Check
Price tags and revenue multiples only tell part of the story, because the people steering VNET Group and the way their incentives are set up can heavily influence what happens next. See who runs VNET Group and how they are paid.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com