


EN
Kikusui Holdings (TSE:6912) Stock Faces Q2 Earnings Profit Squeeze
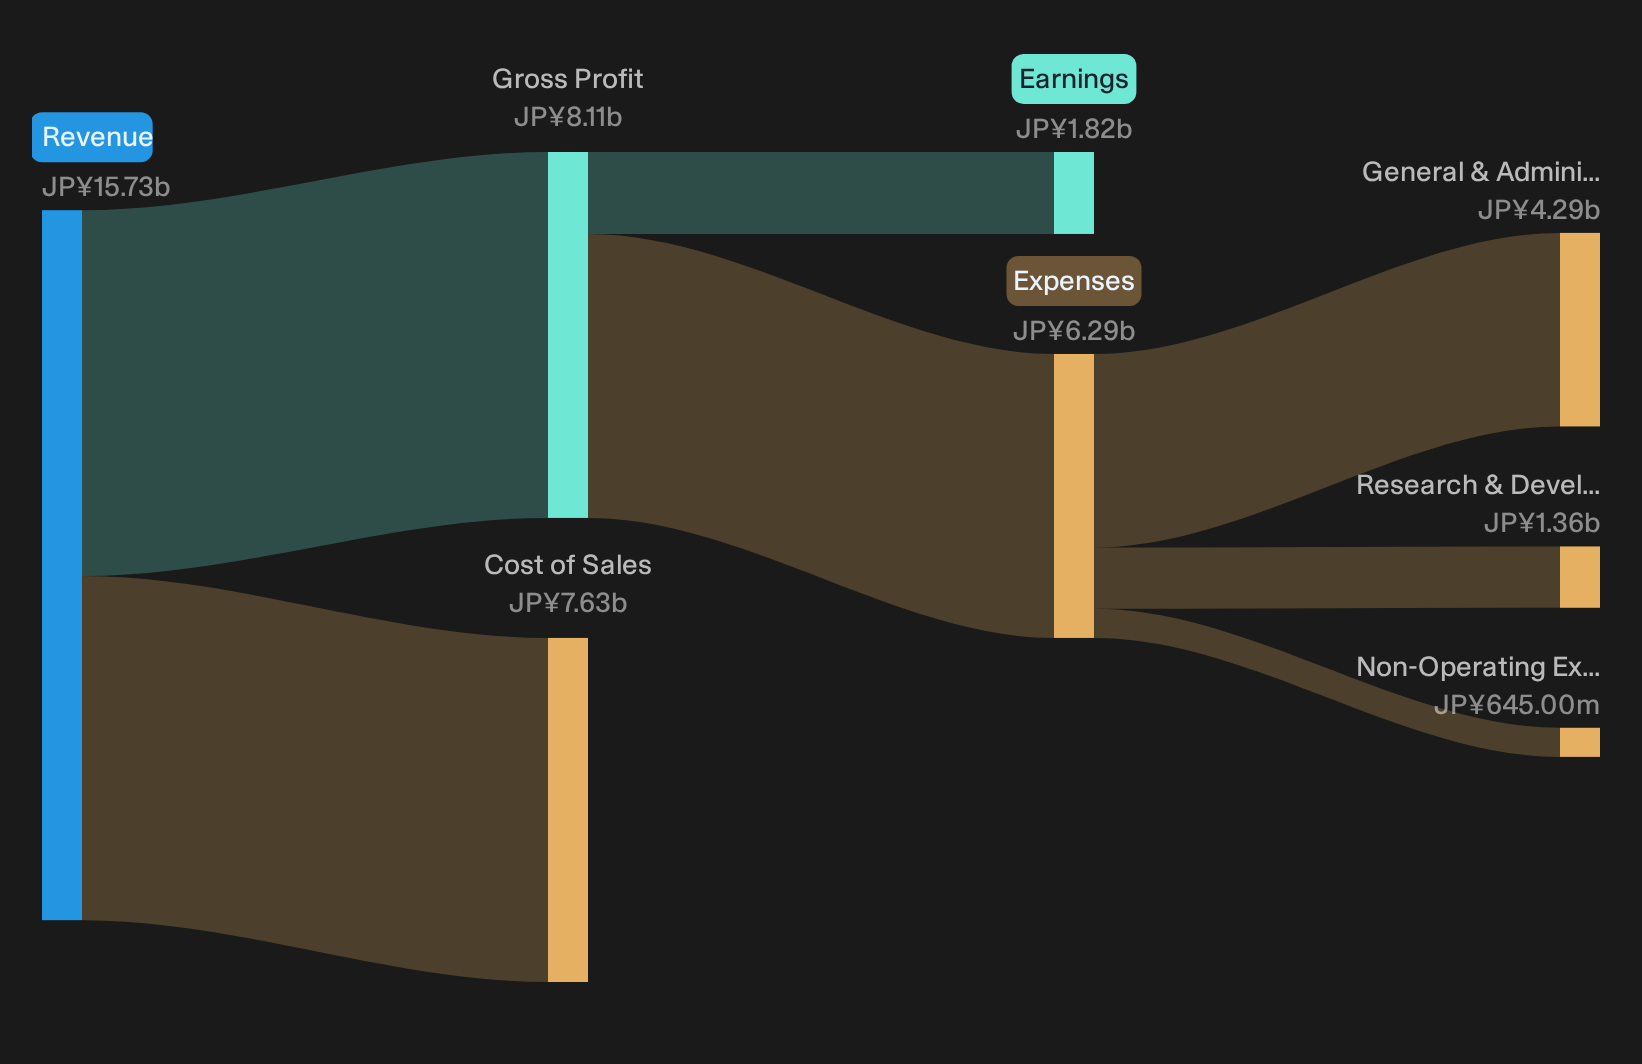
Traders have been marking Kikusui Holdings lower in recent weeks, with the stock down about 23% over the past month to ¥2,188 even before investors had time to fully process the latest figures. The company has now posted its Q2 2027 earnings, revealing quarterly net income of ¥302 million on revenue of ¥3,830 million, a clear squeeze from the prior quarter that jars with the firm’s stronger trailing 12 month profitability. The market reaction has been quick. The real question is whether this short term profit pressure meaningfully dents the longer term earnings story and current 10x P/E.
Love the 10x P/E entry point on Kikusui Holdings but uneasy about the squeeze in recent quarterly profits? Compare this setup against our screener of 15 high quality undervalued stocks to see how other companies with sturdier earnings stack up.
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs. Q2 2026): ¥3,830 million vs. ¥3,543 million (up about 8%)
- Net Income (Q2 2027 vs. Q2 2026): ¥302 million vs. ¥365 million (down about 17%)
- Basic EPS (Q2 2027 vs. Q2 2026): ¥36.21 per share vs. ¥43.84 per share (down about 17%)
- Trailing 12 Month Net Profit Margin (latest vs. prior year): 11.5% vs. 10.4% (improved profitability on recent trailing results)
Earnings tell you what Kikusui Holdings reported this quarter, but investors who care about valuation often focus on the cash being generated behind those profits. Looking only at Kikusui Holdings' recent cash flows, the stock could be a whopping 45% undervalued.
Revenue resilience keeps Kikusui’s bullish story alive
For investors leaning optimistic on Kikusui Holdings, the latest figures still leave some room to stay constructive. Quarterly revenue of ¥3,830 million is higher than the ¥3,543 million booked a year earlier, which fits the idea of a specialist supplier that can hold demand. Trailing 12 month net margin of 11.5% compared with 10.4% a year ago also backs the view that the business model can support healthier profitability through the cycle, even if not every quarter cooperates.
Profit squeeze tests the Kikusui Holdings earnings narrative
The other side of the tape is harder to ignore. Net income fell from ¥365 million to ¥302 million and basic EPS declined in line, which directly pushes against any simple “steady earner” story for Kikusui Holdings. That dip indicates that near term profit pressure is real, not just market mood. The recent share price slide over the last month then looks directionally consistent with this squeeze, suggesting investors are already treating earnings volatility as a practical risk, not a theoretical one.
After a 23% slide in a month, a profit squeeze and a volatile share price can be a harmful mix. Review the independent risk analysis for Kikusui Holdings which shows 2 important warning signs to see whether these visible cracks hint at deeper structural issues or other quietly building red flags.Hunt For Mispriced Earnings Power
Kikusui Holdings just reminded you how quickly sentiment can swing when profits tighten and the share price responds. The real opportunity is spotting stocks that could be undervalued before the market recognises their earnings power.
- Company 1 - 39% below our estimate - lets sponsors trial virtual performers so campaigns move faster than traditional celebrity partnerships.
- Company 2 - 27% below our estimate - sells precision grinding tools that become embedded once factory engineers standardise production lines.
- Company 3 - 24% below our estimate - turns messy enterprise data into tailored dashboards that teams adopt once spreadsheets stop scaling effectively.
That is three of the list. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com