


EN
3 Fast Growing Insider Owned Stocks To Watch In October 2026
AI spending plans are suddenly under pressure after OpenAI cut its fundraising target and Meta received a credit warning over cash flow and heavy investment. Market confidence in big tech growth stories looks shakier, which puts more attention on smaller companies where insiders already have substantial skin in the game. This article highlights three fast growing, high insider ownership stocks from our screener that may deserve a closer look.
The three stocks highlighted here offer a compelling starting point if you want exposure to fast growing businesses where insiders are heavily aligned with outside shareholders. However, if you want the strongest names, these 373 high growth high conviction stocks are the top of the list.
CoreWeave (CRWV)
Overview: CoreWeave runs a cloud infrastructure platform focused on GPU compute that powers large-scale AI training and inference, with other services like storage and visual effects contributing alongside its core AI workload offering.
Operations: CoreWeave generates about US$7.6b in data processing revenue, with roughly US$7.0b from the United States and US$577 million from other regions.
Market Cap: US$33.5b
CoreWeave matters for this fast-growing, insider-backed theme because its AI-focused cloud platform directly touches the heaviest compute workloads where demand can move quickly and materially.
"The financial structure is heavily weighted toward fixed debt and non-negotiable depreciation cycles."
What ultimately happens to CoreWeave’s margins and growth path depends on how one intense cost pressure and customer behavior trend intersect over time.
That collision of costs and customer behavior is exactly where the full narrative for CoreWeave lays out how CoreWeave’s model could either compress or accelerate.

Sansan (TSE:4443)
Overview: Sansan provides cloud-based contact, sales activity, invoicing, contract, and data quality tools that help businesses share leads, manage pipelines, and strengthen CRM data.
Operations: Sansan generates about ¥48,865 million from its Sansan/Bill One cloud segment, ¥7,143 million from Eight, and ¥446 million from other services, all in Japan.
Market Cap: ¥273.8 billion
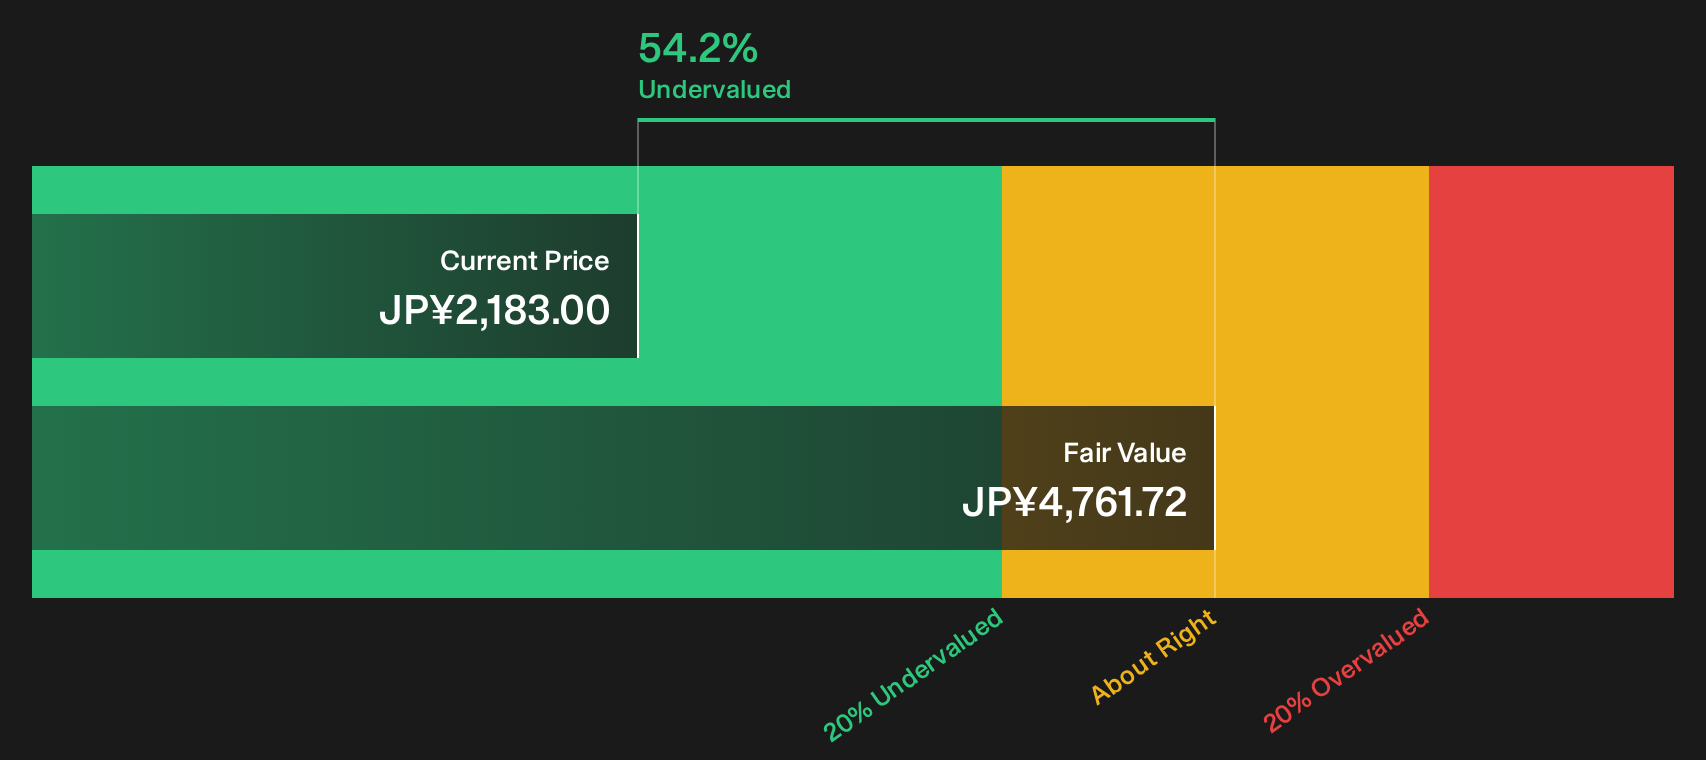
Sansan aligns with the Fast Growing Stocks With High Insider Ownership theme because its cloud contact and CRM data platform is designed for recurring, scalable usage, and the shares trade at a large discount to estimated fair value.
That discount is exactly why the DCF valuation analysis for Sansan can be worth a look if you want to see what the market might be missing.
Micronics Japan (TSE:6871)
Overview: Micronics Japan develops and sells semiconductor test equipment such as probe cards and wafer probers, alongside body measuring and LCD inspection tools.
Operations: Micronics Japan generates ¥84,868 million from its Probe Card Business and ¥1,391 million from its TE Business across Japan, South Korea, Taiwan and other regions.
Market Cap: ¥439.5 billion
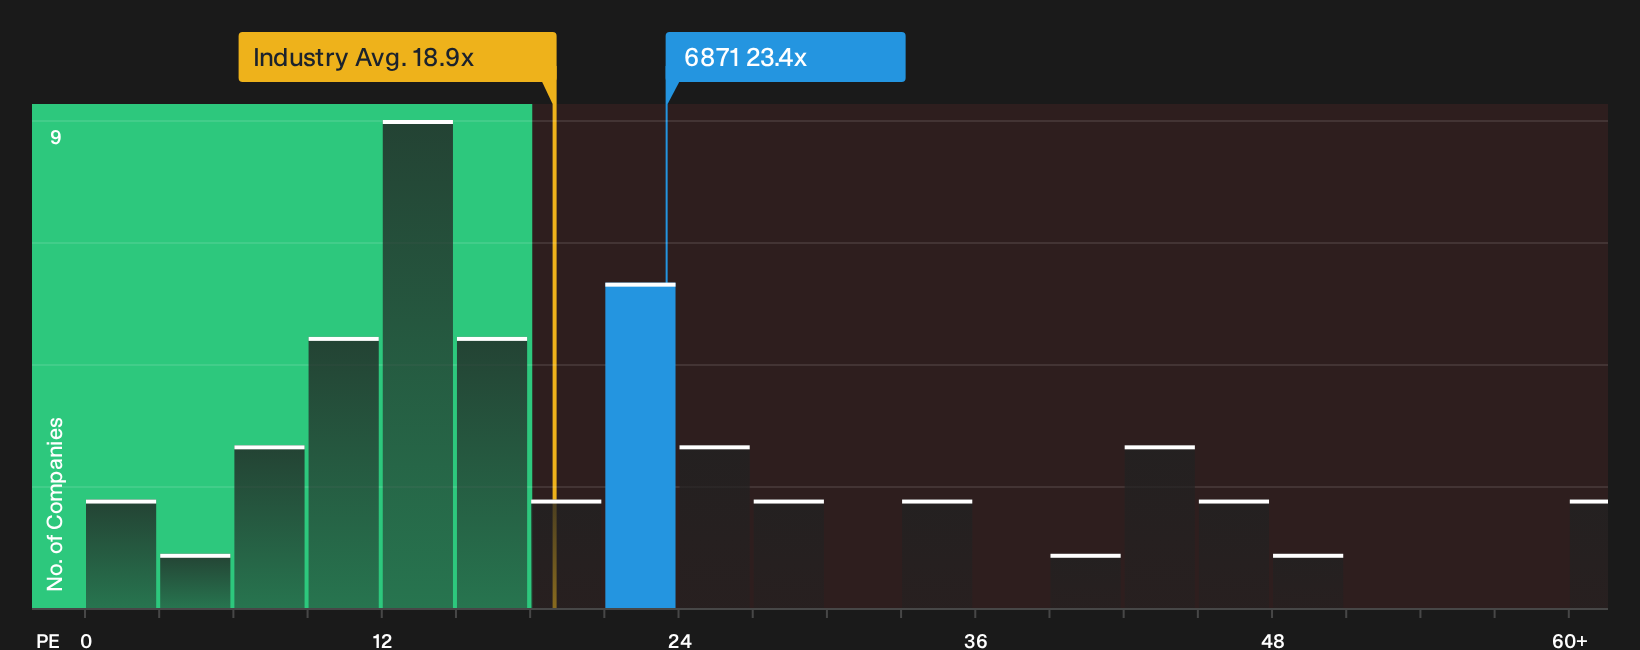
Micronics Japan ties this screener together because almost all its revenue comes from probe cards and related testing hardware used in semiconductor manufacturing. Earnings grew 89.4% year on year and company guidance indicates strong demand. However, the premium P/E suggests that much depends on how memory chip testing orders interact with any unexpected pressure on capacity and pricing.
That premium P/E makes the next step clear. The 2 key rewards and 1 important major warning sign lays out where Micronics Japan’s upside could decouple from testing demand swings.
Seeking Fresh Alternatives Before They Fly
Fresh breakout stories rarely stay quiet for long. Once momentum is caught by the crowd, the best entry points start dropping away. Scan the next wave now and get in early.
- Spot potential turnarounds with real balance sheet strength by running the curated list of solid balance sheet and fundamentals (25 results) before the market fully prices in their financial resilience.
- Ride structural infrastructure shifts by zeroing in on curated 39 power grid technology and infrastructure stocks that could benefit as grids modernize while the opportunity is still under the radar for now.
- Follow the next wave of industrial automation by targeting hand picked 95 robotics and automation stocks before capital chases the late stage stories instead of the early compounding opportunities.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com