


EN
Greatland Resources And 2 Australian Undervalued Stocks To Own
Tech giants are pouring an estimated $828b into AI infrastructure this year, and the focus on cash hungry projects has sharpened attention on dependable cash generation. That sets the stage for Australian companies that quietly produce solid cash flows yet trade below their estimated fair value. This article highlights three such opportunities from a specialist cash flow screener that filters for value, and explains why each one deserves a closer look.
The three companies covered below are a small sample from this value focused universe, and the full screen surfaced 6 more businesses with equally compelling cash flow stories that are not detailed in this article.
To go straight to the source and identify ideas that fit your own filters, analyze the full list using the Undervalued Stocks Based On Cash Flows screener.
Greatland Resources (ASX:GGP)
Greatland Resources is a gold and copper developer whose Havieron project in Western Australia is central to the cash flow story this screener targets.
Greatland Resources is a gold and copper producer anchored by its Havieron project, which generated about A$2.26b from the Telfer Havieron segment and underpins the cash flow theme, and the business carries a market value of roughly A$6.62b.
"The primary driver of Greatland’s future is the gold price. As a single-asset developer moving toward production, it offers significant operational leverage to gold."
What happens if one key cost pressure shifts just as that leverage to future cash flows starts to really matter?
When that cost pressure shifts, read the full narrative for Greatland Resources to see how Greatland Resources’ cash flows could accelerate or stall under different gold and inflation paths.

Ansell (ASX:ANN)
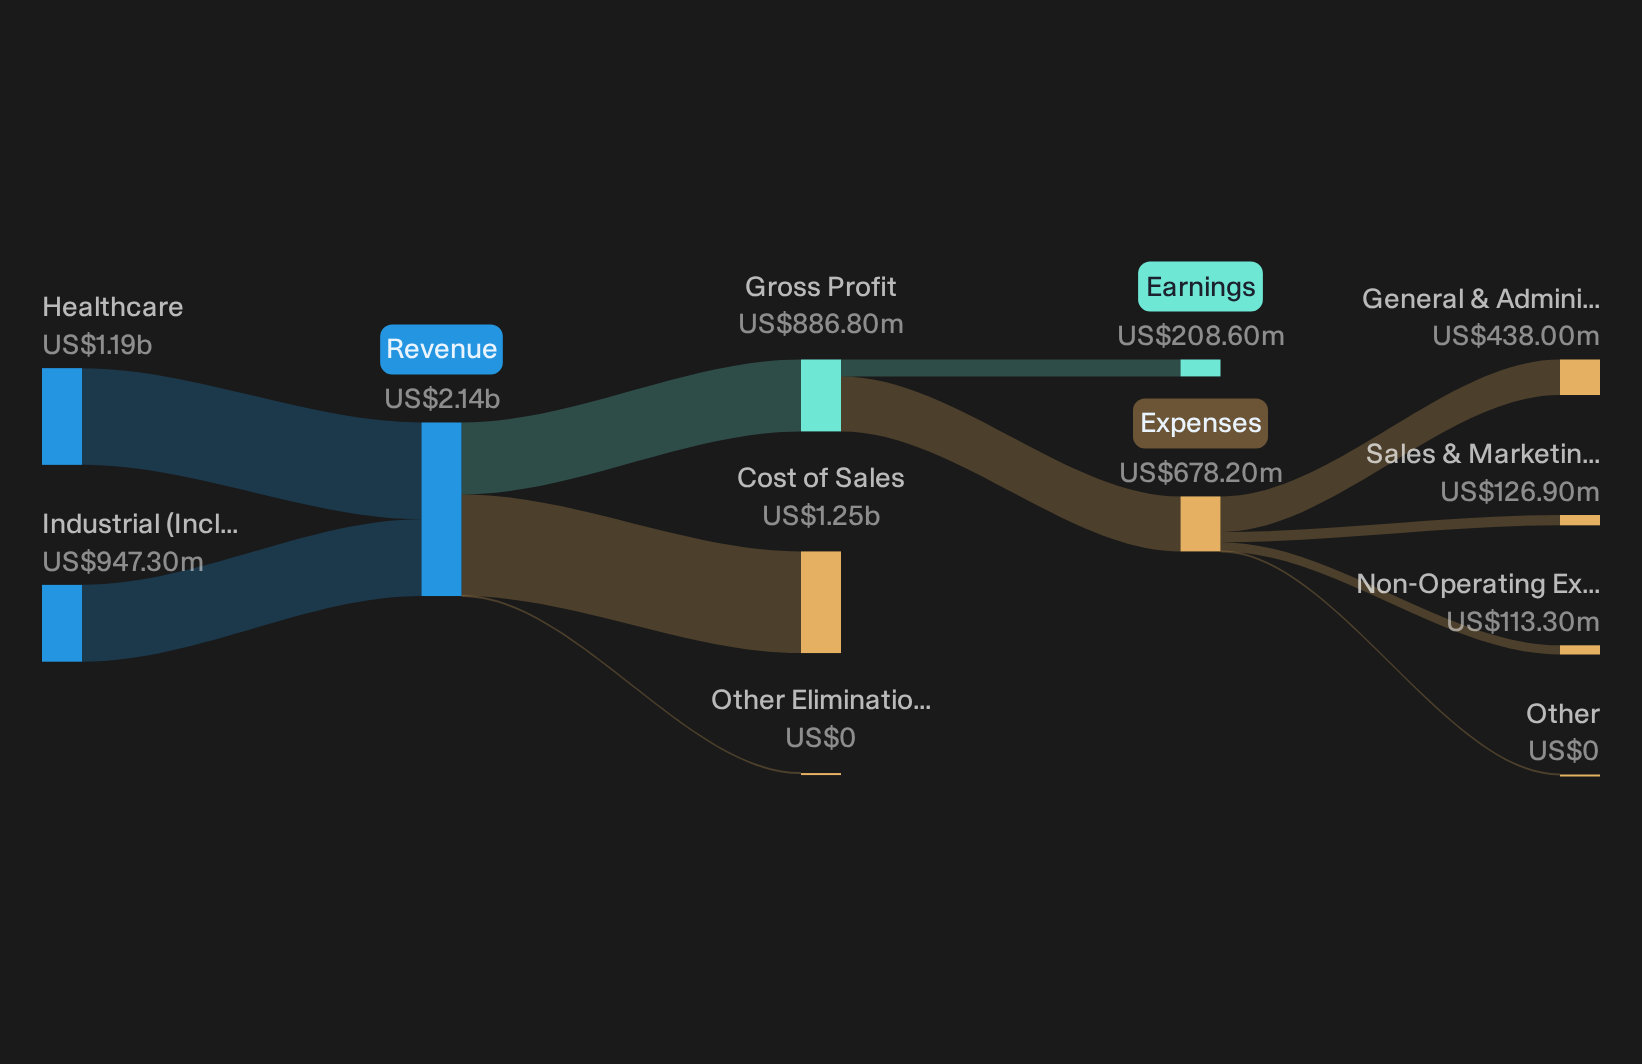
Ansell is a global personal protective equipment specialist, and its Healthcare glove and consumables line captures the recurring cash flow focus of this screener, with Healthcare generating about US$1.19b and Industrial US$947 million in revenue, and the company valued at roughly A$6.31b.
For investors following cash flow driven value ideas, Ansell matters because a large, repeat purchase glove business can create durable income streams that a discounted cash flow model can measure more clearly than one off projects.
"Ansell is well placed to capture increased structural demand in PPE, driven by tightening workplace safety regulation, rising healthcare and hygiene standards, and accelerating industrialisation in emerging markets."
The real swing factor is how one cost side shift interacts with that steady glove demand to shape future profitability and reinvestment capacity.
That cost shift is exactly what the full narrative for Ansell unpacks in detail, showing how different pricing and input shocks could quietly reshape Ansell’s cash engine.
Origin Energy (ASX:ORG)
Origin Energy is a diversified energy group that explores and produces natural gas, generates and sells electricity, and offers broadband, solar and e-mobility services, with A$15.26b from Energy Markets and A$307 million from Integrated Gas and a market value near A$21.01b.
Origin Energy matters here because its upstream gas fields feed a cash engine that can anchor discounted cash flow valuations, while the broader retail and renewables platform adds extra levers for value.
"Investor expectations around Origin Energy’s exposure to electrification remain high. Management guidance points to efficiency gains and distributed resources partly offsetting new residential load, which could limit long term electricity revenue growth if demand stays broadly flat."
What really moves the needle is how one shifting pressure on that cash engine plays out for margins and long term returns.
That shifting pressure is exactly what the full narrative for Origin Energy breaks down, revealing where Origin Energy’s cash flows could accelerate, decouple from electricity volumes and surface overlooked upside.

Seeking Alternatives Beyond These Cash Engines?
Fresh ideas move first. By the time every chart shows a breakout, early entries are already flying. Scan these under the radar lists before the momentum is caught, and consider acting sooner rather than later.
- Spot resilient balance sheets before they hit the spotlight by running the list of solid balance sheet and fundamentals (12 results) to zero in on businesses built to handle shocks.
- Explore structural demand in electricity, grids and renewables by scanning the 39 power grid technology and infrastructure stocks and focusing on operators behind evolving energy infrastructure.
- Look for real cash generators across AI chip fabs, data centers and tooling with the 54 AI infrastructure stocks to track the picks and shovels of this trend.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com