


EN
Sanyo Denki (TSE:6516) Stock Price Falls Despite Strong Q2 Earnings
Sanyo Denki entered this Q2 2027 report with a weak chart, the stock down over 13% in both the past month and the past quarter, even though the P/E sat below peer levels. The headline today is simple. Earnings per share reached ¥94.81 on revenue of ¥33,779m, marking another quarter where profit quality screens as high. Price action now needs to decide whether the recent slide was an overreaction to sentiment while the underlying electrical equipment business quietly tightened its earnings engine.
Love Sanyo Denki’s solid earnings per share but worried the weak share price is signaling a value trap instead of an opportunity? Benchmark it against companies that pair compressed valuations with resilient fundamentals in our 15 high quality undervalued stocks
Q2 2027 Earnings Summary
- Revenue (Q2 2027 vs Q2 2026): ¥33,779m vs. ¥26,633m (up about 27%)
- Net Income (Q2 2027 vs Q2 2026): ¥3,367m vs. ¥2,458m (up about 37%)
- Basic EPS (Q2 2027 vs Q2 2026): ¥94.81 vs. ¥69.26 (up about 37%)
- Trailing 12M Basic EPS (Q2 2027 vs Q2 2026): ¥324.34 vs. ¥211.64 (up about 53%)
Prefer clean charts over slogging through raw figures and dense earnings tables? See Sanyo Denki’s full financial picture, including a clear visual view of valuation and profitability trends in our company report for Sanyo Denki.
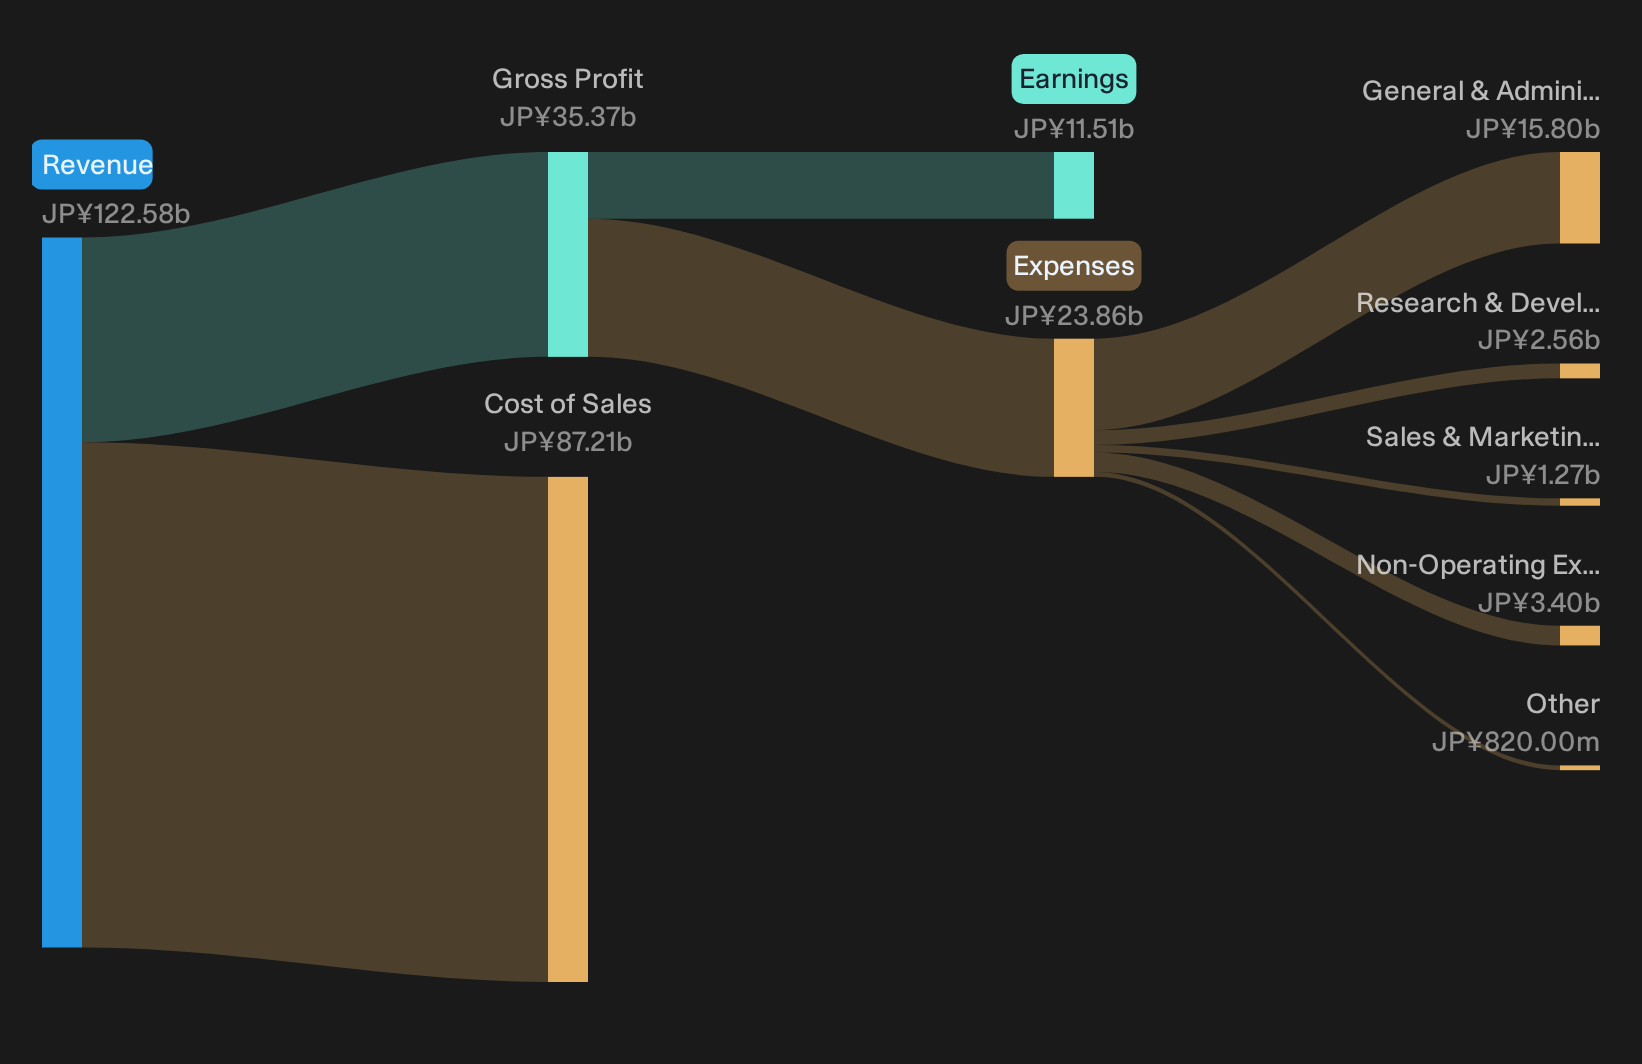
Sanyo Denki: Earnings Back The Picks And Shovels Story
Sanyo Denki’s automation and infrastructure pitch now has firmer footing. Revenue of ¥33,779m and net income of ¥3,367m both sit well above the prior-year quarter, and basic EPS of ¥94.81 tracks that direction. Trailing 12 month EPS of ¥324.34 versus ¥211.64 points to healthier earnings power backing the picks and shovels narrative across robotics, semiconductors, and ICT infrastructure. For a supplier tied to customer capex cycles, this kind of broad based top line and profit progress suggests the underlying industrial tech model is holding up.
Sanyo Denki: Share Price Weakness Versus Earnings Strength
The chart tells a different story. The stock is down about 13% over both 30 and 90 days, and roughly 1% over the past week, even as EPS and net income move higher. That disconnect keeps value trap worries alive for Sanyo Denki, especially for investors who focus heavily on recent price action. At the same time, the earnings pattern and rising trailing 12 month EPS argue that near term business risks look less severe than the share price performance implies right now.
After a 13% slide in three months and a dividend that is not well covered by free cash flows, it is worth asking whether Sanyo Denki’s share price volatility is an isolated signal or part of a wider pattern of fragility in the business model. Review the full risk analysis for Sanyo Denki which shows 2 important warning signsHunt For Quiet Earnings Disconnects
Sanyo Denki reports earnings that diverge from its recent share price move. The real opportunity is finding stocks that could be undervalued before the market corrects them.
- Company 1 - 32% below our estimate - offers a unified payment stack connecting card, carrier, and post-pay tools through one gateway.
- Company 2 - 24% below our estimate - sells data and form software that converts scattered records into actionable dashboards and automated billing workflows.
- Company 3 - 34% below our estimate - supplies electronic materials that help device makers achieve thinner displays and more reliable sensor performance.
Those are three of them. See the full list of 15 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com