


EN
Balchem (BCPC), What Is Behind The Fresh Attention?
Balchem (BCPC) just put fresh numbers on the table, reporting third quarter results alongside an update on its ongoing share repurchase activity that has drawn renewed attention from investors.
Balchem’s recent third quarter release and buyback update have landed against a backdrop where the share price is up 10.36% year to date and the 1 year total shareholder return is 11.50%, while a 3 year total shareholder return of 42.83% points to momentum that has cooled in the very short term but remains intact over a longer stretch.
Scan how Balchem’s mix of earnings momentum and buybacks compares with other companies showing similar traits in the 29 high quality undervalued stocks.
Earnings are ticking higher, buybacks are in motion and Balchem shares have already moved this year. Is it better to lean in now or hold out for a cleaner entry on valuation?
Most Popular Narrative: 19% Undervalued
Balchem’s most followed narrative places fair value at $209.25, above the last close at $169.98. This frames today’s debate around how much of its balance sheet capacity and end market recovery is already reflected in the share price.
The expanded US$650 million revolving credit facility, low net leverage of 0.3x and ongoing share repurchases give Balchem financial flexibility to fund additional product development, capacity projects and acquisitions that can add to future revenue and adjusted EBITDA.
See why 2 investors see Balchem as 19% undervalued.
Result: Fair Value of $209.25 (UNDERVALUED)
Still, the Balchem narrative depends on EU antidumping support and manageable petrochemical and freight costs, and pressure on either could quickly challenge today’s optimism.
Find out about the key risks to this Balchem narrative.
Another View: Balchem Through The P/E Lens
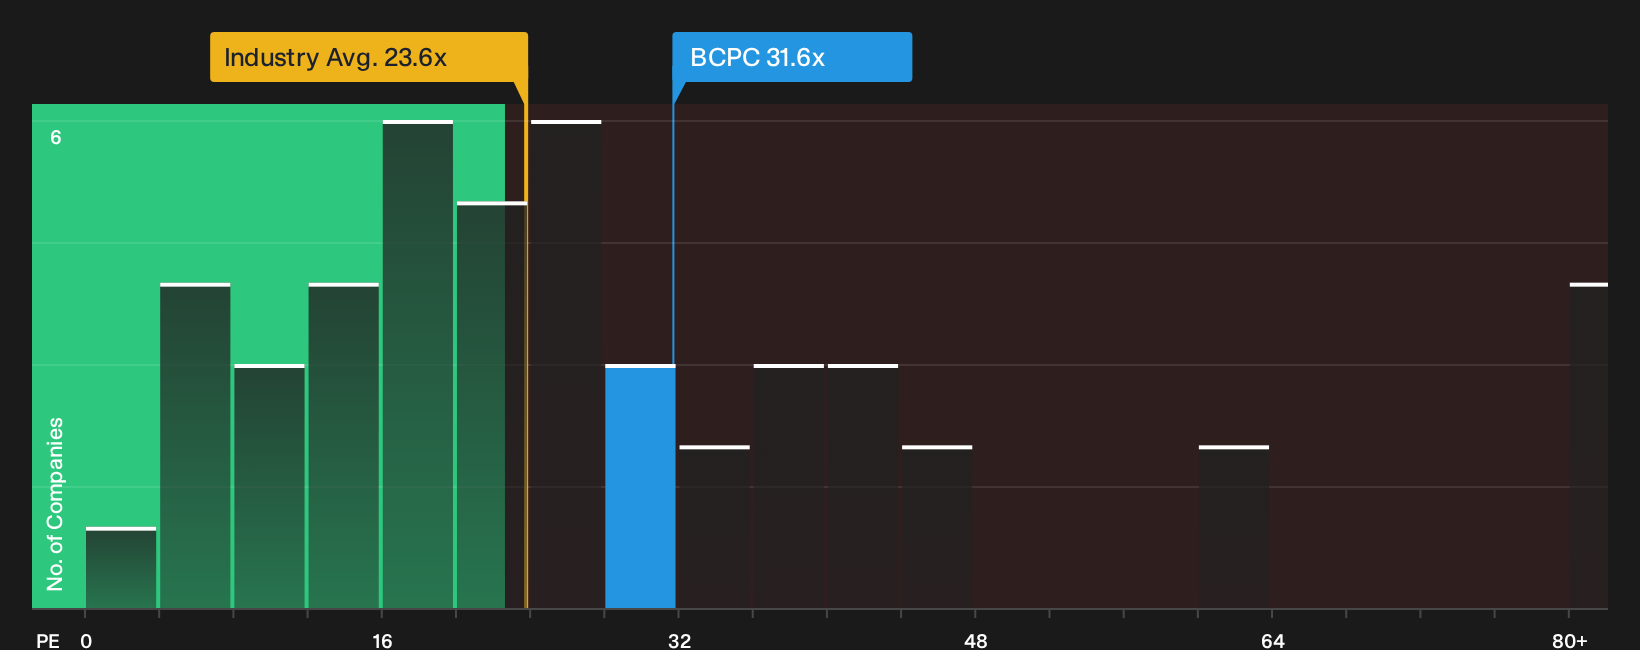
On the flip side of that fair value narrative, Balchem looks expensive on a simple earnings multiple. The stock trades on a P/E of 31.6x, compared with 23.1x for the US Chemicals industry, 26.6x for peers, and a fair ratio of 15.4x that the market could move toward over time.
That gap points to a rich valuation that could compress if sentiment cools, even if the business keeps growing. The question is how comfortable you are relying on multiple support instead of the cash flow story here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment around Balchem is split, and that is exactly why your own work matters. Move quickly while this debate is fresh and stress test the 4 key rewards.
Looking For More Investment Ideas Beyond Balchem?
If you stop with Balchem, you risk missing other opportunities that fit your style, so consider putting the broader market to work for you today.
- Target resilient cash generators that combine quality and attractive pricing by running a focused search through the 29 high quality undervalued stocks.
- Prioritise capital preservation and steadier returns by filtering for companies with stronger financial footing using the 30 resilient stocks with low risk scores.
- Hunt for underfollowed opportunities with cleaner fundamentals by scanning the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com