


EN
Corning (GLW) Raised Guidance After AI Deals, Is The Pullback A Bargain?
Corning (GLW) has become a focal point for investors after reporting strong third quarter and year to date results, followed by higher guidance tied to optical communications demand and AI focused data center agreements.
Despite strong Q3 results and upbeat guidance, Corning’s recent momentum has cooled, with the share price down about 20% over the past month and 11% over 90 days even as the year to date share price return is 36% and the 1 year total shareholder return is nearly 40%.
Spot 54 AI infrastructure stocks that, like Corning’s optical business, are tied directly to AI data center buildouts and could be setting up their next major move.Corning now pairs strong reported earnings and upbeat AI linked contracts with a sharp pullback in the share price. Does that reset leave the risk reward skewed toward buyers or toward investors taking some caution here?
Most Popular Narrative: 33% Undervalued
Corning’s most followed narrative pegs fair value at about $182.76, well above the last close of $123.31. This frames today’s pullback against a richer long term story grounded in AI infrastructure and energy transition spending.
The numbers imply that Corning’s current valuation treats the stock as if execution risk, equity issuance and mixed end market conditions fully offset the multibillion long term growth opportunities in AI data centers, U.S. solar and photonics. This underpins the view that the shares are undervalued.
See why 107 investors see Corning as 33% undervalued.
Result: Fair Value of $182.76 (UNDERVALUED)
Still, the Corning story can break if Springboard execution wobbles, or if further equity raises dilute earnings more than current AI and solar plans assume.
Find out about the key risks to this Corning narrative.
Another View: Corning Through The Earnings Multiple
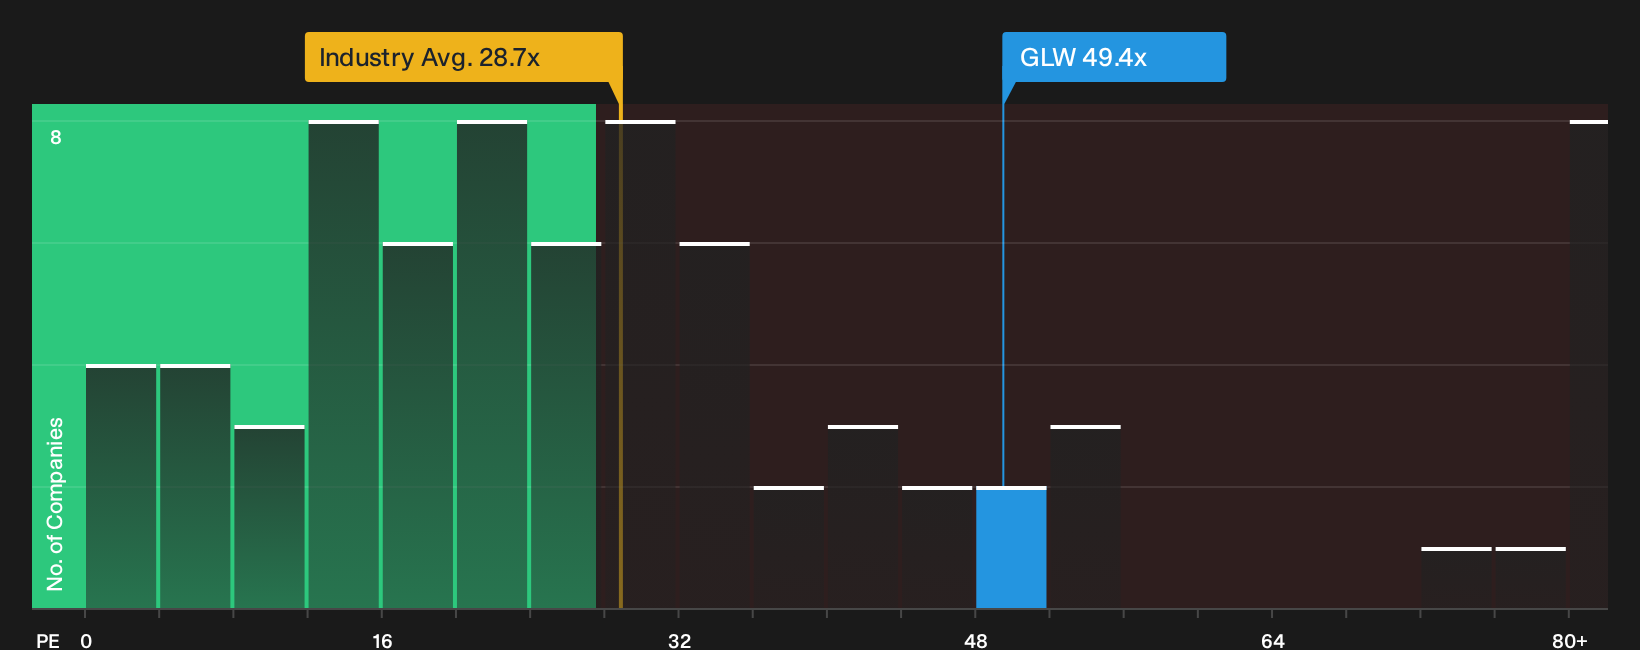
That DCF style fair value near $182.76 paints Corning as undervalued, yet the current P/E of 49.4x is well above the US Electronic industry on 28.7x, and only slightly below a peer average of 63.7x and a fair ratio of 52.9x. Is that a bargain or just a lot of optimism priced in?
To see how this richer earnings multiple stacks up against the underlying assumptions and sector trade offs, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Sentiment on Corning is split, which is exactly when it pays to check the data yourself and move quickly to form an independent view. To see how the positives stack up against the pressure points in one place, review the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Corning?
If Corning has sharpened your focus on opportunities tied to clear stories and solid data, do not stop here. Broader research can strengthen every decision you make.
Use the Simply Wall Street Screener to spot three very different sets of opportunities before other investors crowd in.
- Target potential mispricings by scanning our 29 high quality undervalued stocks that combine robust fundamentals with prices that may not fully reflect their underlying business strength.
- Build a steadier income stream by reviewing 5 dividend fortresses that focus on higher yields paired with balance sheets that support ongoing payouts.
- Protect your downside by concentrating on 30 resilient stocks with low risk scores that score well on financial resilience and may help smooth out portfolio swings when markets get choppy.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com