


EN
Sanrio Company (TSE:8136) Ends China Sensitive Tie Up, Is The Valuation Still Justified?
Sanrio Company (TSE:8136) has scrapped a collaboration with a Japanese TV spy drama after criticism from China over portrayals of Chinese intelligence agents, putting fresh attention on its exposure to Chinese consumers.
At a ¥1,254.0 share price, Sanrio Company has seen a 30-day share price return of 5.60% and a year-to-date share price gain of 26.79%. However, total shareholder return over the past year declined 11.16% even after a very large 5-year total shareholder return of about 6x, which indicates that recent momentum has cooled despite strong longer term compounding.
Scan opportunities with similar brand and regional exposure by reviewing the hand picked 71 high quality undiscovered gems that could be flying under the radar next to Sanrio Company.
Sanrio Company shares have climbed in 2026, but given the recent pullback from last year’s highs and fresh questions around China exposure, should you lean in at today’s ¥1,254 price or hold fire for a cheaper entry as valuation comes into focus?
Price-to-Earnings of 27.2x: Is it justified?
Sanrio Company trades on a P/E of 27.2x, which is a rich tag against its ¥1,254 last close and points to an overvalued setup compared to peers at current levels.
The P/E ratio compares the share price with earnings per share and, for a consumer brand and licensing group like Sanrio Company, it reflects how much investors are willing to pay for each unit of current profit. A higher multiple often signals that the market is pricing in stronger profitability or steadier earnings than many retailers, especially where characters, content and licensing provide multiple revenue streams.
Recent figures show earnings growth of 22.6% over the past year and revenue growth of 9.6% annually, with high quality earnings and a current net profit margin of 27.6%. Forecasts point to earnings increasing 10.5% per year and revenue rising 9.6% per year, both ahead of the broader JP market. This can help explain why investors accept a premium P/E even as that growth is not described as very high compared with fast growing sectors.
The gap becomes starker against benchmarks. At 27.2x, the P/E for Sanrio Company is more than double the JP Specialty Retail industry average of 13.2x and well above the peer average of 11.6x. It also exceeds an estimated fair P/E of 22.3x, which indicates that the current valuation stretches meaningfully beyond a level the market could move towards if expectations cool.
Explore the SWS fair ratio for Sanrio Company.
Result: Price-to-Earnings of 27.2x (OVERVALUED)
Still, investor confidence in Sanrio Company could be tested if further China related backlash spreads to licensing partners or if premium pricing meets resistance from consumers.
Find out about the key risks to this Sanrio Company narrative.
Another view on Sanrio Company: DCF says the price looks cheaper
The P/E screen presents Sanrio Company as expensive, yet our DCF model suggests a different picture. At ¥1,254 the shares trade below an estimated future cash flow value of ¥1,439.82, which points to a potentially undervalued setup if those cash flow assumptions hold up. Which signal would you put more weight on?
Look into how the SWS DCF model arrives at its fair value.
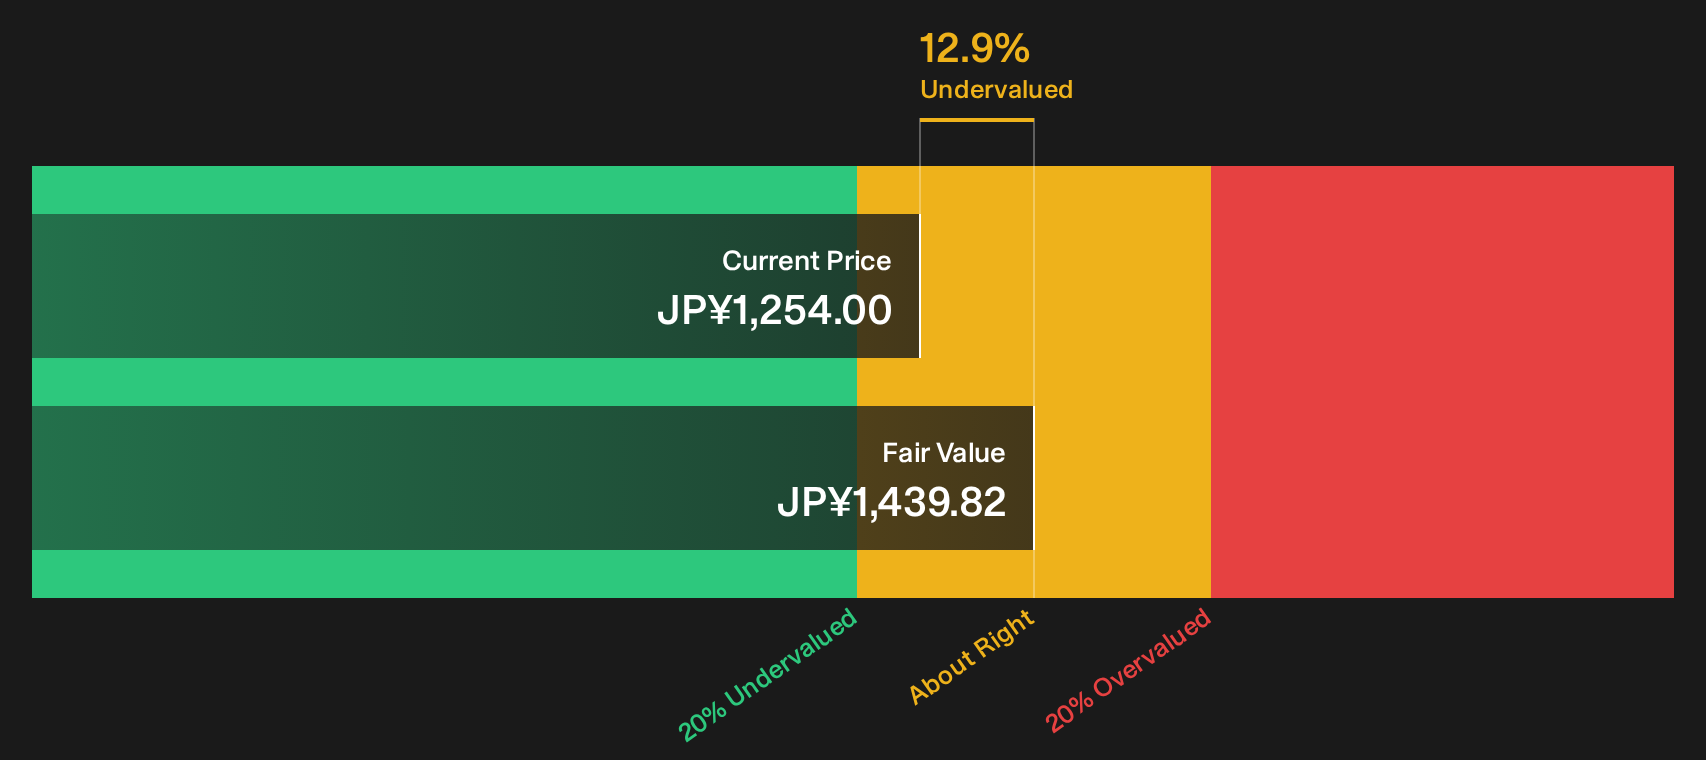
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sanrio Company for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 15 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on valuation and sentiment do not need to leave you on the fence. Act while the data is fresh and pressure test Sanrio Company against peers using our breakdown of 4 key rewards and 1 important warning sign
Looking for more Sanrio Company style investment ideas?
Do not stop with one stock. Use the Simply Wall St screener to surface fresh ideas that match your risk comfort, income needs, and return goals.
- Target potential mispricing by scanning a curated set of 15 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect their financial profile.
- Strengthen portfolio resilience by focusing on a list of solid balance sheet and fundamentals (22 results) so you can anchor your holdings in companies with sturdier financial footing.
- Reduce stress around big drawdowns by searching through a 24 resilient stocks with low risk scores that filters for steadier businesses with lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com