


EN
How Strong Earnings At Stock Yards Bancorp (SYBT) Has Changed Its Investment Story
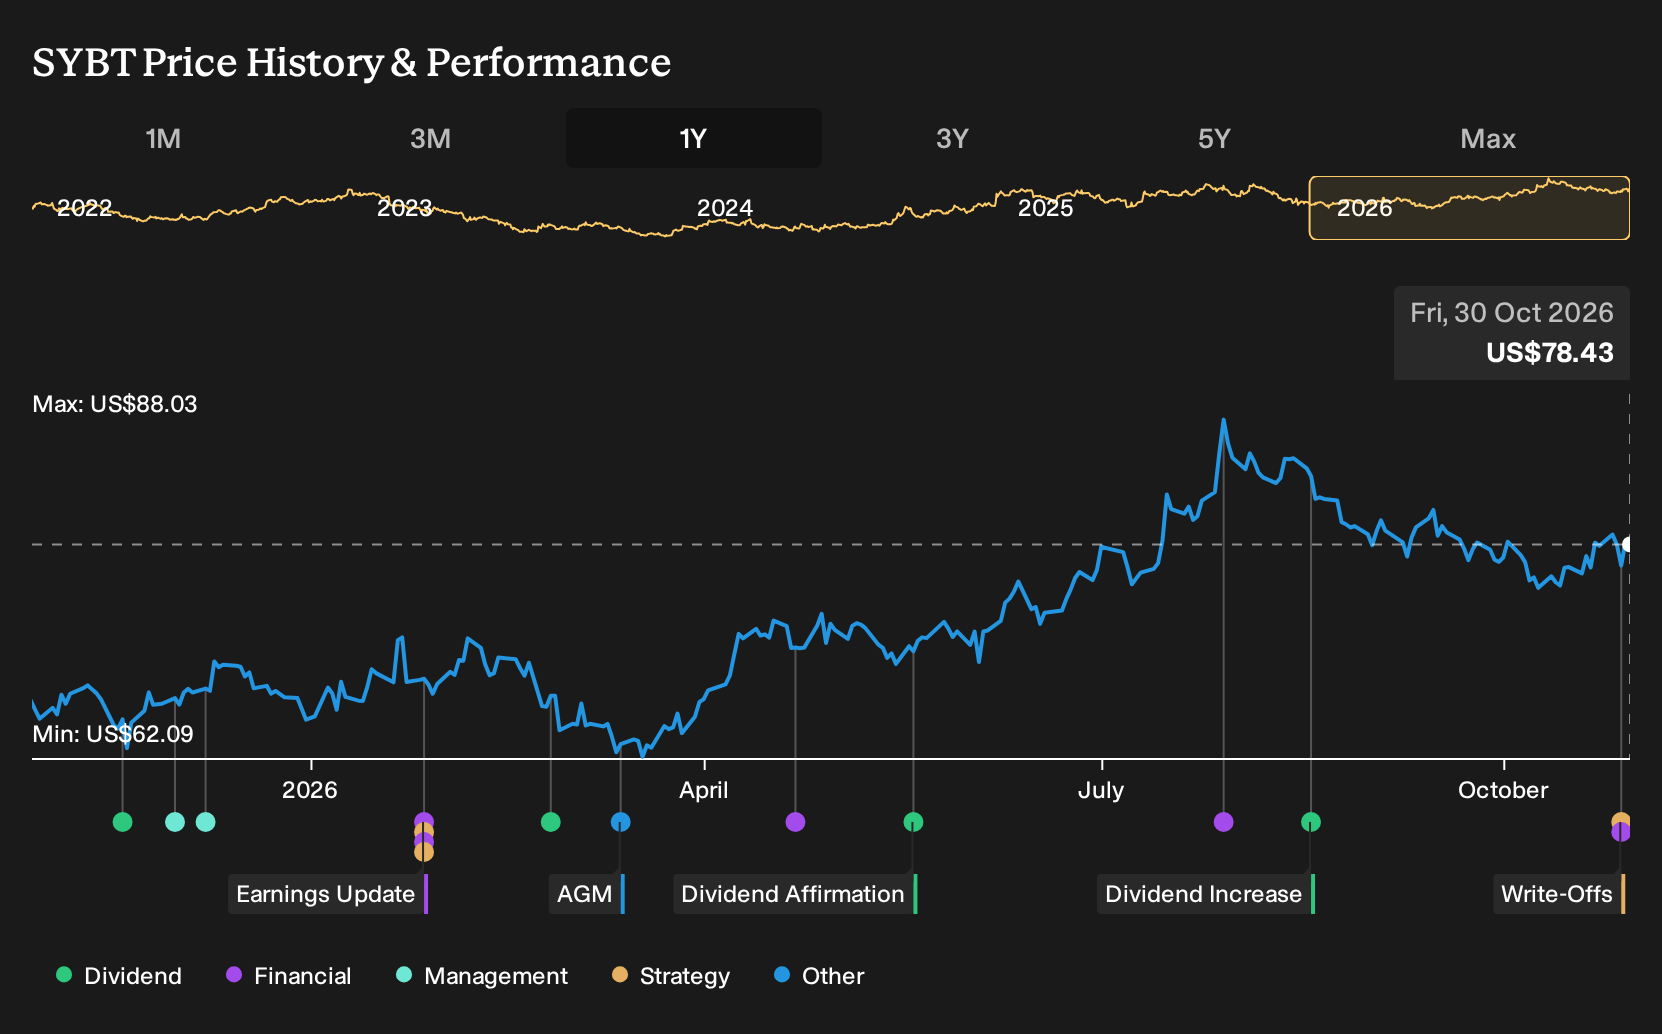
- Stock Yards Bancorp reported third quarter 2026 net income of US$43.51 million and net interest income of US$92.6 million, with basic earnings per share from continuing operations of US$1.41, all higher than the prior year period.
- Behind those headline figures, Stock Yards Bancorp also recorded a sharp rise in net charge offs to US$3.95 million, which puts credit quality trends under a brighter spotlight even as analysts raise earnings estimates.
- Next, the focus will be on how Stock Yards Bancorp's stronger earnings per share profile might influence its broader investment narrative.
What Is Stock Yards Bancorp's Investment Narrative?
To own Stock Yards Bancorp, you need to buy into a fairly simple idea. This is a regional bank that leans on steady net interest income, disciplined lending and a fee engine from wealth management and trust services, rather than big swings in trading or investment banking. The latest quarter fits that picture, with higher net interest income, a net interest margin near 3.9% and a loan book approaching US$8b, all while analysts lift earnings estimates.
The catch is that banking is about what you keep as much as what you earn. Net charge offs jumping to US$3.95 million pulls credit quality into focus and turns asset review and underwriting standards into short term catalysts. If management contains that issue while keeping loan growth and deposit costs in check, the existing earnings profile and dividend could stay appealing.
That said, the Stock Yards Bancorp story still runs into a less comfortable question once you look closely at ...
There's only one way to know the right time to buy, sell or hold Stock Yards Bancorp. Head to Simply Wall St's company report for the latest analysis of Stock Yards Bancorp's Fair Value.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Stock Yards Bancorp research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Stock Yards Bancorp. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Stock Yards Bancorp's overall financial health at a glance.
Looking For More Investment Ideas Beyond Stock Yards Bancorp?
If Stock Yards Bancorp has sharpened your interest in regional banks and income opportunities, it can be useful to widen the lens and compare it with other businesses that share similar qualities or offer different risk and return profiles. The Simply Wall St Screener lets you scan the market by fundamentals, so you can build a watchlist that actually fits your goals rather than relying on headlines or passing commentary.
- If capital preservation is high on your list, start with companies that pair steady balance sheets with measured risk profiles by reviewing the 30 resilient stocks with low risk scores through the screener.
- If income is a priority, look for businesses that combine higher yields with resilient cash generation by checking out the 5 dividend fortresses that have already passed a fundamentals filter.
- If you want to go hunting for new ideas, cast a wider net across lesser known but financially robust businesses by scanning the 18 high quality undiscovered gems inside the screener tool.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com