


EN
Is Russell Index Removal Altering The Investment Case For CBIZ Stock (CBZ)?
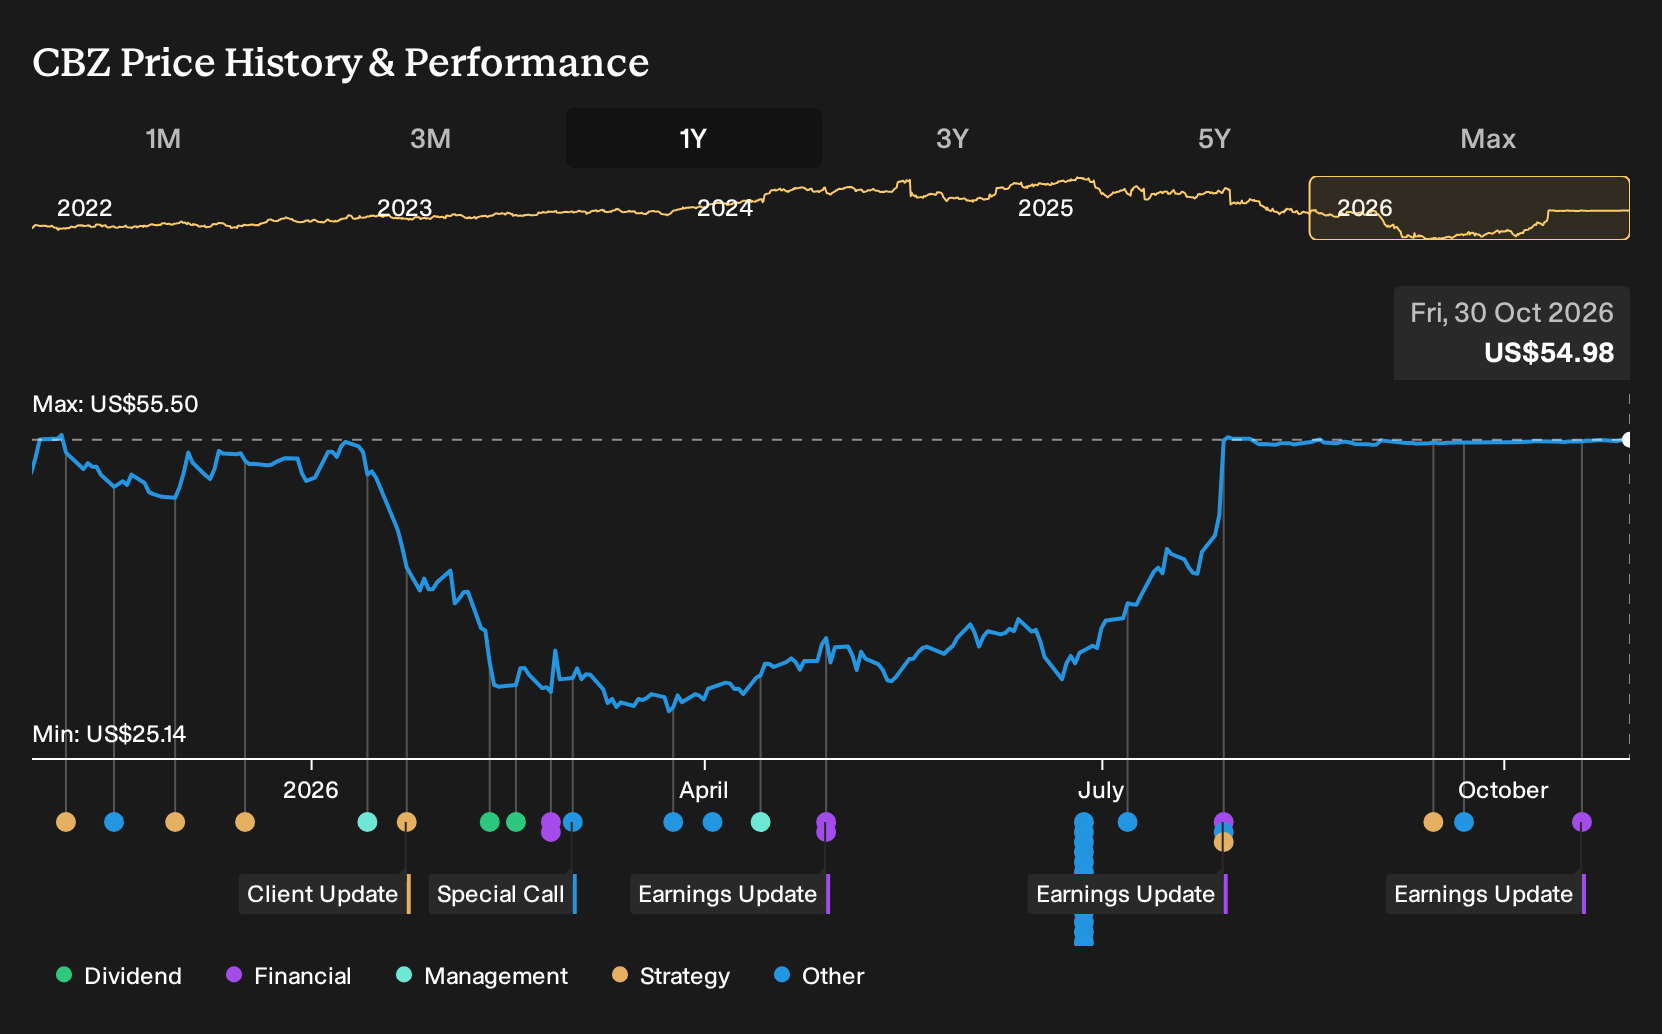
- CBIZ, Inc. was removed in October 2026 from a wide range of Russell indexes, including the Russell 2000, 2500, and 3000 families and related style and factor benchmarks that many index and quantitative funds use as allocation guides.
- The exits mean some index tracking capital tied to those Russell products no longer needs to hold CBIZ. This can matter for liquidity, ownership mix, and how easily the company can convert its recent earnings performance into steady market interest.
- We will now look at how CBIZ's investment narrative could be affected by its broad removal from the Russell index family.
Scan how CBIZ's index removal compares to other potential opportunities by checking companies that pass our 29 high quality undervalued stocks.
CBIZ Investment Narrative Recap
To own CBIZ, you basically need to believe the larger services platform, including Marcum, AI workflows and offshore delivery, can keep turning a mostly recurring client base into consistent earnings, even when project work is choppy. The broad Russell removals mainly affect how some funds trade the stock rather than how clients buy tax, advisory or benefits work. For the near term, the key positive swing factor is continued execution on efficiency and integration programs. The live operational risk is pricing pressure and volatility in nonrecurring Benefits & Insurance work.
For now, the index exits look more mechanical than fundamental. They can change who holds CBIZ shares, not how many clients need accounting, benefits and advisory services next quarter. The bigger business watchpoints stay the same. Can management keep embedding AI driven productivity, lifting offshore delivery and holding producer teams together while still managing debt that is not well covered by operating cash flow?
The clearest operational reference point around this index move is the third quarter 2026 earnings print. CBIZ reported US$702.24 million of quarterly sales, up from US$693.82 million a year before, and net income of US$47.24 million compared with US$30.15 million. Diluted EPS from continuing operations was US$0.79 versus US$0.48. Those numbers suggest the business entered the index removal with solid reported profitability and higher margins than last year.
That matters because the current catalyst story is about execution on efficiency and scale, not about index membership. Earnings for the first nine months of 2026 were US$218.63 million on sales of US$2,233.03 million, ahead of the prior year’s US$194.86 million on US$2,215.33 million of revenue. Investors weighing the Russell deletions against this operational backdrop are judging whether CBIZ can keep translating its enlarged platform, AI rollouts and global delivery plans into durable earnings while keeping an eye on leverage and pricing risk.
CBIZ Index Exit Against Analyst Expectations
CBIZ's narrative projects US$3.1b revenue and US$293.9 million earnings by 2029. This assumes 4.3% yearly revenue growth and an earnings increase of about US$171.8 million from US$122.1 million today.
Uncover why CBIZ's fair value is essentially aligned with its current price.
Exploring Other Perspectives
Some bullish analysts focus on CBIZ's earnings power rather than the index exits. You see a more optimistic script that leans on AI, offshore delivery and advisory mix, with forecasts before this news for revenue of about US$3.2b and earnings near US$298.8 million by 2029. You can compare these upbeat views with more cautious scenarios and decide which assumptions feel realistic.
Explore another CBIZ fair value estimate, including one that suggests potential upside of as much as 266% from the current price!
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your CBIZ research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CBIZ. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CBIZ's overall financial health at a glance.
Looking for more investment ideas beyond CBIZ?
If CBIZ has sharpened your thinking about earnings quality, index effects and balance sheet risk, it can be useful to put that side by side with a wider watchlist built from clear, rule based filters.
- For investors who care most about financial resilience, start with companies that pass our list of solid balance sheet and fundamentals (25 results) and compare how their funding profiles stack up against CBIZ.
- If capital preservation is your first filter and you prefer steadier business profiles, review our 30 resilient stocks with low risk scores to see which stocks score well on that front.
- When you want something less crowded that still has strong fundamentals, broaden your search using our 18 high quality undiscovered gems and see which businesses deserve a closer look next.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com