


EN
Diamondback Energy (FANG) Could Be 11% Undervalued As Analyst Optimism Builds
Recent analyst reports on Diamondback Energy (FANG) have become more optimistic, citing higher earnings estimates that are tied to expectations for stronger oil, natural gas, and liquids revenue, increased production volumes, and firmer pricing.
Diamondback Energy shares have climbed to US$212.08, with a 30-day share price return of 15.38% and a year to date share price gain of 39.21%. The 1-year total shareholder return of 51.68% points to strong momentum building behind the recent optimism.
Scan for other energy names showing similar earnings momentum and analyst upgrades using our curated list of 29 high quality undervalued stocks.
After a near 40% move this year and rising optimism on earnings, the question around Diamondback Energy shifts. Does the current price still offer upside that justifies the risk buyers take from here?
Most Popular Narrative: 11% Undervalued
At a last close of $212.08 versus a narrative fair value estimate of $239.45, Diamondback Energy screens as modestly undervalued, which is why so much attention is landing on what has to go right in its cash flow story.
The main thing that has to go right is that Diamondback Energy continues to translate lower drilling and operating costs, successful EOR pilots and improved gas marketing into durable free cash flow while managing risks from insider selling and a more neutral analyst stance.
The current valuation implies that Diamondback Energy is treated more like a peer level, defensive cash generator rather than a premium growth and capital efficiency story. This underpins the view that the shares are undervalued and that the risk or reward is skewed to the upside.
See why 79 investors see Diamondback Energy as 11% undervalued.
Result: Fair Value of $239.45 (UNDERVALUED)
Still, the narrative around Diamondback Energy could shift quickly if large insider or major shareholder sales occur at the same time as higher operating costs in the Permian.
Find out about the key risks to this Diamondback Energy narrative.
Another View: Valuation Through The P/E Lens
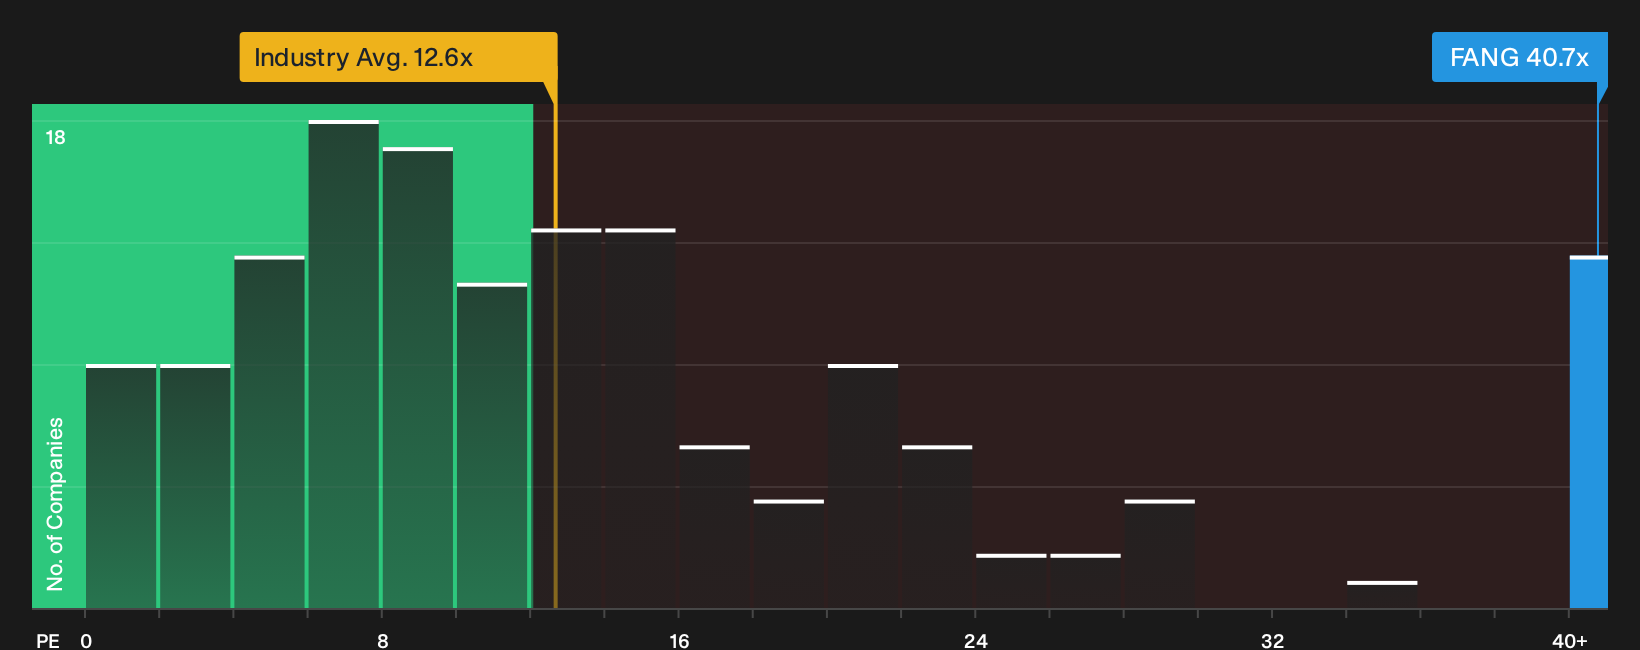
On the narrative fair value framework, Diamondback Energy appears 11% undervalued. On a plain P/E yardstick, the picture looks very different. FANG trades on 40.7x earnings compared with 12.6x for the US oil and gas group and a fair ratio estimate of 24.2x.
That gap points to a rich valuation on current earnings that already bakes in a lot of good news, even if long range cash flow models point to upside. The key question for you is whether the story justifies paying such a premium multiple today.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Strong opinions are building around Diamondback Energy, which is exactly when you benefit most from checking the data yourself and moving quickly to shape your own stance. To weigh both sides in one place, start with the 2 key rewards and 4 important warning signs.
Ready for more investment ideas beyond Diamondback Energy?
If Diamondback Energy has sharpened your thinking, do not stop here. Use the Simply Wall St Screener to spot other opportunities that fit your playbook.
- Target reliable income streams by reviewing companies in the 5 dividend fortresses that might help anchor your portfolio with cash returns.
- Hunt for pricing gaps by focusing on the 18 high quality undiscovered gems that the broader market may not be paying attention to yet.
- Dial down potential volatility and stress test your holdings against the 30 resilient stocks with low risk scores so you are not caught off guard later.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com