


EN
Sempra (SRE) Earnings Setup Puts Its Capital Plan And Valuation In Focus
Sempra (SRE) heads into its November 5 earnings release with expectations for higher year-over-year profit and revenue, and an Earnings ESP of +2.25% pointing to a possible positive surprise.
Recent trading has tilted in Sempra’s favor, with a 1-month share price return of 10.39% and a 7-day share price gain of 2.38% lifting the stock to $86.06. This comes even though the year-to-date share price return is down 4.07% and the 1-year total shareholder return is down 3.58%, while the 3-year and 5-year total shareholder returns of 30.68% and 58.07% suggest longer term holders have still seen solid value creation.
Spot opportunities around Sempra's earnings setup by scanning a curated 39 power grid technology and infrastructure stocks that could also be primed for their next move.Sempra has recently rallied, yet it still trades below the average analyst target and an intrinsic value estimate that is described as much lower. Is the recent move a reset, or is the market still underpricing it?
Most Popular Narrative: 13% Undervalued
Sempra's most followed narrative pegs fair value at $99.03, above the recent $86.06 close. This puts real weight behind the current earnings setup and the capital plan investors are watching.
The US$47.5b five year base capital plan at Oncor, along with US$10b of incremental identified projects tied to ERCOT endorsed upgrades, reliability work and future resiliency filings, keeps the earlier thesis about sustained capital deployment into transmission and distribution assets in place as a driver of long term earnings growth.
See why 25 investors see Sempra as 13% undervalued.
Result: Fair Value of $99.03 (UNDERVALUED)
Still, the Sempra story can break if regulators tighten allowed returns in California or Texas, or if LNG construction setbacks drag on earnings longer than expected.
Find out about the key risks to this Sempra narrative.
Another View: Multiples Paint A Tougher Picture For Sempra
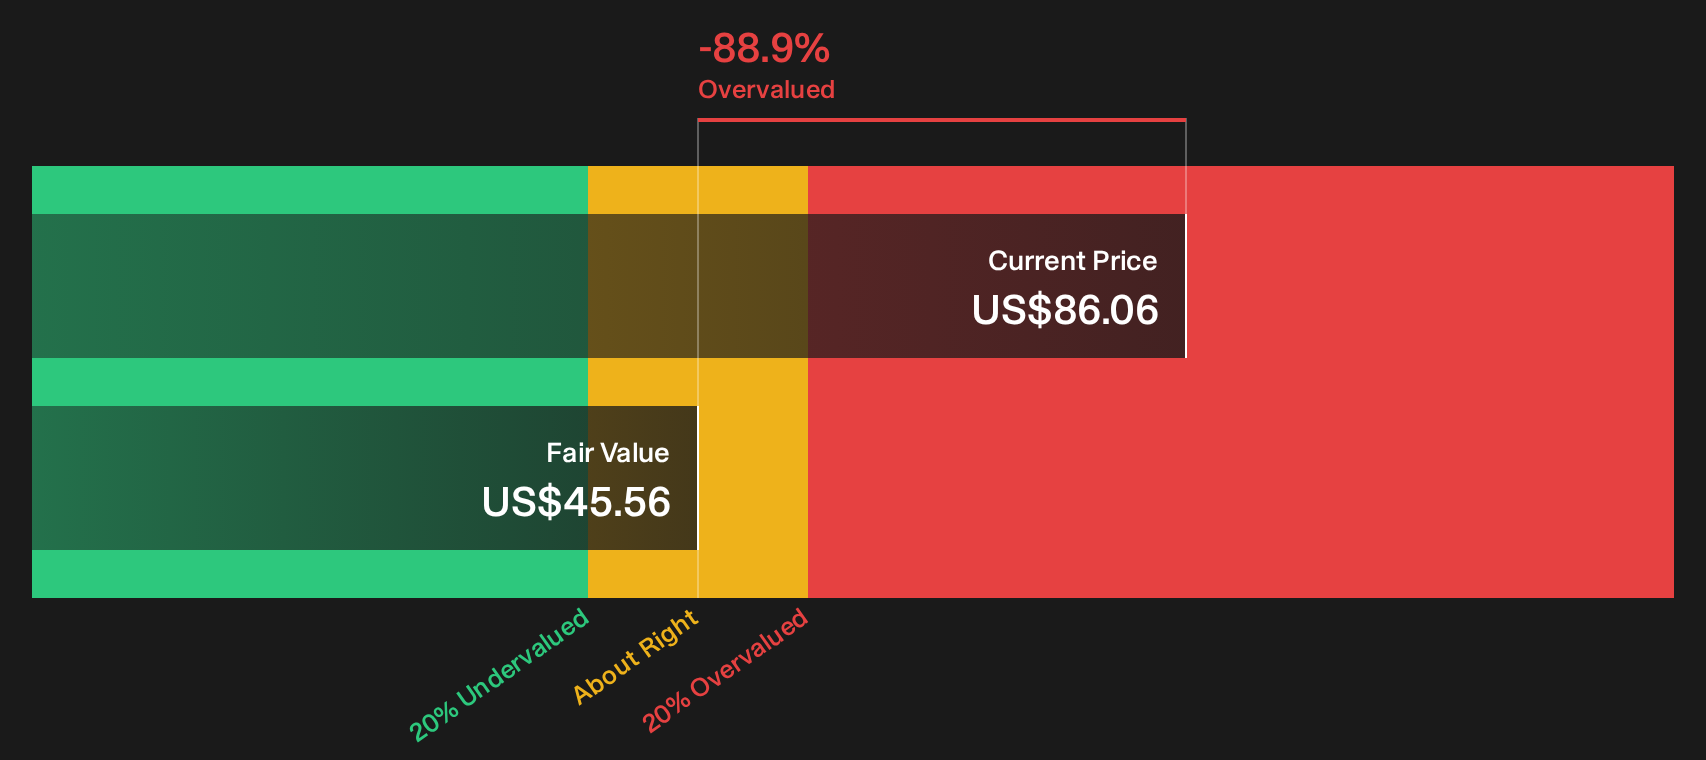
The SWS DCF model points to Sempra trading above an estimated future cash flow value of $45.56 at the current $86.06 price, which screens as overvalued on that lens. That pulls against the $99.03 fair value from the narrative work and leaves you asking which set of assumptions you trust more.
Before leaning on either signal too hard, it helps to see how this model is built and what is driving the gap between price and cash flow value. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Sempra’s setup appears finely balanced between optimism and caution, so consider reviewing the information while it is current and pressure test the story yourself using 1 key reward and 2 important warning signs.
Looking For More Ideas Beyond Sempra?
If Sempra has sharpened your focus ahead of earnings, do not stop here. Broader opportunities often emerge when you compare different business models side by side.
- Target resilient cash generators by scanning companies on the 29 high quality undervalued stocks that combine quality fundamentals with prices below their estimated worth.
- Strengthen your income stream by reviewing the 5 dividend fortresses and spotting payout profiles that line up with your risk tolerance.
- Limit unpleasant surprises by filtering for sturdier balance sheets using the 30 resilient stocks with low risk scores before the next bout of volatility hits.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com