


EN
Bharat Forge Climbed While It Swung To A Loss
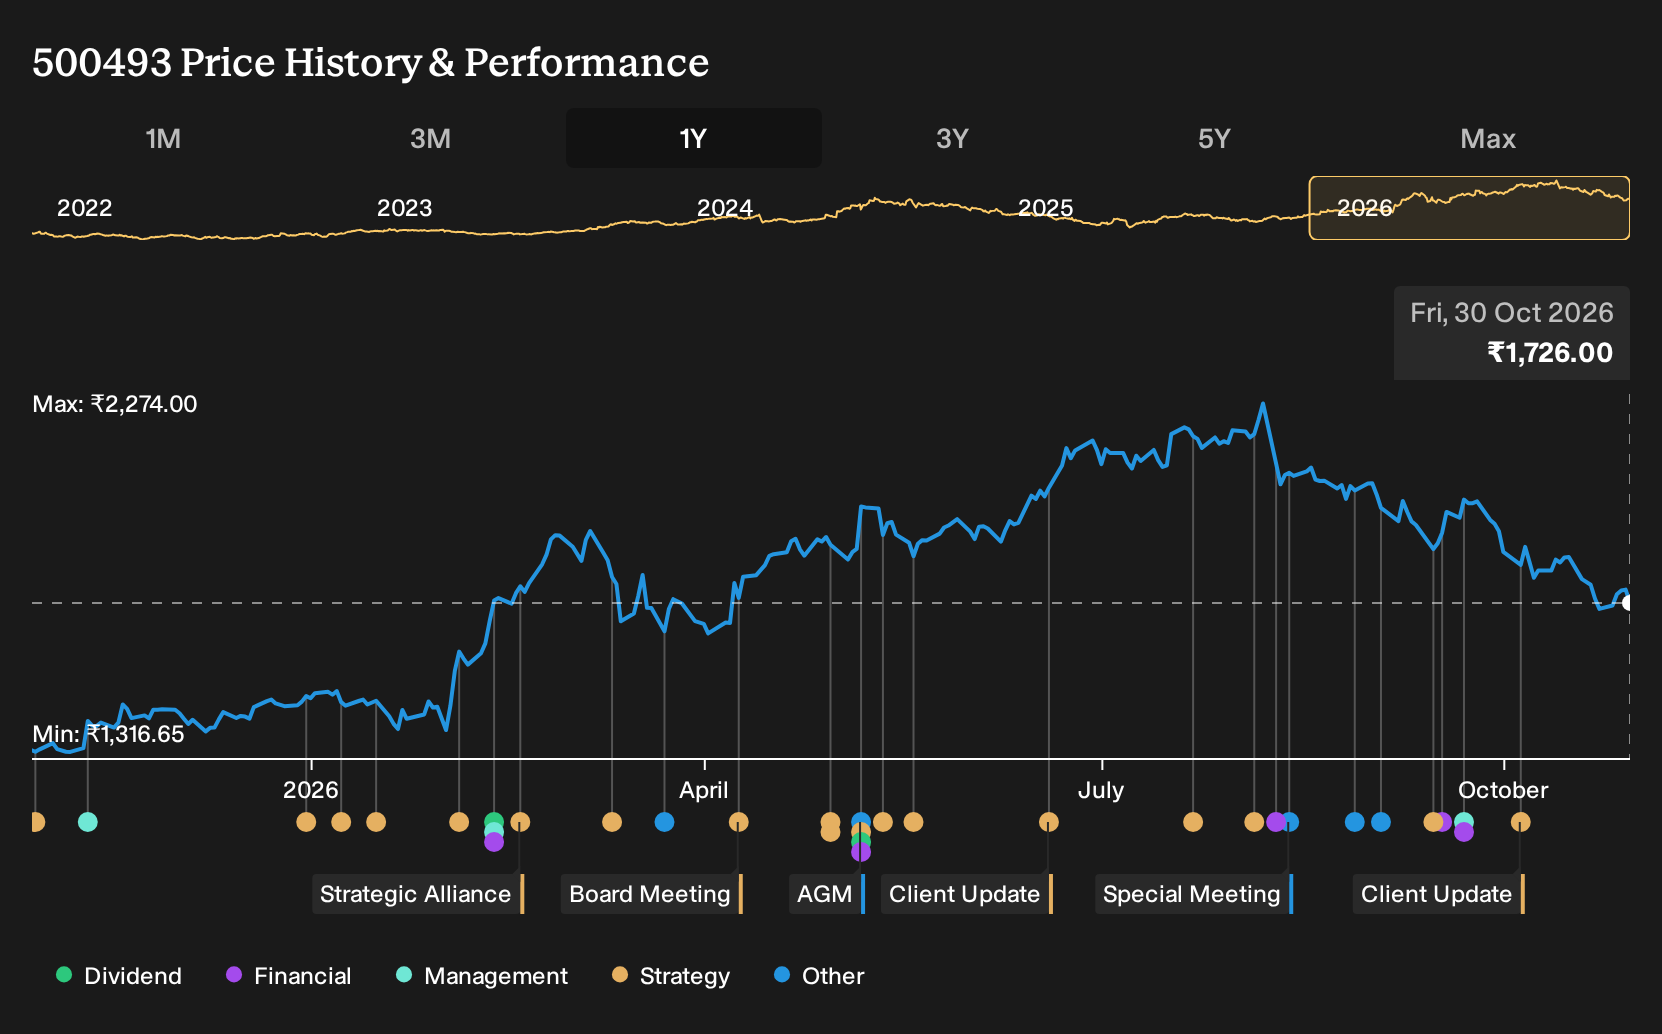
If you only glanced at Bharat Forge headlines, the eye might have gone straight to its newer server and electronics push with Compal Electronics, one concrete step into AI infrastructure and higher-value manufacturing. Holding Bharat Forge over the past year would have returned 30.9%, including dividends. If you had been weighing a purchase before that move, what did you need to believe about this shift beyond legacy forgings, and its resilience after a quarter where profit slipped into a loss?
Bharat Forge has already moved. See which of 199 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Bharat Forge
The shares cost ₹1,317 at the start of the period, so any thesis on Bharat Forge had to clear a fairly demanding bar.
On the bullish side, the optimistic narrative pointed to a fair value of ₹1,800, essentially the price implied if strong assumptions played out, backed by 14.5% annual revenue growth and margins rising from 6.8% to 12.3% by 2028.
The more cautious view saw fair value at ₹1,164, built on 11.4% revenue growth and profit margins reaching 11.0%, while flagging tariff risks in the United States as a key threat to earnings stability.
What The Results Changed For Bharat Forge
The clearest fresh fact for Bharat Forge holders was the Q1 2027 print. Reported revenue reached ₹46,399.41m, up from ₹39,087.49m a year earlier, which leaned toward the optimistic growth case. Profit told a different story. Net income moved from ₹2,836.83m to a loss of ₹897.27m and net margin fell from 7.3% to 1.9% in the red, so profitability upside remained unproven. Overall, the evidence cut both ways.
The real lesson is where you anchor your expectations. The bullish and cautious cases both hinged on margin expansion. For any other stock with an ambitious story, check whether net margin is actually moving toward the level in the thesis before treating strong revenue alone as confirmation.
What Bharat Forge's Price Now Asks You To Believe
Bharat Forge trades at ₹1,726 today, and the selected Narrative’s Fair Value sits below that level, so its authors see the market already baking in a lot of execution success.
The Narrative’s core question is whether large India capex, defense and aerospace ramps, and export restructuring will turn into cash and margins fast enough. Anyone paying today’s price is effectively assuming those projects hit plan. How does the highlighted risk around cash conversion and overseas drag affect that bet?
"Key Takeaways: Bearish analysts expect Bharat Forge to keep facing pressure on its traditional auto and export businesses as electric vehicles, new materials and weak overseas margins weigh on long term revenue quality. The main factor that has to go right is successful execution of the large India capex and the build out of defense, aerospace and high precision components, so that these newer verticals can offset overseas drag and cost inflation."
Not everyone reads the same price the same way. → See the lower figure this Narrative lands on, and how it gets there
Looking Beyond Bharat Forge
Once you think through Bharat Forge, your eye might shift sideways. Defence-heavy manufacturing has another layer that rarely grabs headlines.
Big military and aerospace buyers do not only need metal. They also want complex electronics, secure systems and software that can be updated for decades.
One supplier focuses on exactly that, tying together radars, secure communications, avionics and cyber protection for critical operators.
Its customers still care about hardware output, yet decisions increasingly hinge on digital security, connectivity and mission software.
If that balance keeps tilting toward systems and data, the opportunity looks very different to Bharat Forge's forging-heavy mix.
The case is written up, with the assumptions it depends on. → Discover the robotics company one Narrative values 24% above its price
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com