


EN
CSX (CSX) Following Rail Outage Recovery Looks Near Fair Value
CSX (CSX) is in focus after a technology outage disrupted freight operations and data exchange with other major railroads. Management now reports that critical systems have been restored, no cyberattack occurred, and interchange volumes have returned to or exceeded prior levels.
Recent trading suggests investors are looking past the outage and focusing on CSX's broader trajectory, with a 30 day share price return of 11.78% and a year to date share price return of 43.34%. The 5 year total shareholder return of 57.12% points to momentum that has built over time.
Scan how CSX compares to other rail and freight operators, and find fresh momentum in freight recovery across our hand picked 30 resilient stocks with low risk scores.
The outage is fading from view, and CSX now trades near analyst targets while sitting well above some intrinsic value estimates. Is the recent 43.34% year to date surge already pricing in fair value, or not yet?
Most Popular Narrative: 2% Undervalued
CSX closed at $51.99, while the most followed narrative puts fair value around $53.10. The market is only slightly below that mark yet still treating future cash generation and margin potential with some caution.
The industrial development pipeline of roughly 600 active projects, with about 100 expected to enter service in 2026 and provide significantly more volume at full ramp than the prior year cohort, is poised to add new carloads that support merchandise and bulk revenue and help operating leverage.
See why 25 investors see CSX as 2% undervalued.
Result: Fair Value of $53.10 (UNDERVALUED)
Still, the CSX story can break if crew capacity once again lags volume, or if regulatory pressure forces higher operating costs and softer profitability.
Find out about the key risks to this CSX narrative.
Another View: CSX Through The P/E Lens
The SWS DCF model points to a future cash flow value of $40.80 per share, which sits well below CSX's recent $51.99 price and frames the stock as overvalued on that basis. Yet the P/E ratio tells a different story and raises a fresh question for investors.
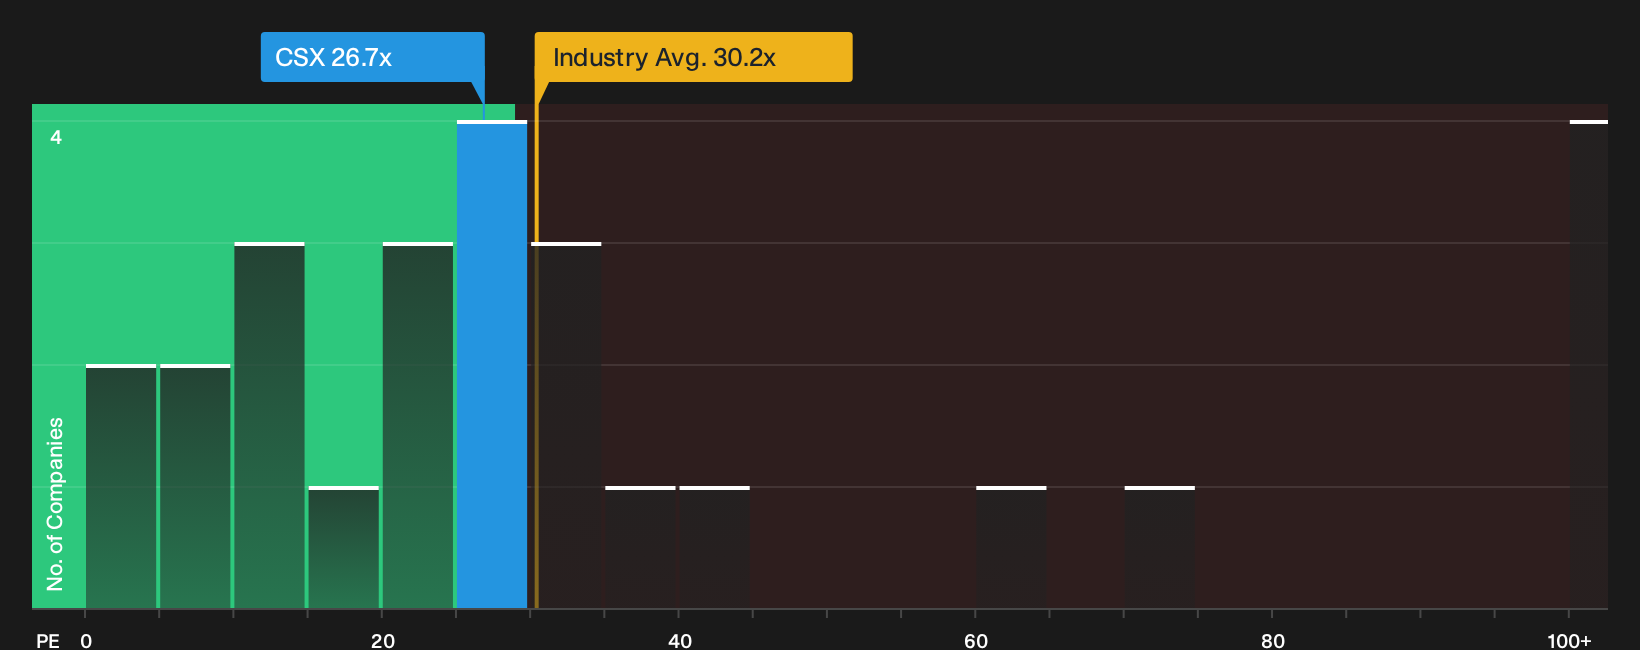
On earnings multiples, CSX trades on 26.7x, which is cheaper than the wider US Transportation group at 30.2x but richer than the peer set at 21.8x and above a fair ratio of 20.2x. That mix of relative value and fair ratio risk leaves a practical puzzle: Is the premium a sign of quality or a margin of error waiting to close?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on CSX valuation and risk. Consider the situation while the outage story is fresh in mind and weigh both sides through 3 key rewards and 1 important warning sign.
Looking for more ideas beyond CSX?
If CSX has your attention, do not stop here. The best opportunities often come from comparing fresh ideas across quality, yield, and value in one focused session.
- Target resilient balance sheets by scanning companies in the list of solid balance sheet and fundamentals (25 results) that may handle shocks better than most.
- Hunt for potential mispricing across the market with the 29 high quality undervalued stocks before others re-rate those opportunities.
- Strengthen your income stream by reviewing the 5 dividend fortresses that could complement or offset any future CSX returns.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com