


EN
Should Earnings Beat Require Action From Upbound Group (UPBD) Investors?
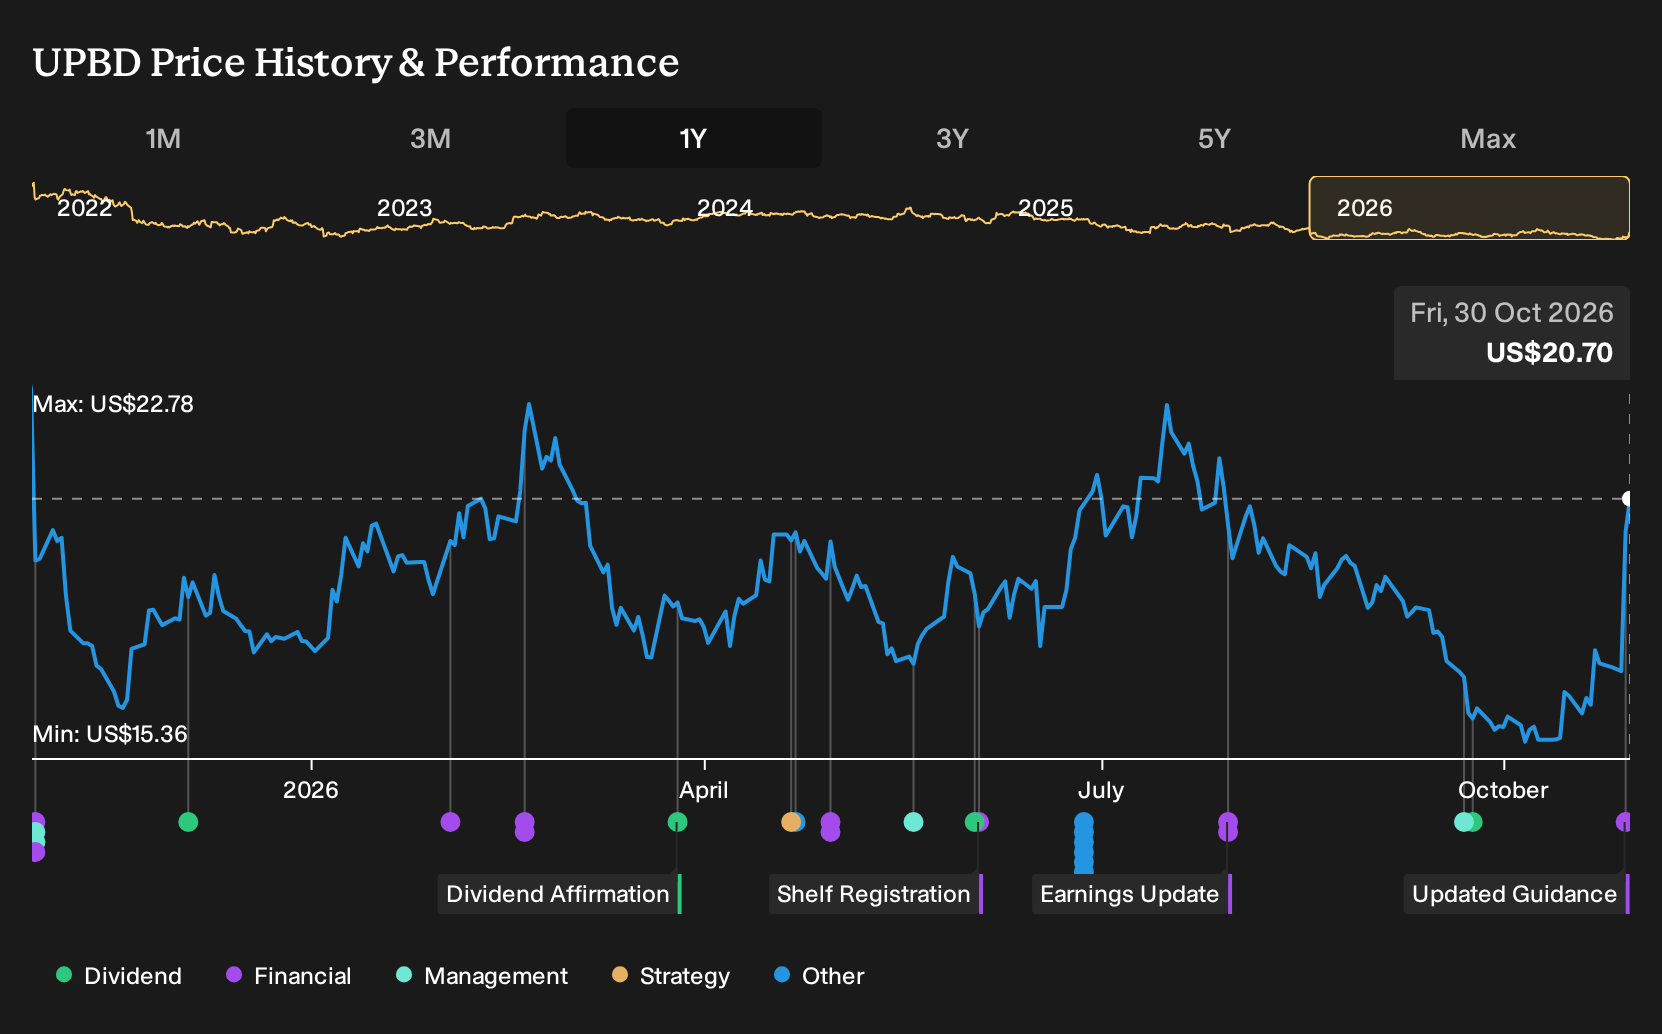
- Upbound Group reported third quarter 2026 revenue of US$1.15b and net income of US$34.27 million, with non GAAP EPS of US$1.01 exceeding prior guidance and consensus expectations.
- The business coupled this earnings beat with a Boost Mobile lease to own partnership across roughly 5,000 stores and a plan to repurchase up to US$50 million of stock, indicating tighter execution and active capital deployment.
- We will now look at how Upbound Group's investment narrative is affected by this earnings beat and the Boost Mobile agreement.
Upbound Group Investment Narrative Recap
To own Upbound Group, you need to believe the business can keep turning tight credit screening, tech driven underwriting and a multi brand model into steadier earnings and cash generation, even while non prime customers remain stretched. The latest quarter supports that thesis in the near term, with non GAAP EPS and adjusted EBITDA ahead of guidance despite softer demand.
The short term swing factor is execution at Acima and Rent A Center, especially credit outcomes, fraud control and lease volumes. The biggest risk is that consumer stress or renewed operational issues at Acima, including regulatory or legal setbacks, undercut margins and free cash flow just as management leans into buybacks and new partnerships.
The most relevant announcement for this earnings beat is management’s plan to repurchase up to US$50 million of common stock under the existing program. That move depends on the company’s ability to keep generating solid free cash flow and to manage its high debt load without crowding out investment in underwriting tools and growth initiatives.
For you as an investor, the buyback ties directly into the current catalysts. If Upbound Group continues to push digital underwriting, and expand merchant relationships such as Boost Mobile and Amazon, and keep Acima’s loss performance in check, then share repurchases can concentrate any future earnings power. If credit costs flare or the CFPB lawsuit outcome is unfavorable instead, that same capital return could look early against the risk profile.
Upbound Group's current analyst framework points to revenues of US$5.2b and earnings of US$311.3 million by 2029. This outlook is built on a projected 3.1% yearly revenue growth rate and an increase in profit from US$90.3 million today, which would mean earnings rising by about US$221 million over the forecast period.
Uncover why Upbound Group's fair value indicates a 36% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternative lens on Upbound Group focuses less on partnerships and more on margin strain from tech and AI spending. The lowest analysts already expected 3.4% yearly revenue growth to about US$5.2b and earnings of US$361.5 million by 2029. Those projections came before this quarter’s beat, so their story may shift once they refresh the numbers.
Explore 2 other Upbound Group fair value estimates, including one that suggests it could be worth just $27.50!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Upbound Group research is our analysis highlighting 3 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Upbound Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Upbound Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Upbound Group?
Once you have a view on Upbound Group, it can help to compare it with other businesses that match the kind of risk, balance sheet strength or income profile you want in your portfolio. The Simply Wall St Screener is built for exactly that sort of targeted search, so you can line up stocks against your preferred filters in minutes rather than hours.
- If you want potential mispricing combined with quality fundamentals, start by scanning a focused set of 29 high quality undervalued stocks that may offer a more attractive entry point than headline names.
- For investors who care most about resilient finances, narrow your search to companies in the list of solid balance sheet and fundamentals (25 results) and compare their strength against Upbound Group's profile.
- If capital preservation matters as much as upside, aim at the 30 resilient stocks with low risk scores and see which stocks better match your comfort level on volatility and business risk.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com