


EN
Cardinal Health (CAH) Lifts Earnings Outlook, Is The Stock Still Trading At A Discount?
Cardinal Health (CAH) just posted quarterly results that lifted operating income by more than a third and pushed adjusted earnings per share up 37%, supported by 14.8% revenue growth in its Pharmaceutical and Specialty Solutions segment.
The earnings beat has landed on a stock that is already in motion. Cardinal Health shares are up 12.6% over the past month and 21.8% year to date, while the 1 year total shareholder return of 32.5% and very large 5 year total shareholder return suggest momentum has been building for some time.
Scan for other healthcare distributors showing similar earnings momentum and pricing setups to Cardinal Health by reviewing the hand-picked list of solid balance sheet and fundamentals (25 results) in the same sector.
Cardinal Health now trades close to a fresh high, yet it still sits at a discount to both analyst targets and some fair value estimates. Is that a market warning signal, or an opportunity that caution does not fully explain?
Most Popular Narrative: 8% Undervalued
Cardinal Health closed at $250.48, while the most followed narrative anchors fair value around $270.94, implying a gap that hinges on how investors view its shift toward higher margin services and a repaired medical products base.
The expansion of specialty pharma distribution, multi specialty MSO platforms in areas like oncology, urology and gastroenterology, and a rapidly scaling Biopharma Solutions business that is ahead of its prior growth plan points to a larger mix of higher value services that can influence segment profit and overall earnings.
Faster growth in higher margin service businesses such as Nuclear and Precision Health, OptiFreight logistics and at-Home Solutions, with revenue and profit guidance above prior long term targets, indicates a structural mix shift that can support operating margin and earnings growth.
See why 57 investors see Cardinal Health as 8% undervalued.
Result: Fair Value of $270.94 (UNDERVALUED)
Still, two issues could upset that 8% undervalued story for Cardinal Health: levothyroxine recall scrutiny and any renewed pressure on Global Medical Products and Distribution profitability.
Find out about the key risks to this Cardinal Health narrative.
Another View: What Cardinal Health's P/E Is Telling You
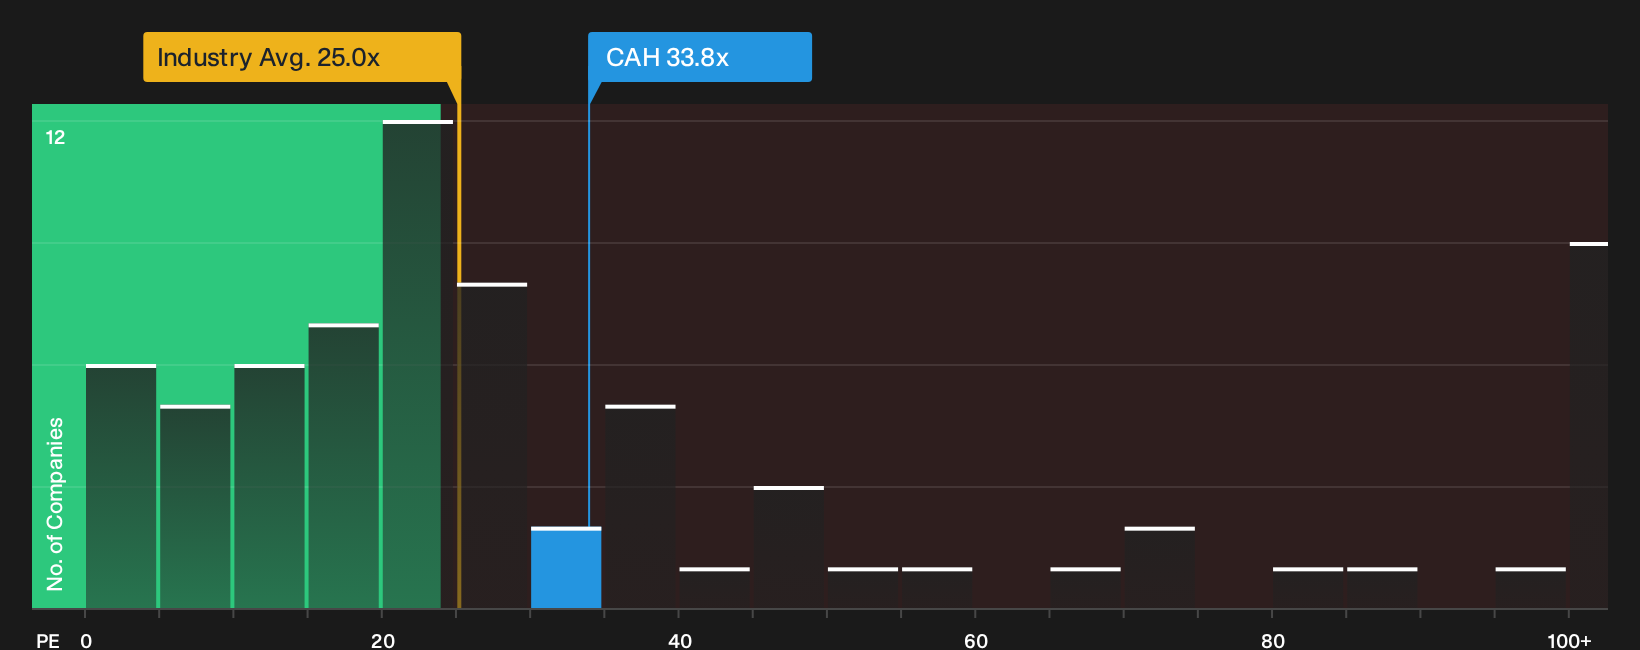
The story looks different when you swap fair value estimates for simple earnings multiples. Cardinal Health trades on a P/E of 33.8x, compared with 25x for the broader US Healthcare group and 27.9x for peers, while the fair ratio for this stock sits at 30.8x.
That spread suggests investors are already paying a premium for Cardinal Health versus the sector and even versus where the fair ratio says the market could eventually settle. The key question is whether the earnings mix shift and recall risks justify that richer tag or call for more caution.
To see how the earnings multiple stacks up against other signals, review the valuation breakdown in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Momentum stories like Cardinal Health can influence sentiment in both directions, so move quickly past the headlines, stress test the data, and weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Cardinal Health?
You have already done the hard work on Cardinal Health. Do not stop there when a wider set of opportunities could sharpen your entire portfolio.
- Target resilient compounding potential by scanning companies with dependable balance sheets and cash generation using the list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced quality by reviewing the 29 high quality undervalued stocks that could offer stronger fundamentals than their current market tags suggest.
- Build a steadier income stream by evaluating the 5 dividend fortresses that combine higher yields with a focus on durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com