


EN
Is Yue Yuen Industrial (Holdings) (SEHK:551) Still Below Fair Value As Profit Guidance Weakens?
Yue Yuen Industrial (Holdings) (SEHK:551) has warned that profit for the nine months to September 2026 will be 50% to 55% lower than a year earlier, citing weaker demand and higher costs.
That warning comes after a choppy few months for Yue Yuen Industrial (Holdings). The share price is HK$13.7, with a 30 day share price return of 8.73% but a year to date share price decline of 14.21%. The 3 year total shareholder return of 90.26% indicates that longer term investors are still sitting on strong gains, even as near term momentum appears fragile.
Contrast Yue Yuen Industrial (Holdings)' latest guidance with other manufacturers facing similar demand and cost pressures by scanning our hand picked list of list of solid balance sheet and fundamentals (203 results) for comparison.
After a sharp profit warning but a 3 year total return above 90%, Yue Yuen Industrial (Holdings) now sits at an awkward crossroads. Has most of the easy upside already played out? Or does valuation still leave meaningful headroom?
Preferred P/E of 9.9x: Is it justified?
Valuation on Yue Yuen Industrial (Holdings) hinges on a P/E of 9.9x at the HK$13.7 last close, which screens as expensive against both the Hong Kong Luxury sector and its closest peers.
The P/E ratio compares the share price with earnings per share. For a footwear manufacturer and retailer like Yue Yuen Industrial (Holdings), it effectively shows how much investors pay today for each unit of current profit, relative to other consumer companies exposed to similar demand swings and input costs.
Here the market is assigning a richer multiple than several benchmarks. The stock trades on 9.9x earnings, while the Hong Kong Luxury industry sits at 7.7x and the peer group average sits at 9.6x, and the estimated fair P/E from the SWS model is 9.3x. This indicates investors are paying a higher multiple relative to the sector and to the level suggested by the fair ratio model.
Explore the SWS fair ratio for Yue Yuen Industrial (Holdings).
Result: Price-to-Earnings of 9.9x (OVERVALUED)
Still, weak demand, higher costs and any further cut to Yue Yuen Industrial (Holdings)' profit outlook could quickly challenge the case for paying a premium P/E multiple.
Find out about the key risks to this Yue Yuen Industrial (Holdings) narrative.
Another view on Yue Yuen Industrial (Holdings)' value
The DCF output points in a very different direction. At HK$13.7, Yue Yuen Industrial (Holdings) is flagged as trading about 53.8% below an estimated future cash flow value of HK$29.68, which presents the current P/E premium as a possible pricing gap rather than a clear red flag. Could this mismatch be a signal or just model noise?
Look into how the SWS DCF model arrives at its fair value.
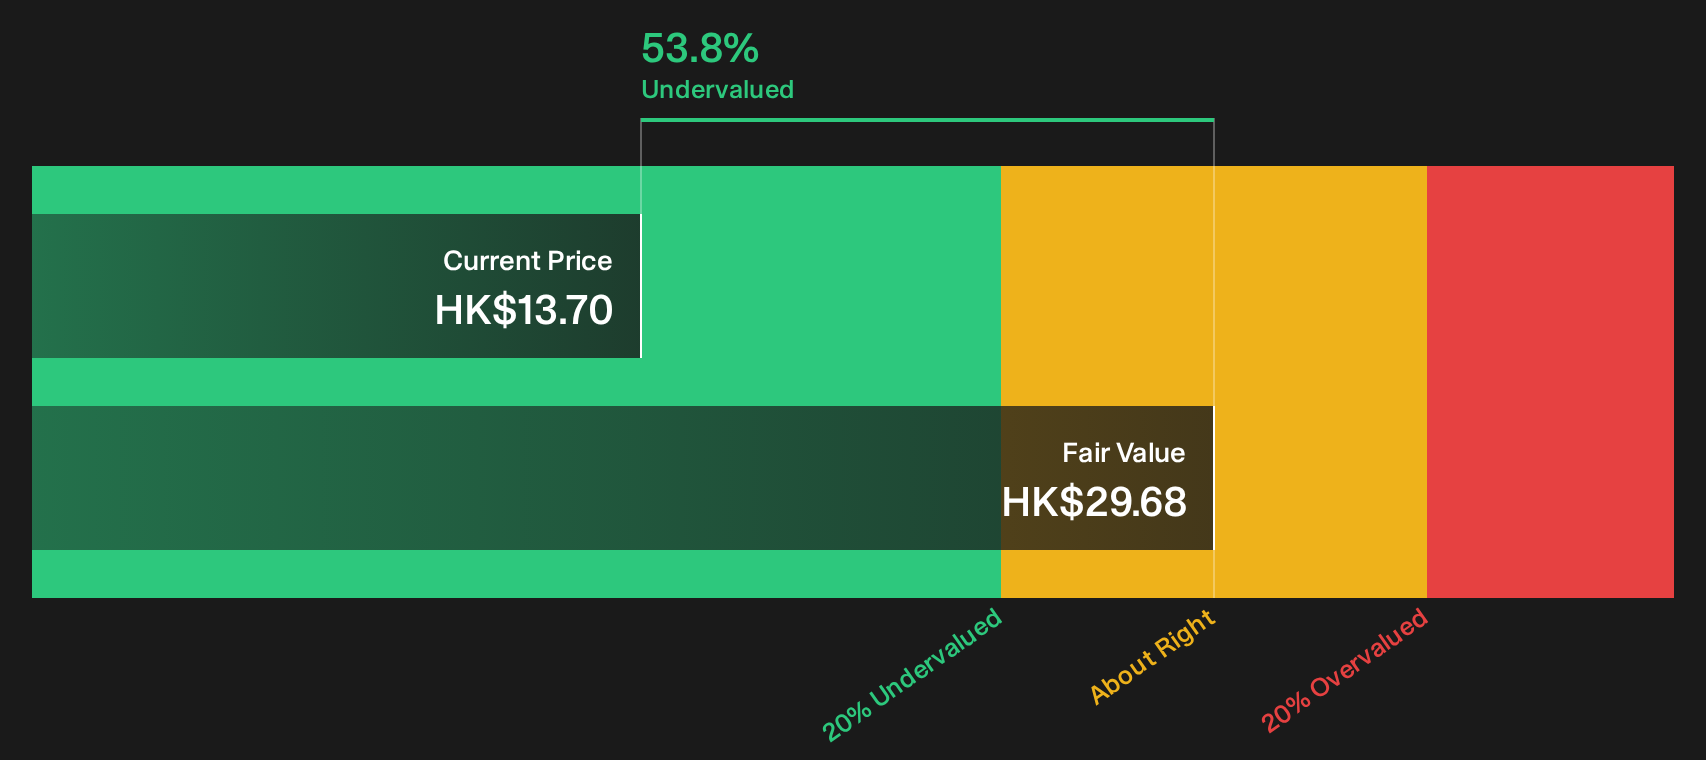
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Yue Yuen Industrial (Holdings) for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals often create the most interesting setups. Move quickly, examine the full risk and reward profile, and shape your own take with the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond Yue Yuen Industrial (Holdings)?
If Yue Yuen Industrial (Holdings) no longer feels like the only place to focus, you can broaden your watchlist and use data to identify additional opportunities.
- Target resilient balance sheets and stress test your downside risk with a curated list of solid balance sheet and fundamentals (203 results) that filters for financial strength first.
- Look for potential mispricing and compare Yue Yuen Industrial (Holdings) with a focused 199 high quality undervalued stocks that highlights businesses where fundamentals and price appear out of sync.
- Prioritise stability and income potential by scanning a hand picked 221 dividend fortresses that concentrates on companies offering higher yields supported by their financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com