


EN
Nucor (NUE) Earnings Strength Keeps Its Undervalued Narrative In Focus
What Nucor’s latest earnings signal for investors
Nucor (NUE) just paired strong third quarter results with fourth quarter guidance that points to earnings in line with, or modestly higher than, that recent performance.
Across both the income statement and cash returns to shareholders, the steel producer has put several fresh data points on the table that matter for anyone tracking Nucor stock.
Nucor’s latest guidance lands after a powerful run, with a year to date share price return of 61.67% and a 1 year total shareholder return of 84.66% that hints at investors re rating both its earnings power and capital returns.
The stock has cooled slightly in the last session with a 1 day share price return decline of 0.52%. However, the 7 day gain of 6.11% and 30 day share price return of 17.16% suggest momentum is still firmly pointed upward.
That strength comes on the heels of third quarter earnings, fresh fourth quarter guidance, ongoing share repurchases totaling roughly 1.63% of the share count, and a US$60m expansion of its Towers & Structures facility, which ties Nucor more tightly to long term power grid investment themes.
Scan beyond Nucor and track where similar earnings strength and capital returns may be building by reviewing our hand picked 29 high quality undervalued stocks in the materials and industrial value chain.
Nucor now trades at a discount to both intrinsic estimates and analyst targets after a rapid run up in the share price. Is that a mispriced earnings story, or is the market simply pricing in steel risk correctly?
Most Popular Narrative: 6% Undervalued
Nucor’s most followed valuation framework points to a fair value of $291.88 against a last close of $273.87. This signals a modest valuation gap that depends on how its new mills and downstream projects convert heavy past spending into ongoing earnings and cash flow.
Nucor's multi year capital program of roughly US$15b to US$20b, with several mills and downstream assets already EBITDA positive and capital expenditure guiding to about US$2.5b in 2026, is moving from the build phase toward cash generation, which can support higher earnings and free cash flow.
See why 105 investors see Nucor as 6% undervalued.
Result: Fair Value of $291.88 (UNDERVALUED)
Still, the story around Nucor can shift quickly if nonresidential and infrastructure demand softens or if large projects like the West Virginia mill stumble on execution.
Find out about the key risks to this Nucor narrative.
Another View: Nucor on traditional valuation measures
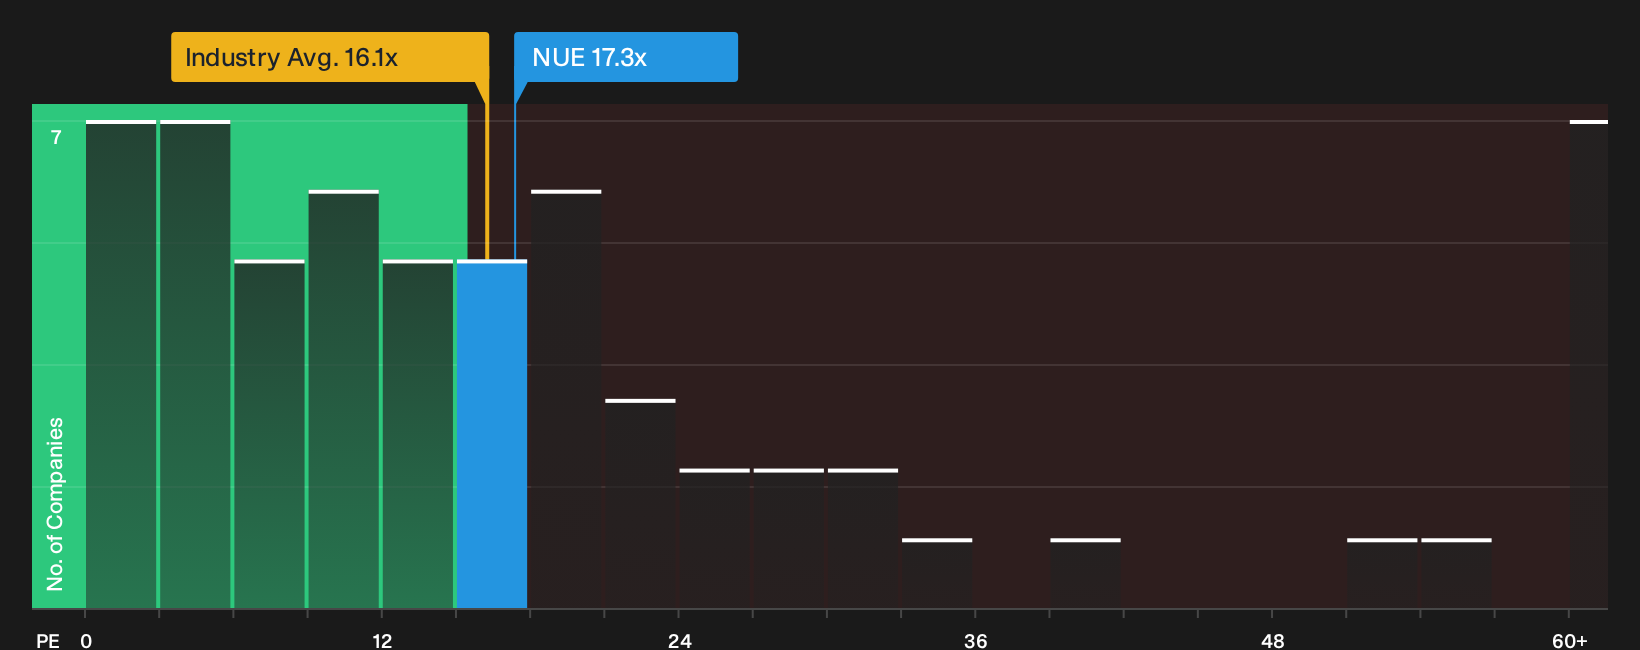
The DCF work suggests Nucor is trading well below an estimate of future cash flow value, yet its current P/E of 17.3x is slightly higher than both the US Metals and Mining industry at 16.1x and the peer average at 16x. The fair ratio is set at 20x. Is the market gradually moving toward that fair ratio, or already reflecting plenty of positive expectations in the price?
That is where valuation becomes more subjective. It can help to see how the detailed earnings and cash flow assumptions feed into the SWS DCF model outcome for Nucor, then compare it with this P/E gap and decide which risk you prefer to focus on: price risk, or execution risk in the projects behind the model. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals or quiet confidence around Nucor? Act while the latest figures are fresh in mind and weigh both sides of the story with 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Nucor?
If Nucor has sharpened your focus on value, do not stop here. Use the Simply Wall Street screener to look for other opportunities.
- Target resilient compounding potential by filtering for consistent cash generators and balance sheet strength with our list of solid balance sheet and fundamentals (25 results).
- Look for possible mispriced quality by scanning companies that pair fundamentals with valuation support through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing reliable high yield candidates surfaced in the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com