


EN
Will Raised 2026 Outlook Change STAG Industrial (STAG) Stock Narrative
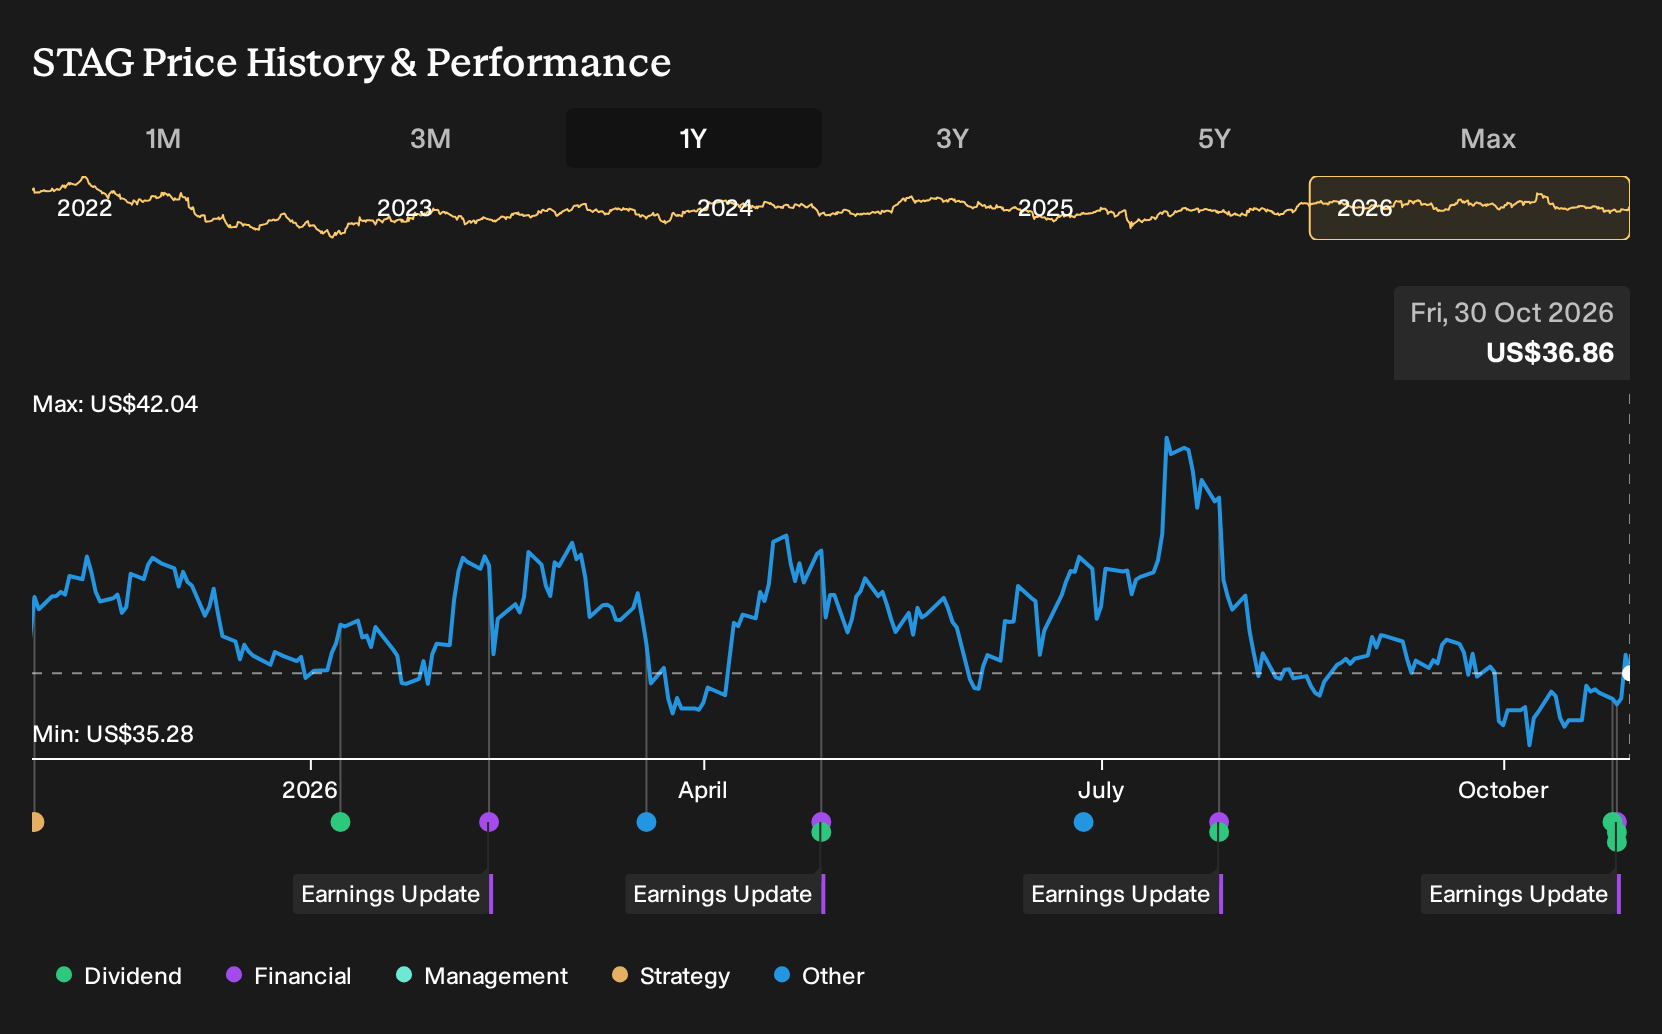
- STAG Industrial reported third quarter 2026 basic and diluted earnings per share from continuing operations of US$0.37, and its board authorized a US$0.3875 fourth quarter dividend per share alongside a new share repurchase program of up to US$250 million with no stated end date.
- Data center related tenants accounted for a large share of new leasing in 2026 and, together with lower than expected credit losses, supported management's decision to raise STAG Industrial's outlook for the year.
- This article examines how STAG Industrial's investment narrative is influenced by the raised 2026 outlook and expanding data center leasing.
Scan beyond STAG Industrial and see which warehouse and infrastructure landlords are also leaning into data center demand with our curated 54 AI infrastructure stocks in one place.
STAG Industrial Investment Narrative Recap
To own STAG Industrial, you need to be comfortable with a simple idea. The business is trying to keep industrial leasing momentum intact while heavy lease expirations roll through and interest costs remain important to watch. The raised 2026 outlook and stronger third quarter earnings per share signal that current operations and credit losses are tracking better than management had budgeted.
The key near term swing factor remains how efficiently STAG Industrial can re-lease space and maintain cash leasing spreads while some markets soften. The biggest risk is that backfilling vacancies drifts beyond the 9 to 12 month assumption, which could pressure occupancy, same store NOI and Core FFO even if data center related demand holds up.
The most relevant fresh datapoint is the US$0.37 basic and diluted earnings per share from continuing operations that STAG Industrial reported for the third quarter of 2026, compared with US$0.26 a year earlier. That result, combined with lower than expected credit losses, underpins the raised outlook and gives management more room to focus on operations rather than course correction.
Nine month earnings per share from continuing operations of US$0.97 compared with US$1.02 a year ago still remind you that the year is not risk free. For catalysts linked to leasing and data center tenants to matter, the trust needs to keep converting that demand into durable rent growth while interest payments, which analysts flag as not well covered by earnings, stay manageable.
STAG Industrial's narrative includes analyst assumptions that revenue grows at about 7.0% per year, reaching US$1.1b of revenue and US$230.5 million of earnings by 2029. This compares with earnings today of US$246.9 million and implies an earnings decline of about US$16.4 million over that period.
Uncover why STAG Industrial's fair value indicates a 13% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster between US$41.75 and US$47.22, which signals tight but not unanimous conviction on where STAG Industrial might trade. Those retail views sit beside risks around slower re leasing and interest rate sensitive acquisitions, so you should weigh several contrasting viewpoints before deciding how this story fits your portfolio.
Explore another STAG Industrial fair value estimate, including one that suggests up to 28% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your STAG Industrial research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for STAG Industrial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STAG Industrial's overall financial health at a glance.
Looking for more investment ideas beyond STAG Industrial
Once you have a view on STAG Industrial, it can help to line it up against other opportunities and see where the risk, income and valuation profiles feel more comfortable for you.
- If you want potential upside without sacrificing balance sheet strength, compare STAG Industrial with a 18 high quality undiscovered gems that pair solid fundamentals with less crowded ownership.
- For readers who care most about capital preservation, filter for steadier businesses using our 30 resilient stocks with low risk scores that screens for resilient profiles and lower overall risk scores.
- If reliable income is your priority, set STAG Industrial alongside a 5 dividend fortresses offering 5%+ yields where stability and payouts sit at the forefront of the thesis.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com