


EN
What Hubbell Stock's Raised Earnings Guidance Means For Shareholders
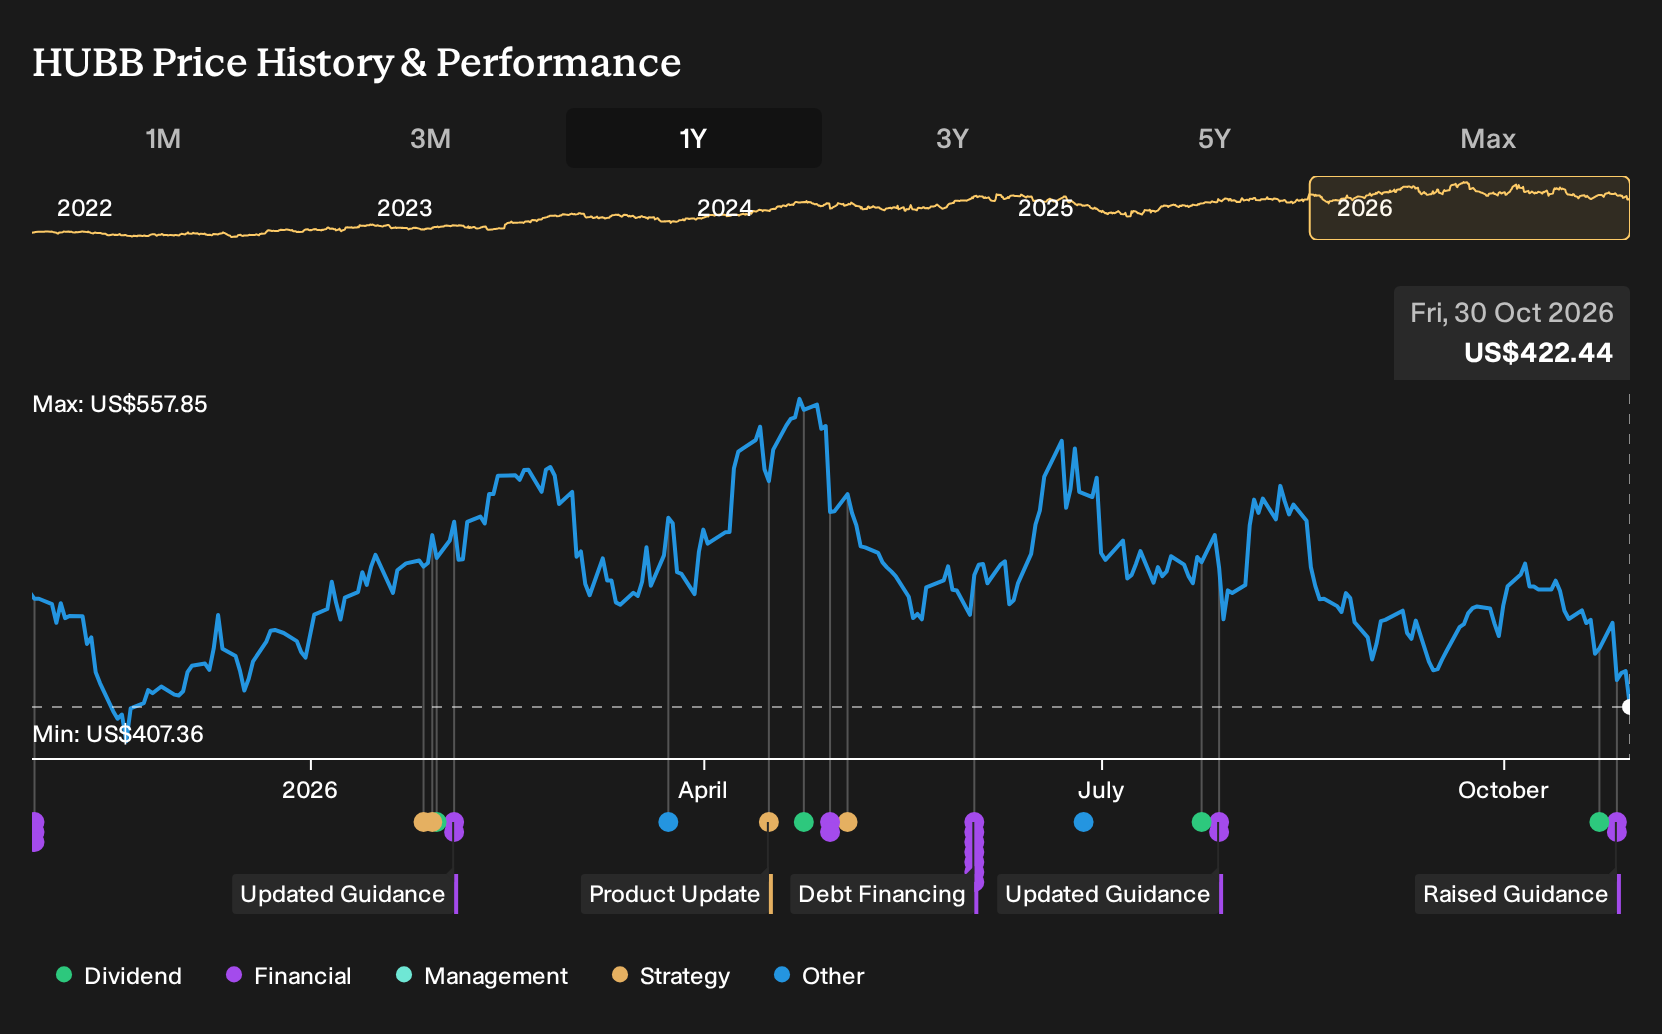
- Hubbell reported third quarter 2026 sales of US$1,872.5 million and GAAP diluted EPS of US$4.94, and updated full year 2026 earnings guidance to a range of US$17.30 to US$17.50 per share on projected total sales growth of 18% to 19%.
- Data center demand is a key swing factor for Hubbell, with Electrical Solutions organic sales rising 22% and data center sales increasing more than 80%, while management prepares for cost inflation with early price increases and higher manufacturing investment.
- Attention now turns to how Hubbell's investment narrative around grid and data center exposure is influenced by stronger guidance associated with data center strength.
Scan for other power grid and data center plays by checking the hand picked 39 power grid technology and infrastructure stocks that reflect the themes in Hubbell's latest earnings and guidance increase.
Hubbell Investment Narrative Recap
To own Hubbell, you need to buy into a simple idea. Grid spending and data center buildouts keep creating work for its Utility Solutions and Electrical Solutions divisions, while pricing and scale help offset higher input costs and interest expense. The raised 2026 guidance leans on that view and keeps data center demand as the key near term catalyst.
The biggest operational risk still sits around margins and leverage. Electrical Solutions has already felt pressure from costs and restructuring, and higher debt means extra interest outlay biting into earnings. Stronger orders from grid and data center customers help, but they do not remove those financial constraints.
Among the recent developments, the increased 2026 earnings guidance is most relevant. Management now expects total sales growth of 18% to 19%, with 10% to 11% organic, and GAAP diluted EPS between US$17.30 and US$17.50. That outlook leans heavily on continued strength in Electrical Solutions, particularly data center related demand.
This same update also connects directly to the main risk. Higher capital intensity, NSI integration work and a planned step up in manufacturing investment sit against a backdrop of elevated debt and higher forecast interest expense. Execution on pricing, cost control and grid automation recovery will matter if Hubbell wants that guidance to translate into durable earnings power.
Hubbell's narrative projects US$8.4b revenue and US$1.3b earnings by 2029. That path lines up with analysts building in 8.6% yearly revenue growth and an earnings increase of about US$392.4m from US$907.6m.
Uncover why Hubbell's fair value points to a 29% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
One alternate view focuses on Hubbell’s high growth CapEx plan as a catalyst. The most optimistic analysts were already penciling in revenue of about US$9.0b and earnings near US$1.3b by 2029 before this guidance hike. That group reads today’s raised outlook as a potential accelerant, although their models may shift once new data settles in.
Explore 2 other Hubbell fair value estimates, including one that suggests as much as 29% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Hubbell research is our analysis highlighting 5 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Hubbell. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Hubbell's overall financial health at a glance.
Looking For More Ideas Beyond Hubbell?
If the Hubbell story has you thinking about where else grid, infrastructure or steady cash generation might show up, the Simply Wall St Screener can help you cast a wider net without losing focus on quality.
- For investors who want potential upside with a quality filter in place, scan through a curated 18 high quality undiscovered gems that line up strong fundamentals with quieter market attention.
- If capital preservation and smoother portfolio swings matter most to you, filter for 30 resilient stocks with low risk scores that pair resilient balance sheets with lower risk scores.
- When dependable cash flows and income are a priority, sort through 5 dividend fortresses that combine higher yields with fundamental support.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com