


EN
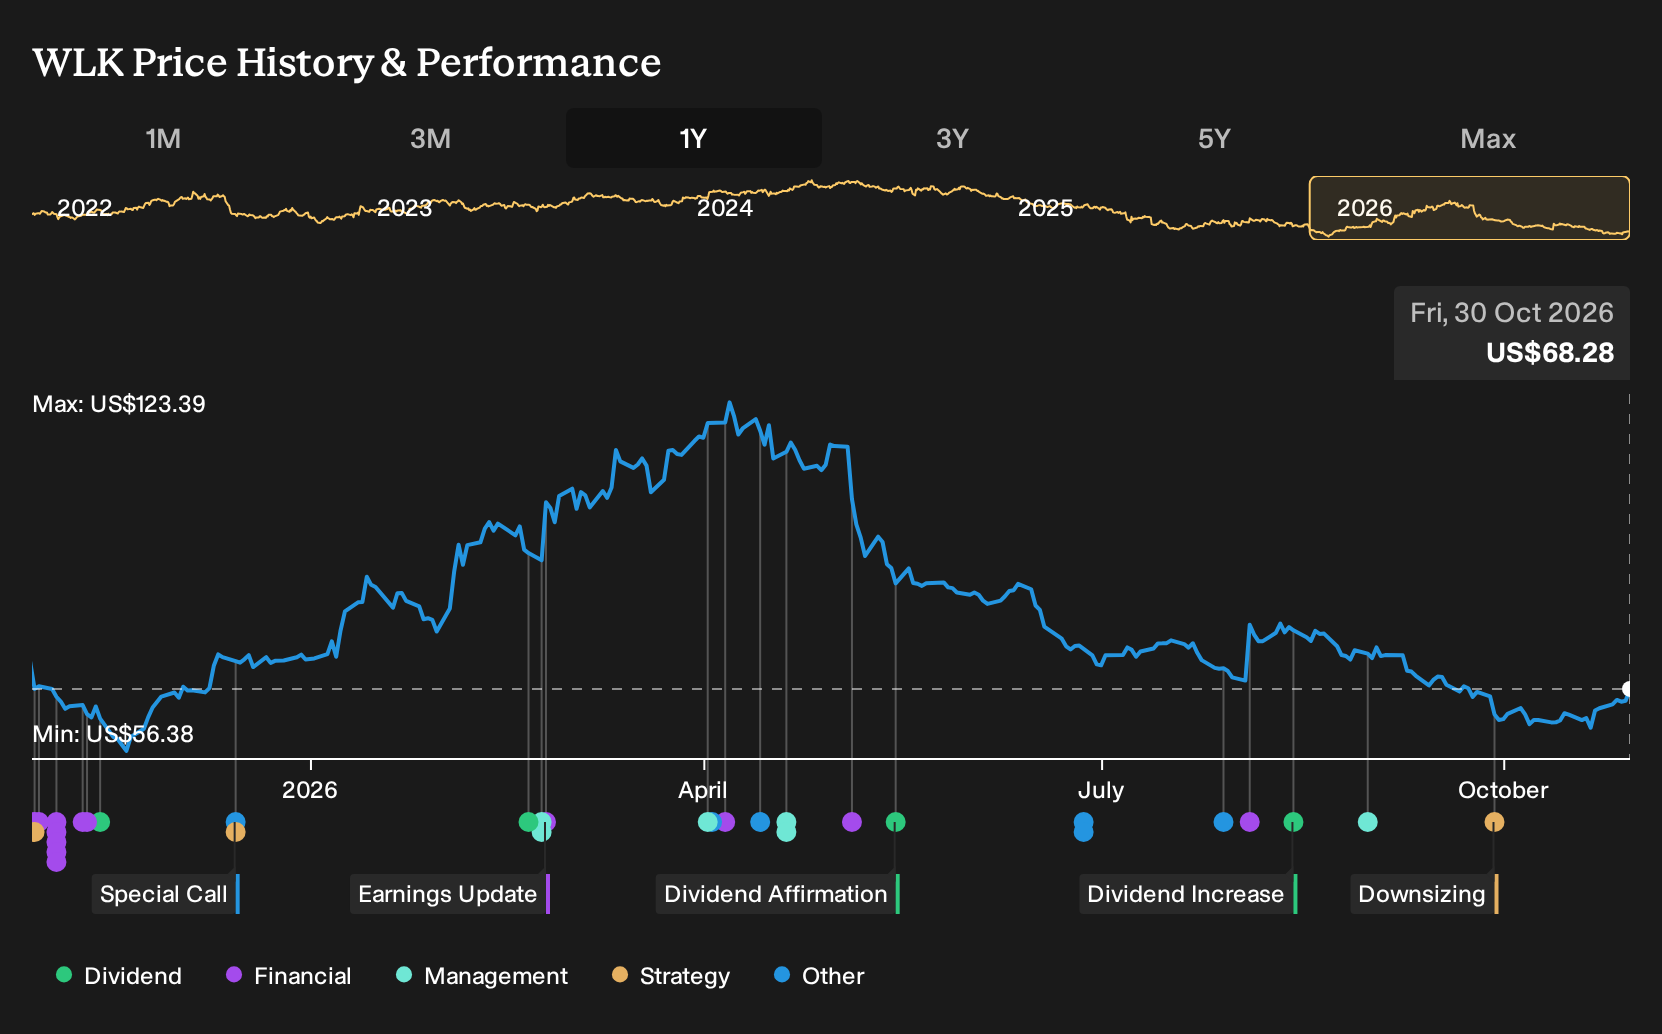
How Investors Are Reacting To Westlake (WLK) Texas Pipe Plant Completion
- Westlake Pipe & Fittings has finished building a 190,000 square foot molecular oriented PVC pipe plant in Wichita Falls, Texas, expanding North American capacity for advanced PVCO products within its Housing & Infrastructure Products division.
- This is described as the largest investment ever made in a Westlake Housing & Infrastructure Products facility, highlighting how management is prioritizing long lived infrastructure demand instead of more cyclical residential exposure.
- We will now look at how Westlake's investment narrative could be influenced by this large scale PVCO capacity addition in Texas.
Scan how other infrastructure focused companies are positioning for long life projects by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) as potential comparison points to Westlake.
Westlake Investment Narrative Recap
To own Westlake, you need to believe that its mix of Performance and Essential Materials and Housing and Infrastructure Products can turn cost efficiency and infrastructure exposure into improving profitability over time. The Wichita Falls PVCO plant fits that view by leaning into long lived municipal and industrial demand rather than short cycle housing, which may help balance softer residential trends.
The most important short term catalyst remains execution on the three pillar profitability improvement plan and the reshaping of the chlorovinyls footprint, because the group is still loss making at the net income line. Key risk stays the same. Prolonged global oversupply, higher North American feedstock costs and freight or PVC resin pressure could offset any operational gains from the new PVCO capacity.
For this PVCO expansion, the most relevant existing catalyst is the multi year increase in U.S. municipal infrastructure spending. The new Wichita Falls facility directly targets water and sewer pipe needs where that public investment and historic under spend in water systems have been supporting demand for Westlake products. That gives the project a clear operational anchor.
The plant also fits into the broader HIP narrative that already includes data center related projects and a focus on long life applications. If Westlake executes well on commissioning, footprint optimization and cost control, the added PVCO capacity can work alongside the profitability program rather than distract from it. If integration is slow or costs run high, investors will likely focus back on already tight margins and the sustainability of the current dividend.
Westlake's narrative projects US$12.7b revenue and US$661.8m earnings by 2029. This is based on an assumption of 4.0% yearly revenue growth and an earnings change of about US$1.9b, from a loss of US$1.2b today to the forecast US$661.8m level.
Discover why Westlake's fair value suggests a 16% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Some of the most optimistic analysts focus on Westlake’s cost cuts as the real catalyst, not just infrastructure demand. Before this Wichita Falls update, the bullish camp was modeling US$14.8b of revenue and US$1.1b of earnings by 2029. You can treat this PVCO expansion as a fresh data point and explore which storyline you find more convincing.
Explore 2 other Westlake fair value estimates, including one that suggests as much as 16% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Westlake research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Westlake. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Westlake's overall financial health at a glance.
Looking for more investment ideas beyond Westlake?
Once you have a view on Westlake, it helps to widen the lens and see how other businesses with different risk and income profiles stack up side by side.
- For investors who want potential upside with stronger balance sheets than typical micro caps, consider scanning the 9 elite penny stocks with strong financials that clear a basic quality bar.
- If value and resilience matter most to you, start with a curated group of companies screened for both financial strength and attractive pricing through the 29 high quality undervalued stocks.
- When capital preservation and steadier cash flows are higher priorities, you can focus on income oriented opportunities by filtering for reliable payers with the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com