


EN
Will Stronger Fundamentals Change Plains All American Pipeline Stock Narrative
- Recent coverage has highlighted Plains All American Pipeline's crude focused midstream model, fee based infrastructure, and execution risks around projects like Cactus III and new gathering systems.
- The business now appears more tightly linked to crude oil fundamentals due to prior NGL divestitures and concentrated capital spending on higher return assets and cost efficiency programs.
- We will now look at how Plains All American Pipeline's stronger return on equity profile reshapes the broader investment narrative around the stock.
Scan how Plains All American Pipeline compares with other midstream operators by reviewing a curated list of list of solid balance sheet and fundamentals (25 results) for additional ideas in this corner of the market.
Plains All American Pipeline Investment Narrative Recap
For a shareholder in Plains All American Pipeline, the core belief is that a focused crude oil midstream model can keep generating steady fee based cash flows while returns on new capital projects stay attractive. Recent news highlighting better return on equity versus a key peer supports that efficiency angle, but it does not materially change the near term story.
The key short term swing factor is still execution on Cactus III, the Powder River Basin build out, and the US$400m to US$450m 2026 growth budget without stretching the balance sheet. The biggest risk remains concentrated exposure to crude volumes and tariffs if basin activity or customer demand softens.
The comparison to Energy Transfer that flagged Plains All American Pipeline’s stronger return on equity, lower debt usage, and better recent price performance is most relevant for how investors think about execution risk. A tighter capital structure with lower leverage can give management more room to deal with project delays or weaker throughput.
That said, the benchmark against Energy Transfer does not remove the operational work ahead. The thesis still leans on hitting targeted cost efficiencies, realizing identified Cactus III synergies, and keeping leverage within the 3.25x to 3.75x range while funding organic projects and distributions from expected 2026 adjusted free cash flow.
Plains All American Pipeline's analyst narrative points to forecast revenue of US$65.1b and expected earnings of US$1.6b by 2029. This implies yearly revenue growth of 7.5% and an earnings increase of roughly US$779m from current earnings of US$821.0m.
Uncover how Plains All American Pipeline's fair value is essentially in line with its current price.
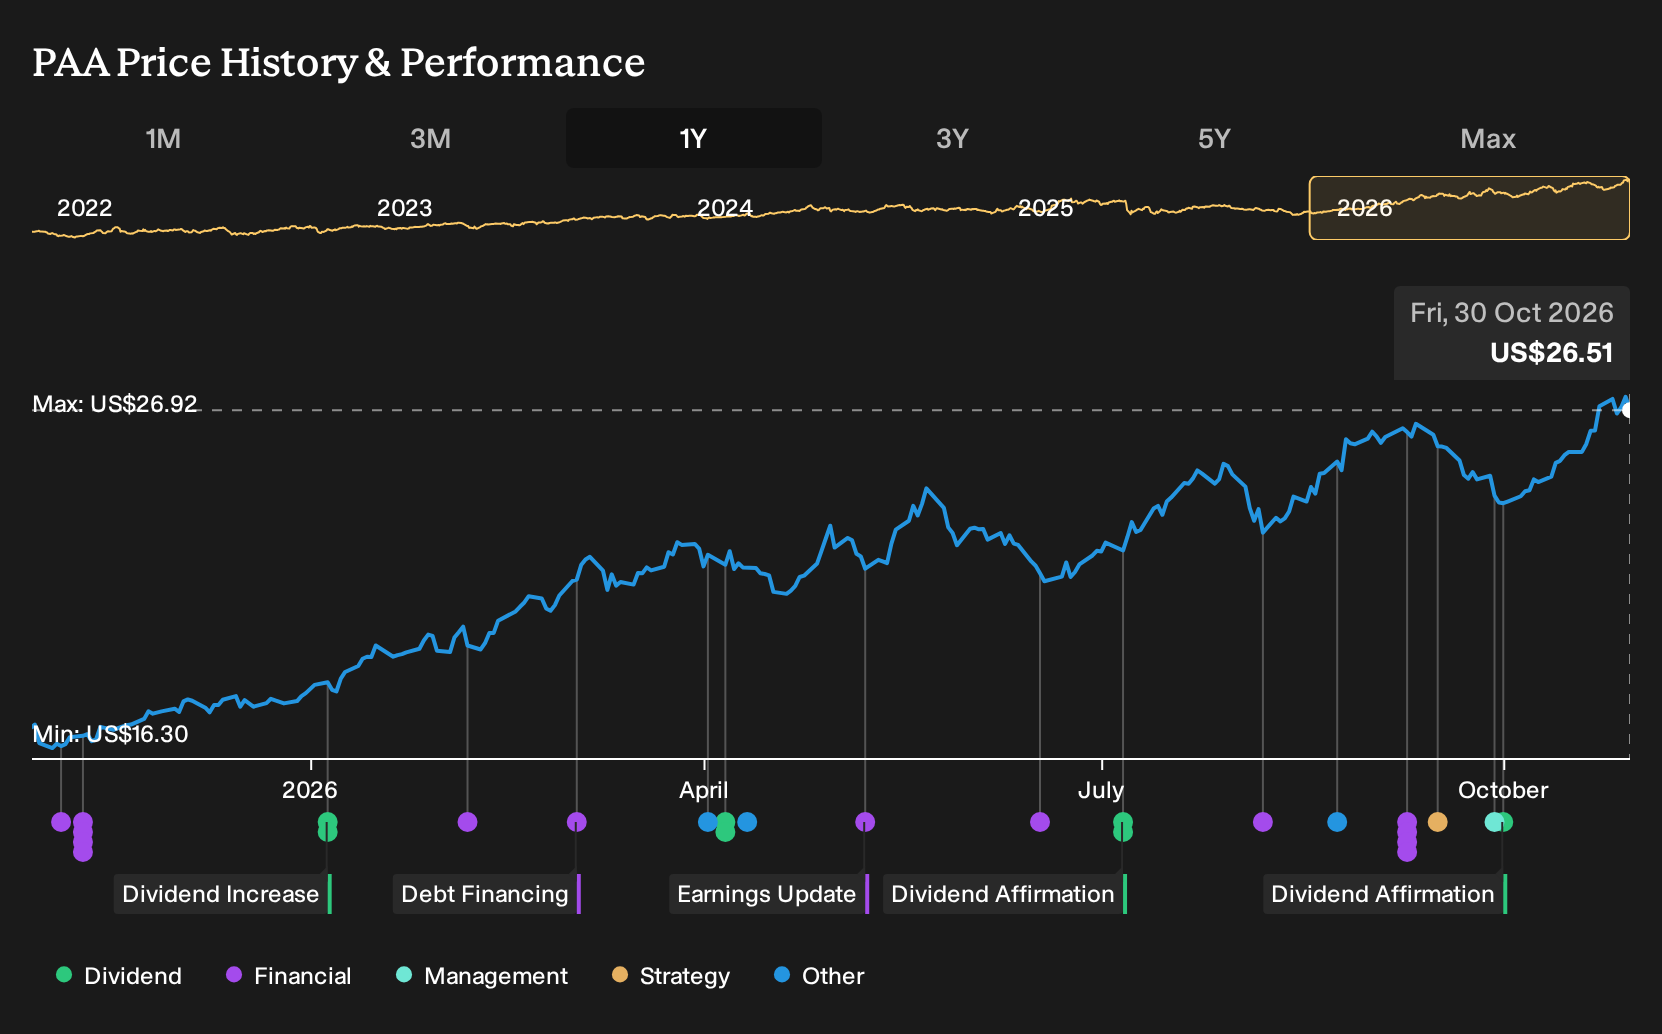
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community span roughly US$26.76 to US$74.43 per unit, which illustrates how far apart retail opinions on Plains All American Pipeline can be. Those estimates were formed before the latest commentary on execution risk and crude concentration, so treat them as a starting point and explore several alternative viewpoints.
Explore another Plains All American Pipeline fair value estimate, including one that suggests it could be worth just $26.76.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider developing your own view.
- A great starting point for your Plains All American Pipeline research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Plains All American Pipeline. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Plains All American Pipeline's overall financial health at a glance.
Looking for more investment ideas beyond Plains All American Pipeline?
Once you have a view on Plains All American Pipeline, it can help to widen the lens and compare it with other opportunities that share similar financial qualities or risk profiles. The Simply Wall St Screener offers a fast way to surface companies that match the type of balance sheets, income streams, and resilience you want in your portfolio.
- For investors who care most about durable finances and flexibility through different cycles, start with a list of solid balance sheet and fundamentals (25 results) that emphasises stronger balance sheets and cleaner fundamentals.
- If your focus is on finding quality at a reasonable entry point, sort through a 29 high quality undervalued stocks that filters for companies where fundamentals and price look out of sync.
- Income focused readers who prioritise cash returns can review a 5 dividend fortresses aimed at higher yield payers with more robust profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com