


EN
Could Viavi Solutions (VIAV) Be 51% Undervalued As It Expands NITRO AI?
Viavi Solutions (VIAV) just rolled its Model Context Protocol Server Framework into the NITRO AI suite, allowing engineers to conduct network, security and access testing using conversational prompts instead of traditional scripts.
Despite the AI-focused product update, Viavi Solutions has been under pressure in the short term, with the share price falling 10.2% over the last day and 28.6% over the past month. This comes even as the year-to-date share price return sits at 64.9% and the three-year total shareholder return is around 2.6x, suggesting longer-term momentum remains intact while near-term sentiment cools.
Scan beyond Viavi Solutions and see how other AI infrastructure plays are setting up in the current market using our hand-picked 54 AI infrastructure stocks
Viavi Solutions has delivered a sharp pullback even after strong multi year total returns, which leaves a simple question hanging: does the current setup still tilt the risk reward towards new buyers once the valuation is unpacked next?
Most Popular Narrative: 51% Undervalued
On the latest numbers, the most followed narrative sees Viavi Solutions worth $61.43 a share compared with the recent close at $29.92. This frames the current drop as a valuation gap rather than just a sentiment swing.
Viavi is experiencing robust and sustained demand across the data center ecosystem, with customers updating optical connectivity to 400G, 800G, and now 1.6T, enabling multi-year upgrade cycles and expanding its total addressable market. This is expected to drive structural revenue growth through 2026 and beyond. Increasing demand for end-to-end network instrumentation from the data center sector, now viewed as mission-critical, is expected to reduce historical cyclicality linked to telecom service provider budgets and provide more consistent revenue visibility and a smoother earnings trajectory.
See why 16 investors see Viavi Solutions as 51% undervalued.
Result: Fair Value of $61.43 (UNDERVALUED)
Still, the Viavi Solutions story can unravel if prolonged weakness in wireless test demand and any stumbles integrating recent acquisitions hit revenue and pressure margins more than analysts expect.
Find out about the key risks to this Viavi Solutions narrative.
Another View: Cash Flows Point To A Tighter Margin For Error
Analyst narratives suggest Viavi Solutions is roughly 51% undervalued, yet our DCF model provides a more restrained perspective. On that cash flow view, the shares at $29.92 sit slightly above an estimated value of $28.11, which indicates more limited upside and a greater risk of disappointment if growth or margins weaken.
This contrast between an optimistic narrative and a more conservative cash flow model puts the focus back on your assumptions. If you use the SWS DCF model as a cross-check rather than your primary guide, it is worth considering how much optimism you are comfortable embedding in your view of Viavi Solutions.
Look into how the SWS DCF model arrives at its fair value.
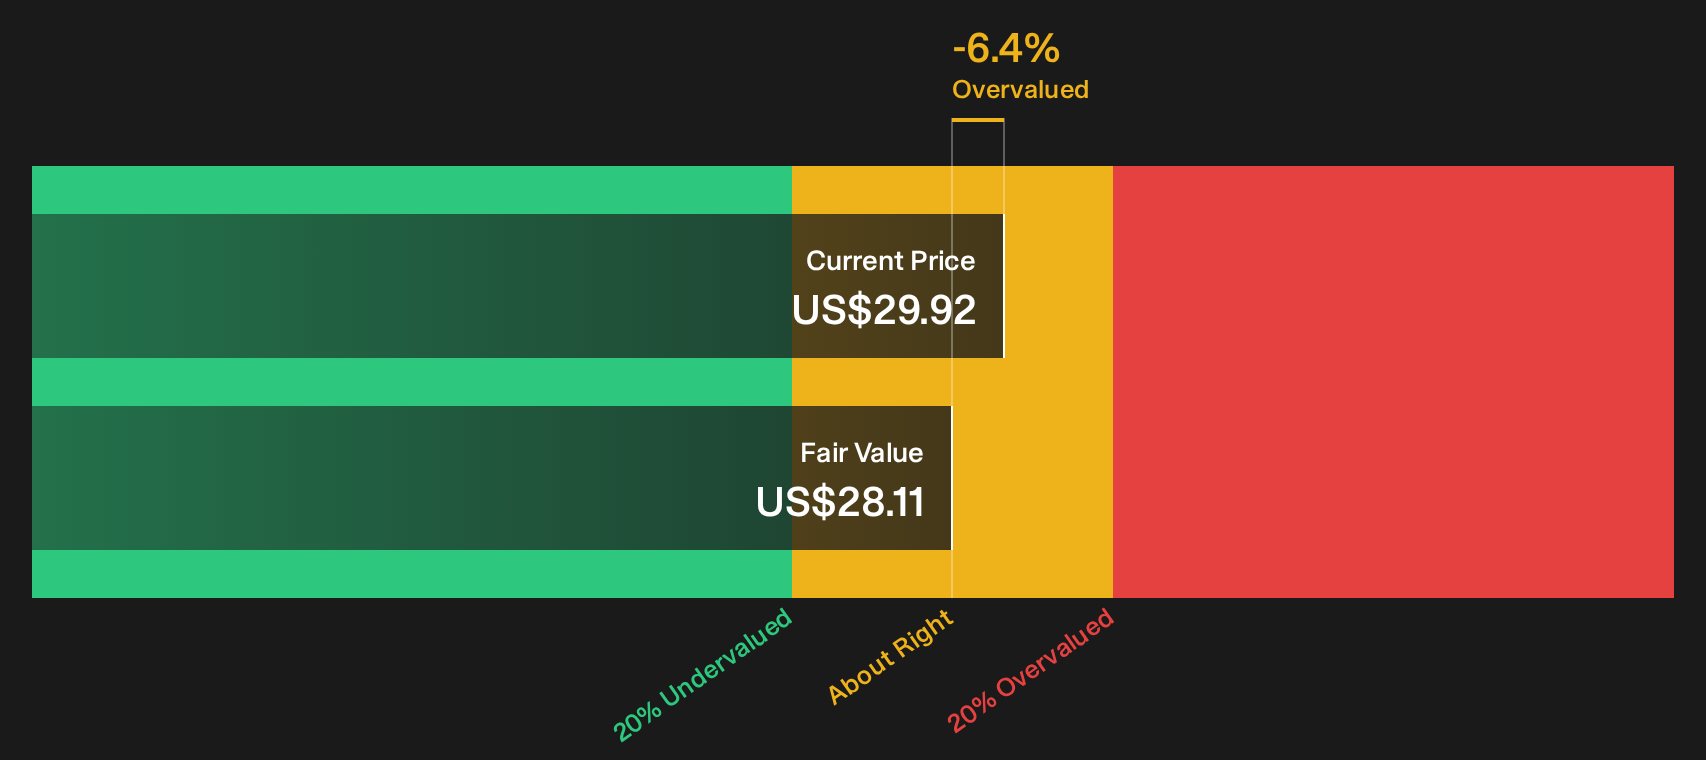
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Viavi Solutions for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on Viavi Solutions is clearly split. Move quickly, review the underlying data, and evaluate both sides of the argument for yourself with the full 2 key rewards and 2 important warning signs
Looking For More Ideas Beyond Viavi Solutions?
If Viavi Solutions is on your radar, you can broaden your opportunity set and pressure test your thesis by scanning other high quality setups that might fit your style.
- Target quality at a discount by reviewing our hand picked 29 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them.
- Prioritise resilience and capital preservation by working through a focused 30 resilient stocks with low risk scores that screens for sturdier balance sheets and steadier return profiles.
- Get ahead of the crowd by combing through a curated 18 high quality undiscovered gems that highlights under followed businesses with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com