


EN
SAP Deal Could Shift DocuSign (DOCU) Stock Investment Narrative
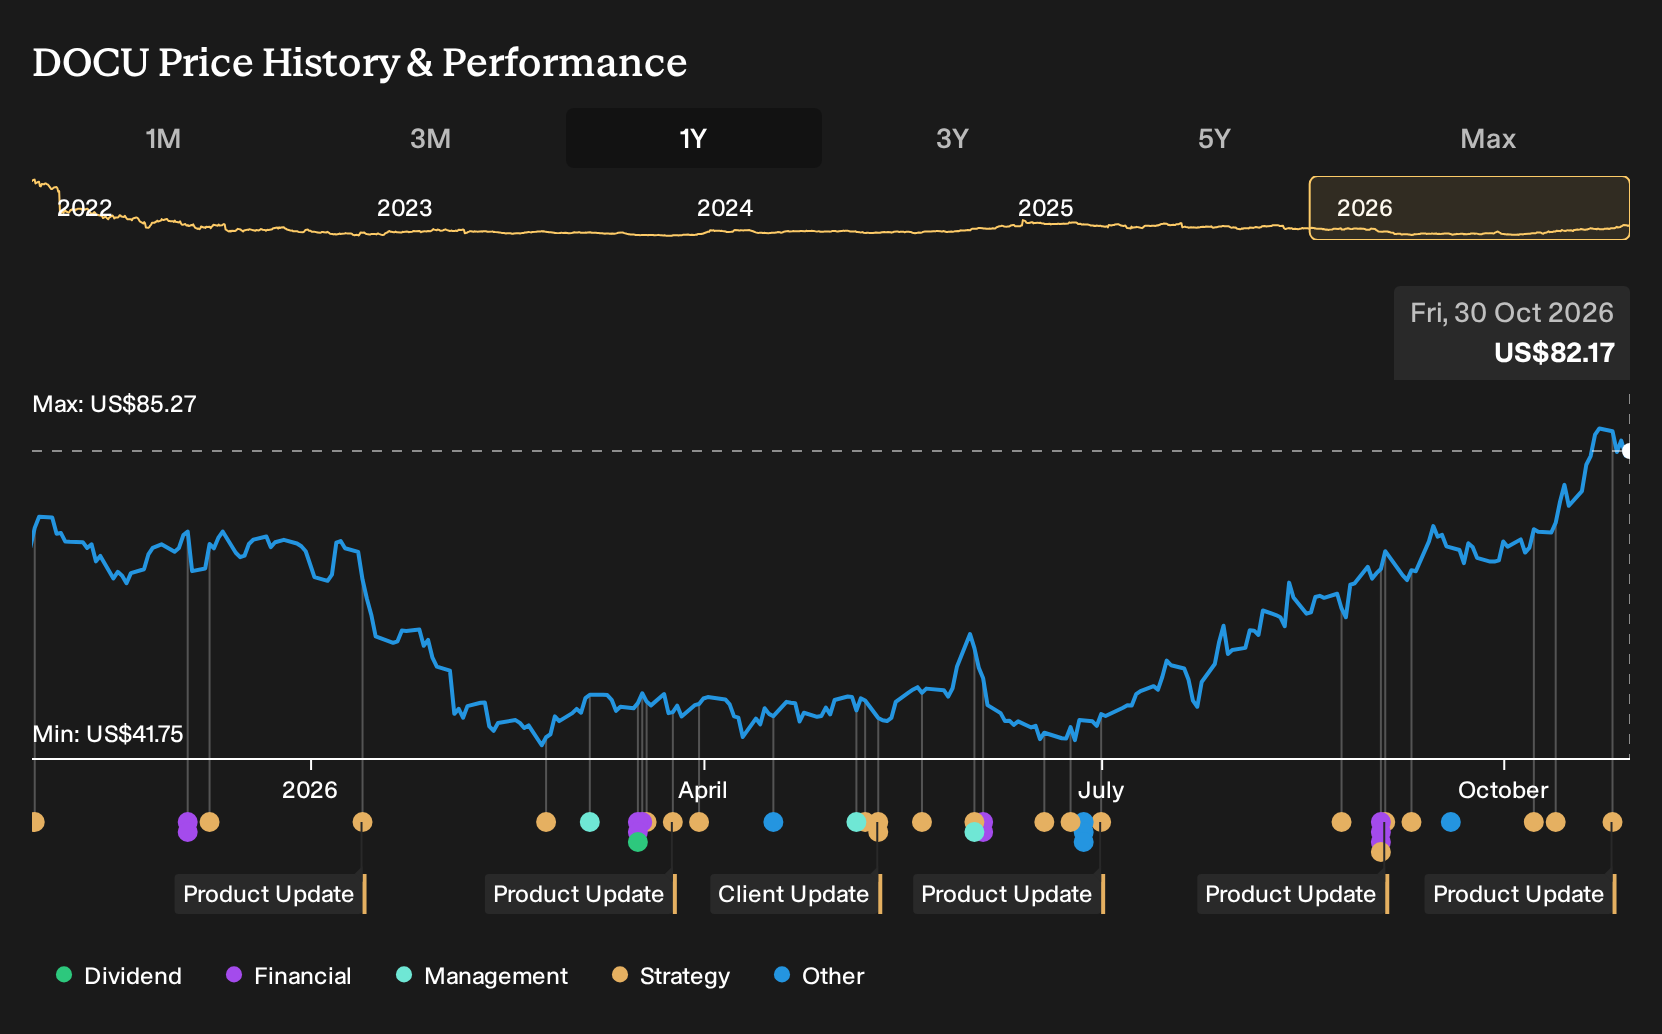
- In late October 2026, DocuSign said its Intelligent Agreement Management products for SAP Sales Cloud and SAP SuccessFactors would be sold as SAP branded Solution Extensions, embedding creation, signing, and management of agreements directly into core sales and HR workflows.
- This shift moves DocuSign deeper into SAP’s distribution and support channels and ties its IAM platform directly to mission critical enterprise processes like contract execution, onboarding, and compliance verification.
- We will now look at how DocuSign's investment narrative could shift as IAM becomes tightly embedded in SAP Sales Cloud workflows.
DocuSign Investment Narrative Recap
To own DocuSign, you need to believe IAM becomes a core workflow layer for large customers, not just an e-signature add-on. The SAP news fits that view by wiring agreements directly into sales and HR systems. It supports the idea that IAM’s rising share of ARR can matter more over time than headline ARR growth that has recently sat in the mid-single digits.
The short-term swing factor is whether deeper enterprise integrations help offset weak ARR momentum and long sales cycles. The key risk stays the same. If big-ticket deals and international expansion do not ramp as expected, high single-digit revenue growth and migration costs could pressure conviction in margins and limit enthusiasm around the stock.
The most relevant recent context is the reported 5.5% ARR growth and anticipated 8.1% sales growth that point to a competitive market and long payback on sales and marketing. Set against that, the SAP Solution Extensions move squarely targets higher-value, embedded IAM use cases that could make each large customer more meaningful even if customer additions stay harder to win.
Investors watching DocuSign may now frame catalysts less around broad e-signature demand and more around proof that these SAP-aligned workflows translate into better ARR productivity per dollar of selling expense. The risk is execution. If these deeper integrations complicate implementation or fail to improve visibility into renewals and expansions, then the business could carry the complexity without seeing the faster agreement-driven activity that many shareholders are looking for.
What The Current DocuSign Forecasts Are Telling You
DocuSign's narrative projects US$4.2b revenue and US$624.4 million earnings by 2029. That profile uses analysts' 7.9% yearly revenue growth assumption and implies an earnings increase of about US$294.5 million from the current US$329.9 million level.
Uncover why DocuSign's fair value indicates a 15% potential downside to its current price, leaving little room for error.
Exploring Other Perspectives
One alternate view says the real issue for DocuSign is not product quality but how much you might be paying for that quality. The lowest analysts were only pencilling in about US$4.1b revenue and US$567.7 million earnings by 2029. That more cautious story has not yet reacted to the SAP Solution Extensions news, so you have room to compare both angles yourself and see which future you find more convincing.
Explore 6 other DocuSign fair value estimates, including one that suggests as much as 36% downside from the current price!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your DocuSign research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for DocuSign. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate DocuSign's overall financial health at a glance.
Looking for more investment ideas beyond DocuSign?
If DocuSign's agreement story has you thinking about what else might be mispriced or overlooked, the Simply Wall St Screener can help you widen the net while still keeping a disciplined process.
- If you want to focus on quality that might be flying under the radar, start with a 18 high quality undiscovered gems and see which businesses have fundamentals that look stronger than their profiles suggest.
- If resilience and balance sheet strength matter most to you, filter for companies with low leverage and solid cash buffers using the list of solid balance sheet and fundamentals (25 results) so you can concentrate on sturdier profiles.
- If you prefer ideas where downside risk scores are already screened, use the 30 resilient stocks with low risk scores and narrow in on businesses that rank better on Simply Wall St's risk framework.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com