


EN
Did Softer Quarterly Earnings Just Shift SouthState Bank Stock's Investment Narrative?
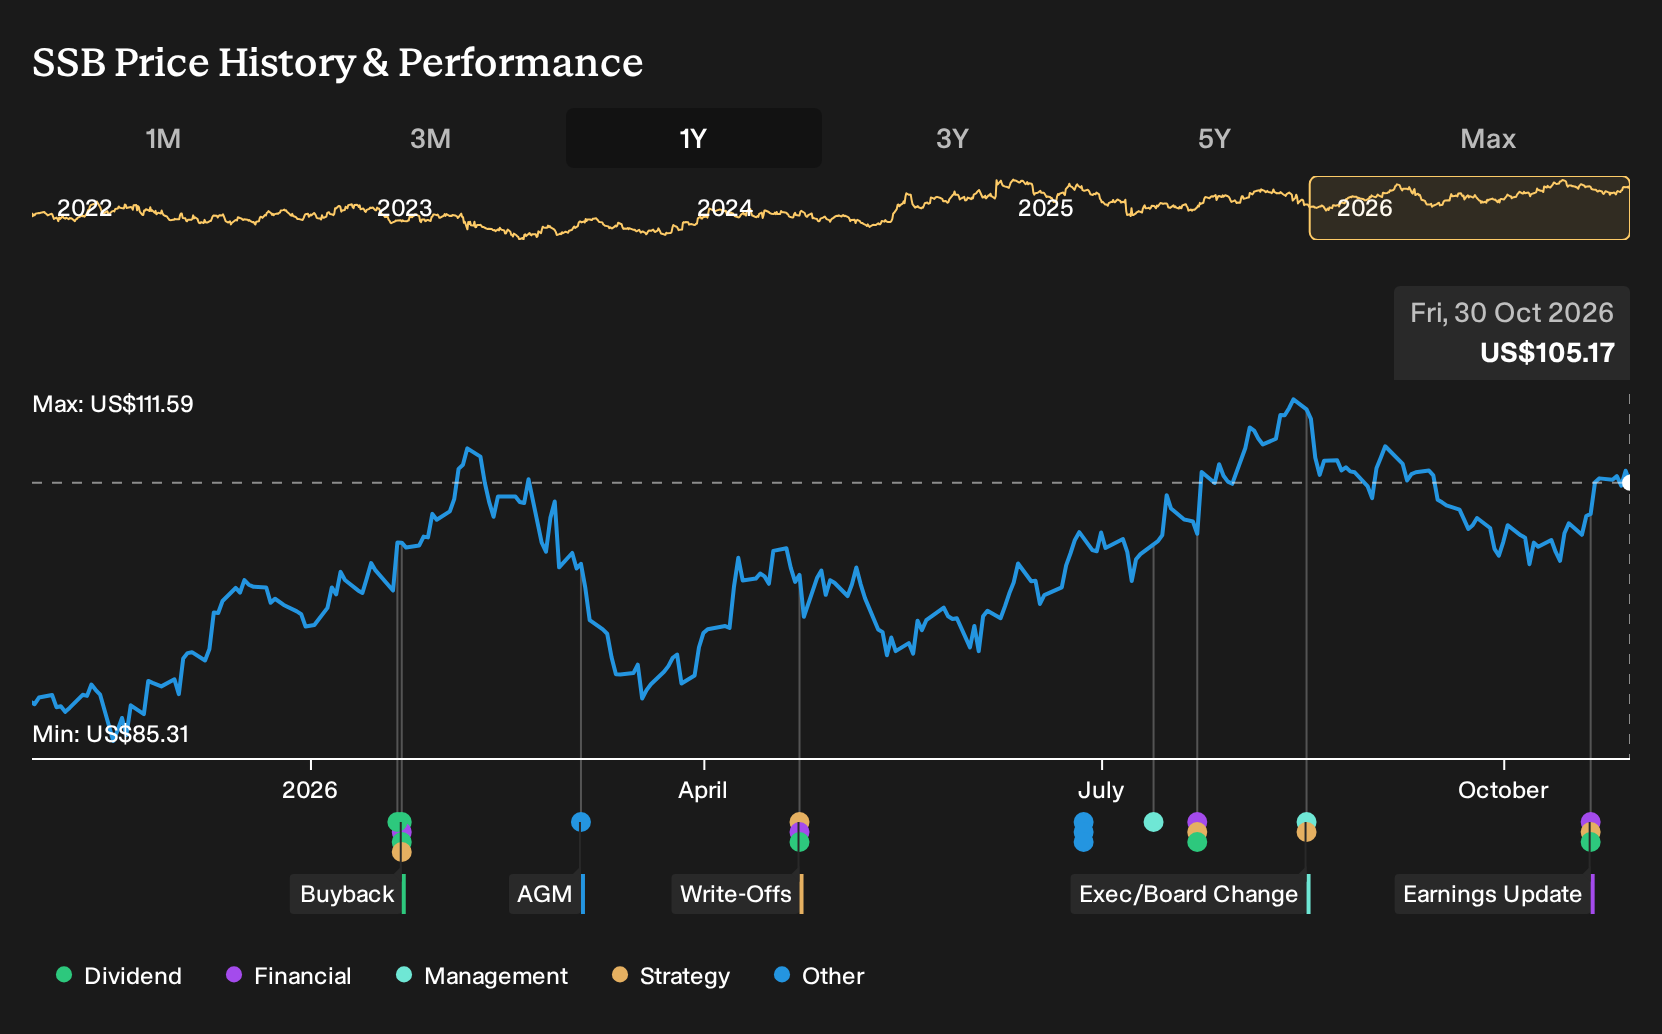
- SouthState Bank reported third quarter 2026 results with net interest income of US$591.52 million and net income of US$223.8 million, alongside a quarterly dividend of US$0.66 per share and US$26.11 million of buybacks completed in the period.
- The nine month earnings profile shows US$679.64 million of net income and ongoing capital returns. The latest US$12 million in net charge offs highlights how credit costs continue to shape SouthState Bank's earnings mix.
- This article will look at how SouthState Bank's investment narrative interacts with softer quarterly earnings and continued share repurchases and dividends.
See how SouthState Bank's mix of dividends, buybacks and credit costs compares with other income focused financial stocks in our curated 5 dividend fortresses.
SouthState Bank Investment Narrative Recap
To own SouthState Bank, you need to be comfortable with a story built on steady net interest income, loan growth in newer markets like Texas and Colorado, and tight control of funding costs. The latest quarter showed softer net interest income and earnings per share compared with a year ago. This keeps pressure on deposit pricing and margin management as the key short term catalyst.
The biggest operational risk right now sits in that same area. Deposit costs and a loan to deposit ratio already just above 90% leave less room if funding becomes more expensive. Net charge offs of US$12 million also keep credit quality on the radar, although this single data point does not materially alter the broader thesis by itself.
The most directly relevant update for investors is the third quarter earnings report itself. Net interest income of US$591.52 million and net income of US$223.8 million, along with diluted EPS from continuing operations of US$2.30, provide a fresh read on how SouthState Bank is balancing loan growth, funding pressures and credit costs in real time.
Viewed against the nine month numbers, with net income of US$679.64 million and basic EPS from continuing operations of US$6.96, current profitability supports SouthState Bank's ability to keep investing in growth markets and technology while still paying dividends and completing buybacks. Those capital returns will matter most if the bank can keep funding cost risk contained and credit losses predictable.
SouthState Bank Earnings Path and Analyst Assumptions
Analysts sketch a future for SouthState Bank where the income statement leans on revenue forecasts of US$3.2b and projected earnings of US$1.1b by 2029. That outlook is built on an assumed 6.1% yearly increase in revenue and an earnings step up of about US$149.8m from current earnings of US$950.2m, with 2029 set as the key forecast year.
Uncover why SouthState Bank's fair value indicates a 14% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value views from the Simply Wall St Community place SouthState Bank between roughly US$119.86 and US$195.25, a wide band for just a pair of estimates. That range meets fresh information on rising deposit costs, a loan to deposit ratio just above 90% and steady buybacks and dividends. Opinions may differ. Use these contrasting readings to test your own thesis.
Explore another SouthState Bank fair value estimate, including one that suggests it could be worth just $119.86.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your SouthState Bank research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for SouthState Bank. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SouthState Bank's overall financial health at a glance.
Looking For More Investment Ideas Beyond SouthState Bank?
Once you have formed a view on SouthState Bank, it can help to set it alongside other opportunities that share similar income or quality traits. The Simply Wall St Screener lets you do that quickly by filtering for companies that match the kind of balance sheet strength, dividend profile or risk level you want to focus on next.
- If you care most about capital strength and resilience, start by scanning a list of solid balance sheet and fundamentals (25 results) that pairs robust finances with fundamental quality filters.
- For investors who want quality at a reasonable entry point, compare SouthState Bank against a 29 high quality undervalued stocks selected using both cash flow and balance sheet checks.
- If lower volatility and capital protection matter more to you than raw upside, narrow your watchlist with a 30 resilient stocks with low risk scores that screens for businesses with more defensive risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com