


EN
Why EchoStar (ECHO) Is Getting Attention Now
EchoStar event puts earnings uncertainty in focus
EchoStar (ECHO) stepped into the spotlight as its Head of Agentic AI Platform Operations addressed the Denver CIO Executive Leadership Summit, just as forecasts flagged a potential year-over-year earnings and revenue decline.
Recent trading tells a mixed story. EchoStar’s share price has climbed 15.28% over the past 90 days and 8.42% over the last month, yet remains down 13.59% year to date. At the same time, the 1 year total shareholder return of 29.48% and a very large 3 year total shareholder return above 7x point to powerful longer term momentum that now meets rising earnings uncertainty ahead of the next result.
Spot similar risk and reward setups around EchoStar by scanning our hand-picked 29 high quality undervalued stocks, which shows solid fundamentals with prices that have not yet caught up.EchoStar has rallied hard, but its last close of US$96.94 still sits well below an average analyst target of US$130.20. Where does a fair valuation really fall inside that spread as earnings uncertainty builds?
Most Popular Narrative: 26% Undervalued
On the most widely followed view, EchoStar’s fair value of $130.20 sits well above the last close at $96.94. This puts the focus firmly on how its cash, spectrum and SpaceX exposure are managed from here.
The main requirement for success is disciplined capital allocation around the SpaceX stake, remaining spectrum and cash, while keeping Boost, DISH TV, Sling and Hughes on a clear path to sustainable profitability.
The numbers suggest the share price reflects a large discount to the estimated value of EchoStar's SpaceX holdings, remaining spectrum and operating businesses, so the stock appears to be pricing in meaningful execution and governance risk.
See why 26 investors see EchoStar as 26% undervalued.
Result: Fair Value of $130.20 (UNDERVALUED)
Still, the EchoStar story could change quickly if bankruptcy related cash outflows run higher than expected or if volatility in SpaceX equity holdings affects reported book value and earnings.
Find out about the key risks to this EchoStar narrative.
Another View: EchoStar Looks Expensive On Sales
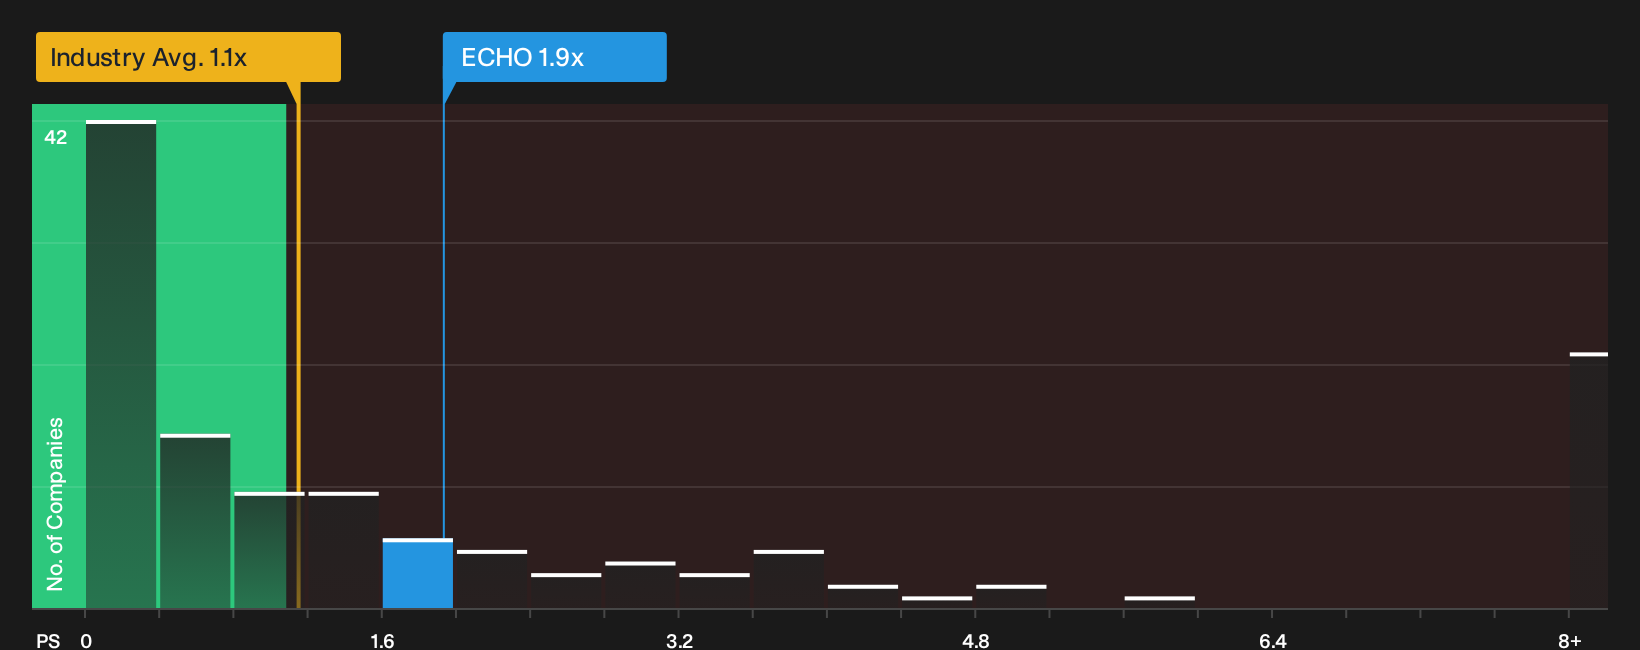
EchoStar appears inexpensive compared with a US$130.20 fair value based on analyst expectations, yet the P/S ratio of 1.9x tells a different story. The US Media sector averages 1.1x and close peers sit near 0.9x, while the fair ratio is 1.3x. That premium highlights valuation risk if growth or execution weaken, so which signal should carry more weight for you?
For a closer look at how the current price lines up with this sales based view, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Earnings anxiety or opportunity? If EchoStar’s mix of risks and potential rewards has your attention, pressure test the story for yourself by weighing the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond EchoStar?
If EchoStar has sharpened your focus on risk and reward, broaden your watchlist with a few targeted screens that surface clear, data driven opportunities.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for pricing gaps where fundamentals look strong and valuations still lag by checking the 29 high quality undervalued stocks.
- Prioritise stability and capital protection by reviewing the 30 resilient stocks with low risk scores that filters for companies with lower risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com