


EN
Will Earnings Expectations Change Analog Devices Stock Narrative
- Analog Devices is heading into its fiscal 2026 fourth quarter report with analyst forecasts calling for higher EPS and revenue versus the prior year, supported by demand linked to AI, 5G, automotive and energy efficient computing.
- Management plans to return 40% to 60% of free cash flow through dividends and buybacks, while flagging potential AI capital expenditure softness and rising competition. This puts the focus squarely on how effectively the business converts design wins into sustained, high margin revenue.
- Next, the focus shifts to how Analog Devices' upcoming earnings expectations and capital return plans could reshape the broader investment narrative.
Compare Analog Devices' setup ahead of earnings with a curated list of other chip makers tied to AI, data centers and advanced computing through the 54 AI infrastructure stocks.
Analog Devices Investment Narrative Recap
To own Analog Devices, you need to believe its exposure to AI data centers, industrial, automotive and energy efficient computing can convert into durable, high margin demand rather than a brief surge. The upcoming November 24 fiscal Q4 print is the key near term check on that story, especially around data center orders and industrial recovery.
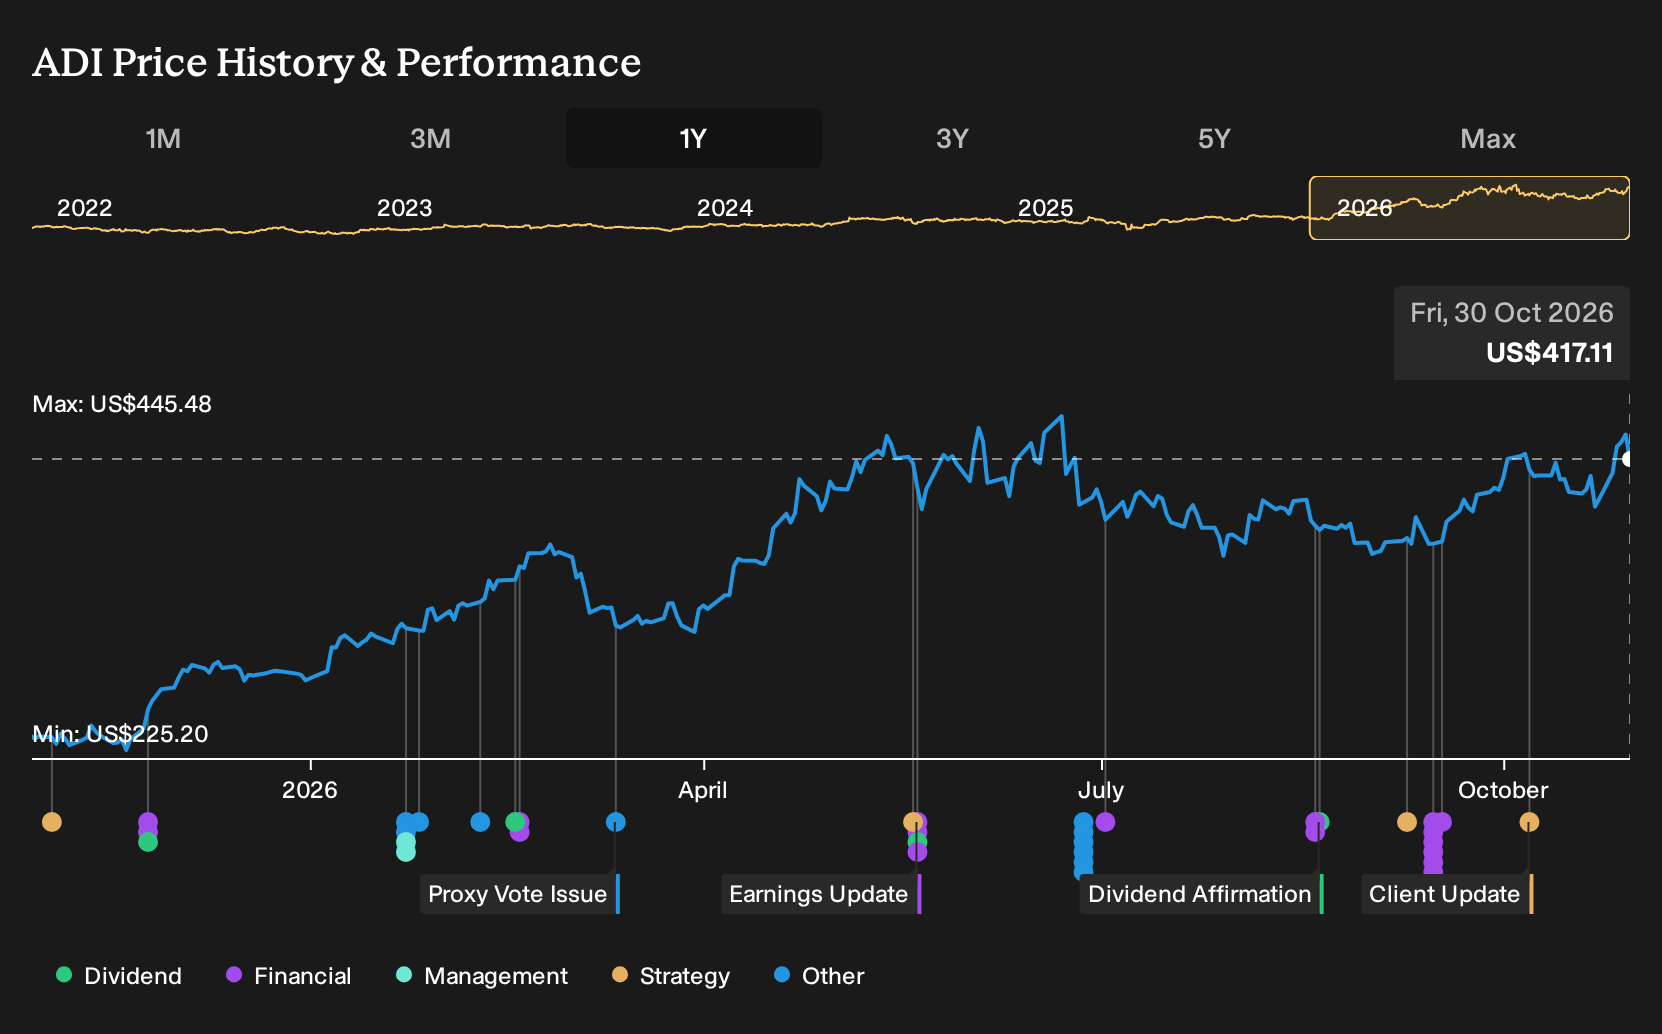
The biggest short term swing factor is how resilient AI related spending and communications demand prove to be after management flagged possible AI capex softness. Rising competition and any pricing pressure in China or other regions remain the central risk. The recent share price strength ahead of earnings does not materially change those core drivers.
The clearest announcement tied to this setup is management’s plan to return 40% to 60% of free cash flow through dividends and buybacks, with part of the balance also earmarked for repurchases. For investors, that puts execution on cash generation and margins at the center of the story, not just headline revenue trends.
Analog Devices currently pays a US$1.10 quarterly dividend, compared with Texas Instruments at US$1.52, and runs a higher P/E multiple than several peers. That combination means the capital return plan can support the case for owning ADI only if design wins in AI, automotive, industrial and aerospace translate into sustained, profitable shipment volumes while competition and geopolitics remain manageable.
What The Current Forecasts Assume For Analog Devices
Analog Devices' current analyst blueprint rests on several moving parts that can be quantified. The consensus view looks for revenue to grow at about 16.0% a year over the next three years, with profit margins projected to rise from 29.8% today to 40.1% by around 2029. On earnings, analysts are modeling an increase from US$4.1b today to US$8.7b by the 2029 estimate year, which is roughly a 2x increase in profit if those projections are met.
The future profit outlook does not come with a single, precise forecast. The most optimistic analysts are penciling in US$10.1b of earnings, while the most cautious sit at US$7.1b, so the range of outcomes on the income statement is wide. There is also an expectation that the share count gradually shrinks, with forecasts pointing to a 1.04% yearly decline in outstanding shares over the next three years as buybacks reduce equity. For anyone tracking return of capital, that shrinking base sits alongside the stated plan to send 40% to 60% of free cash flow back to shareholders through dividends and repurchases.
On valuation, the consensus snapshot has Analog Devices reaching US$21.7b of revenue and US$8.7b of earnings by 2029, and then trading on a P/E of 35.2x on those modeled profits. That implies a lower multiple than the current 46.7x that analysts have cited for the stock and also sits below the 46.9x P/E quoted for the broader US semiconductor group in the same analysis set. The gap between today and that implied future is a key factor in target price calculations because it assumes both higher profits and a lower earnings multiple at the same time.
Analog Devices' narrative projects US$21.7b revenue and US$8.7b earnings by 2029. This would involve 16.0% yearly revenue growth and roughly a 2x earnings increase from US$4.1b today.
Uncover how Analog Devices' fair value indicates a 13% potential upside to its current price, which could narrow quickly if sentiment catches up.
Exploring Other Perspectives
One bullish twist on Analog Devices focuses on AI power and energy systems. The most optimistic analysts were modeling about US$29.5b in 2029 revenue with earnings near US$10.1b, well above consensus. Those figures were set before this earnings run up and the November 24 report, so your view may change as new information lands.
Explore 5 other Analog Devices fair value estimates, including one that suggests as much as 37% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Analog Devices research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Analog Devices. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Analog Devices' overall financial health at a glance.
Looking For More Ideas Beyond Analog Devices?
Once you have a view on Analog Devices, it can help to pressure test your thinking against other opportunities with different income profiles, risk levels and balance sheet strength using the Simply Wall St Screener.
- For readers who care most about dependable income, scan companies that combine higher yields with robust fundamentals through the 5 dividend fortresses.
- If capital preservation and steadier price moves matter more to you than headline growth stories, filter for businesses with stronger downside resilience using the 30 resilient stocks with low risk scores.
- When you want to widen the search to lesser-known opportunities with solid financial quality, run a screen for under-the-radar prospects through the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com