


EN
Raised Guidance Might Change The Case For Investing In Ensign Group Stock (ENSG)
- Ensign Group reported Q3 2026 diluted earnings per share from continuing operations of US$1.76, up from US$1.42 a year earlier, and raised full year 2026 diluted EPS guidance to a range of US$7.94 to US$8.02 with updated revenue guidance of US$5.89b to US$5.92b.
- The higher guidance comes as Ensign Group focuses on higher occupancy, a richer skilled nursing mix and newly acquired turnaround facilities. Together, these factors place execution quality and integration speed at the center of the investment story.
- This article will examine how Ensign Group's raised full year earnings guidance affects the investment narrative around acquisitions and operating execution.
Compare Ensign Group's execution-led story with a curated set of operators that also pair solid earnings power with resilient balance sheets in our list of solid balance sheet and fundamentals (25 results).
Ensign Group Investment Narrative Recap
To own Ensign Group, investors need to be comfortable with a story built on steadily improving operations in skilled nursing, efficient use of acquired facilities and tight control of staffing. The raised 2026 EPS and revenue guidance indicates that management currently sees enough traction in occupancy, skilled mix and new sites to support a higher near term earnings bar.
The main short term swing factor is how quickly recently acquired, lower occupancy facilities, including the new Florida properties, move toward more normal census and margins. The biggest risk sits on the reimbursement and regulatory side. Any less favorable Medicare or Medicaid trends could offset operational gains and limit earnings power.
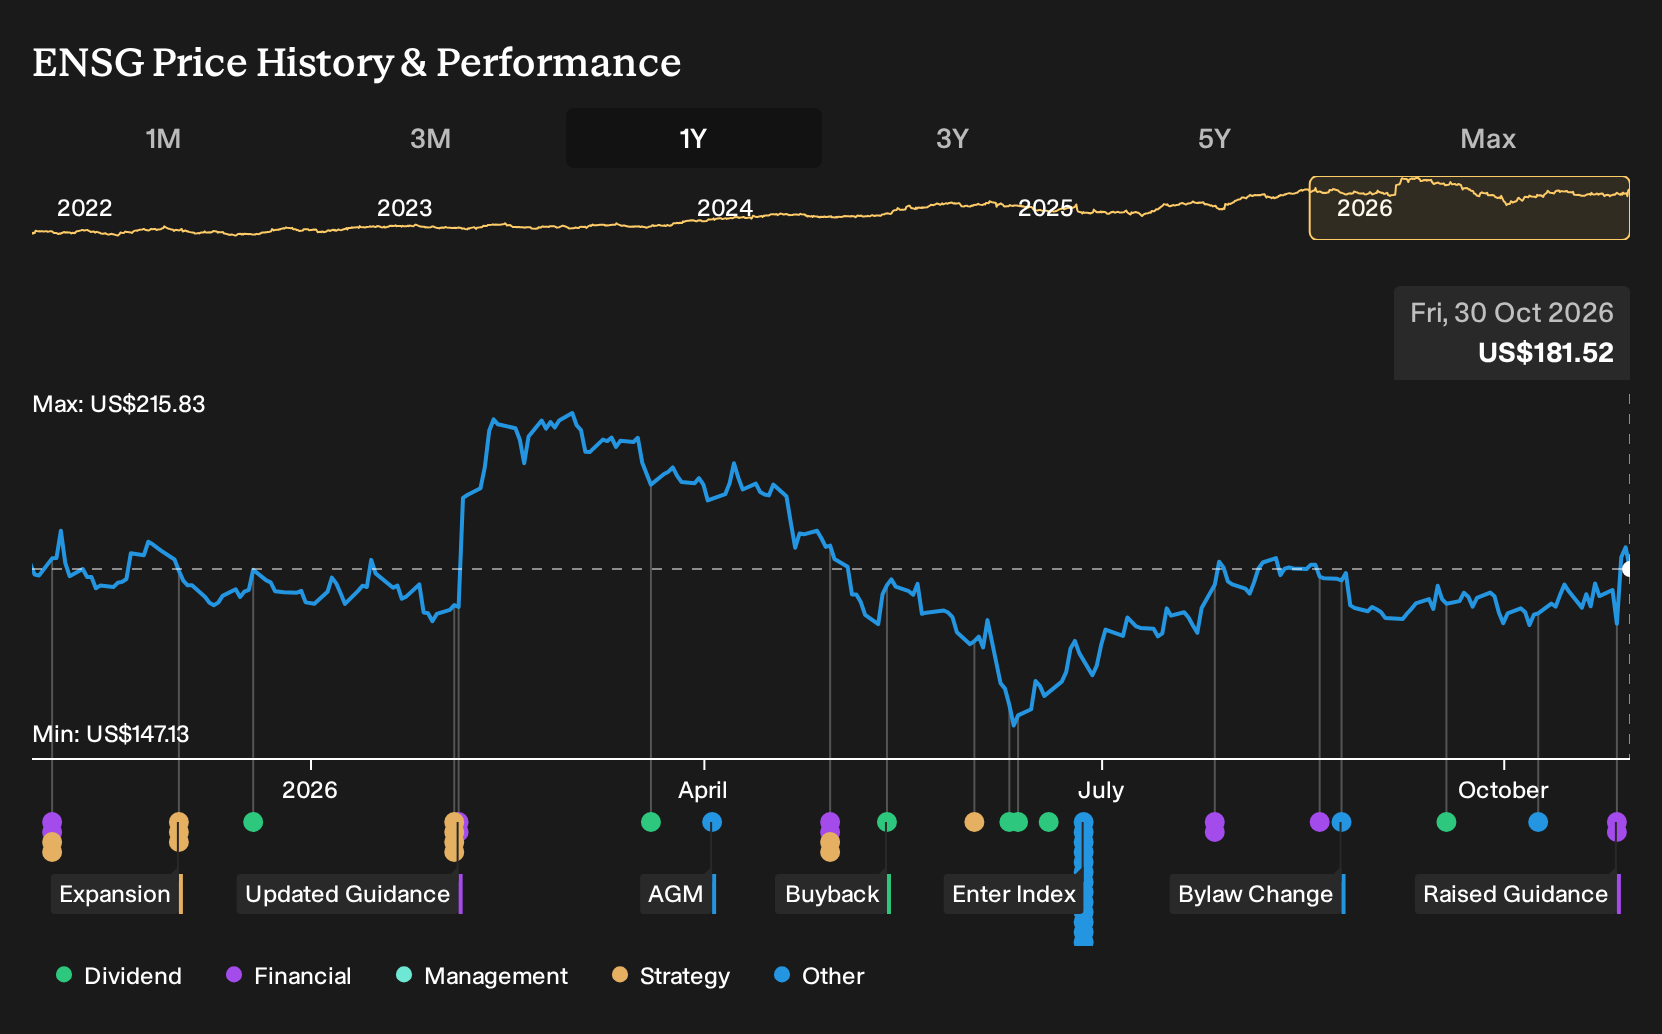
The key announcement is the October 27 update, where Ensign Group lifted 2026 diluted EPS guidance to US$7.94 to US$8.02 and nudged revenue expectations to US$5.89 billion to US$5.92 billion. That revision rests on the current run rate of occupancy, skilled nursing mix and contribution from the 22 facilities added this year.
For investors, that same guidance hike highlights execution risk. Many of the newer operations are turnarounds, especially in Florida, and management has acknowledged they may take time before materially helping earnings. Any slowdown in integration, staffing or quality scores would likely show up quickly against the tighter EPS range now on the table.
What The Long Term Consensus Implies For Ensign Group
Ensign Group's longer term analyst models lean on a few clear assumptions. Revenue is projected to rise at 10.9% a year over the next three years, helped by higher occupancy, skilled mix and the incremental contribution from newly acquired operations. On current estimates, earnings today sit at US$378.7 million and are expected to reach US$565.1 million by 2029. This implies an increase of about US$186 million over that period if the profit margin expands from 6.9% to 7.5% as forecast.
Ensign Group's narrative projects US$7.5 billion in revenue and US$565.1 million in earnings by 2029. This assumes 10.9% yearly revenue growth and about US$186 million earnings increase from US$378.7 million today.
Uncover why Ensign Group's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Three fair value estimates from the Simply Wall St Community cluster between about US$175.86 and US$223.60, which is a tight but meaningful spread for Ensign Group. Those views sit alongside fresh guidance and active acquisitions that could amplify reimbursement or integration risks. Investor opinions clearly vary, so explore several angles before forming a view.
Explore 2 other Ensign Group fair value estimates, including one that suggests it could be worth just $175.85.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ensign Group research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Ensign Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ensign Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Ensign Group?
If you like Ensign Group's execution story but want a broader watchlist, it helps to scan for other businesses with the traits you care about most, whether that is value, income or balance sheet resilience.
- For investors hunting for underappreciated opportunities with solid fundamentals, start by checking out 29 high quality undervalued stocks that fit a similar quality profile.
- If dependable income is a key part of your plan, focus on companies with stronger yields by reviewing 5 dividend fortresses that might complement a healthcare operator like Ensign Group.
- For a more defensive approach, concentrate on financially robust operators and review a 30 resilient stocks with low risk scores that can sit alongside higher execution stories in your portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com