


EN
Will Upcoming Results Change STERIS (STE) Stock Narrative
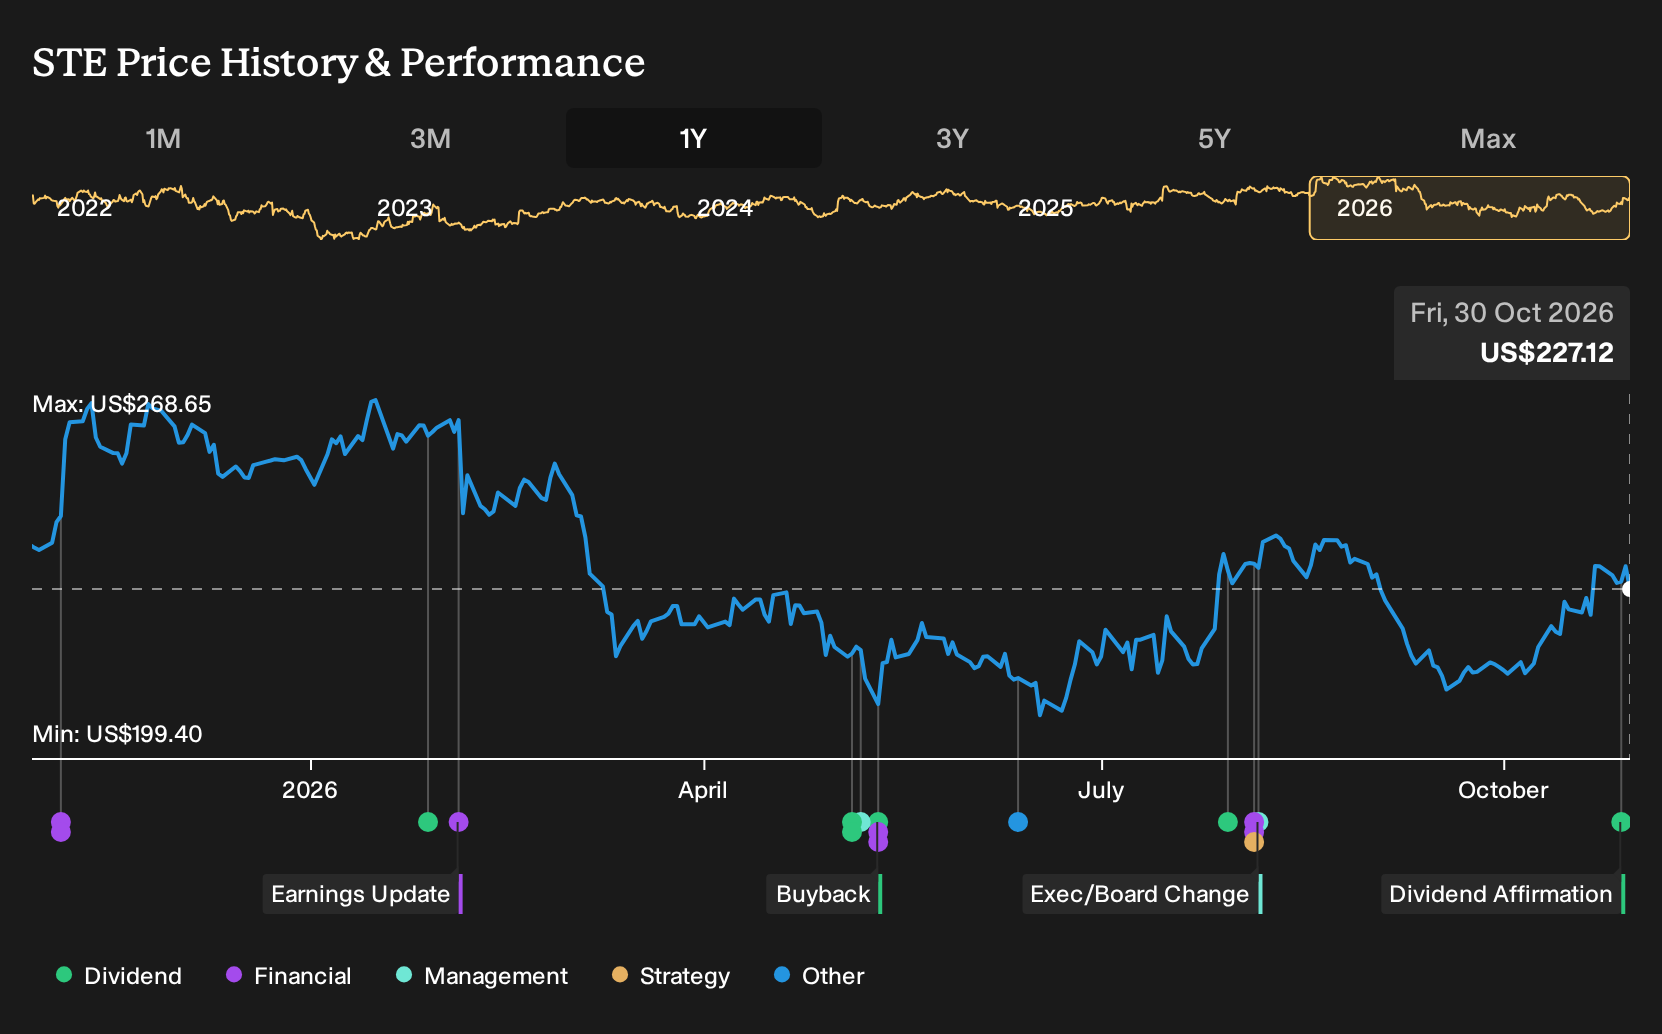
- STERIS plc has affirmed a quarterly dividend of US$0.69 per share, payable on December 17, 2026 to shareholders of record on November 17, 2026, alongside upcoming second quarter fiscal 2027 results.
- The confirmed cash payout, together with expectations for operational progress in the Healthcare segment and recent acquisitions, keeps attention on how STERIS balances investment needs with ongoing shareholder returns.
- The next key area of focus is how STERIS's upcoming second quarter fiscal 2027 results could influence the broader investment narrative.
STERIS Investment Narrative Recap
To own STERIS, you need to be comfortable with a healthcare equipment and services group that leans heavily on recurring chemistries and sterilization support, and is investing in large facilities for future volume. The investment case rests on procedure driven demand holding up and those chemistries and services continuing to support earnings.
The upcoming second quarter fiscal 2027 release looks like the main near term catalyst, because it will update how pricing, tariffs and inflation are flowing through margins. The biggest near term risk sits in execution on the North Carolina chemistries project and related restructuring, which could weigh on free cash flow if there are delays or cost overruns.
The fresh US$0.69 per share quarterly dividend affirmation is the announcement that really ties this story together. When paired with expectations for ongoing Healthcare segment progress and contributions from recent acquisitions, it keeps attention on how STERIS funds capital projects while still returning cash to shareholders.
For you as an investor, the key question is whether that dividend fits comfortably alongside tariff costs, restructuring charges and higher capital expenditure for new facilities. If upcoming results show that recurring chemistries and services are supporting margins and cash generation, the dividend rhythm may help frame how resilient the overall STERIS thesis feels through fiscal 2027.
STERIS' story centers on analysts forecasting US$7.3b in revenue and US$1.2b in earnings by 2029, based on an assumed 6.6% yearly revenue growth rate and a move in profit from US$805.0m in earnings today to the US$1.2b consensus, which implies an earnings increase of about 49% over that period.
Uncover why STERIS' fair value indicates a 16% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$216 to US$263 per share, which shows how far apart retail views on STERIS can land. Those opinions were formed before the latest dividend affirmation and before the upcoming second quarter fiscal 2027 release, so fresh numbers could quickly reshape the story.
Explore another STERIS fair value estimate, including one that suggests potential upside of as much as 16% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your STERIS research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for STERIS. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate STERIS' overall financial health at a glance.
Looking for more investment ideas beyond STERIS?
Once you have a view on STERIS, it can help to widen the lens and compare it with other businesses that fit different risk and income profiles. The Simply Wall St Screener gives you a way to scan for companies that match the kind of balance sheet strength, valuation, or income profile you want to focus on next.
- If you care most about capital strength and resilience, start with a 30 resilient stocks with low risk scores that could help anchor a more defensive section of your portfolio.
- For investors hunting for quality at a reasonable price, you can zero in on a 29 high quality undervalued stocks that pass a mix of cash flow and balance sheet checks.
- If income is a priority, use the tool to surface 5 dividend fortresses that might complement what STERIS offers on the payout front.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com