


EN
Should Raised Guidance Require Action From Extra Space Storage (EXR) Investors?
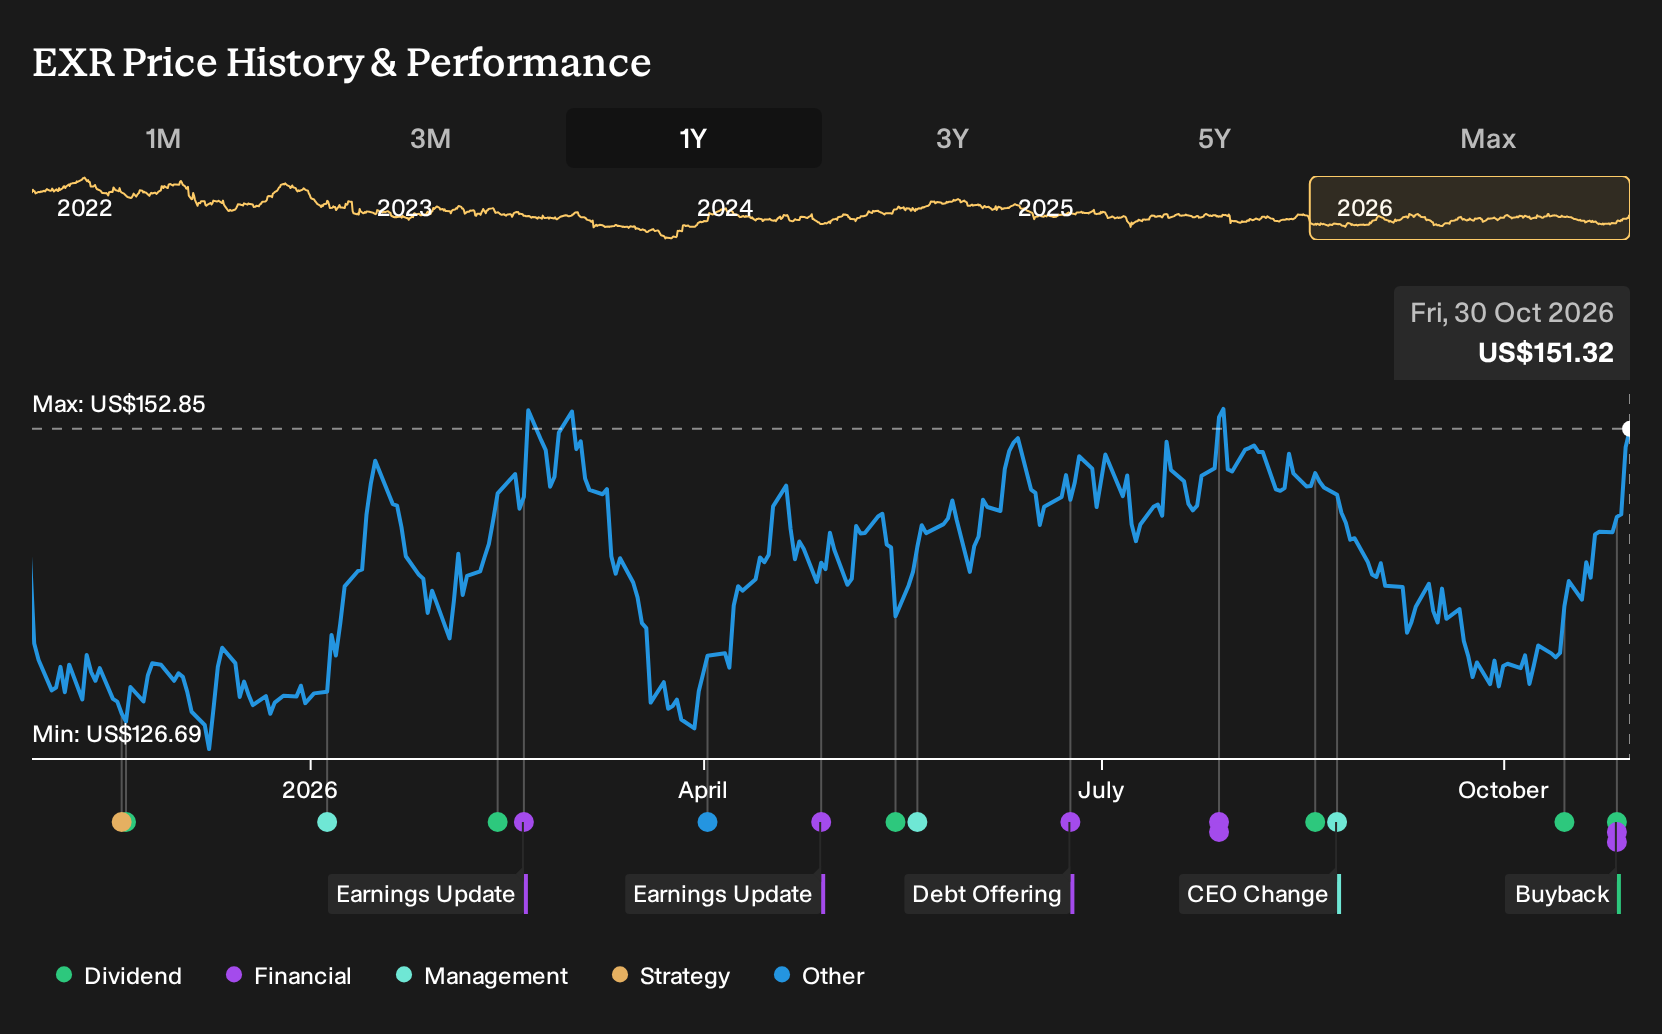
- Extra Space Storage reported solid Q3 2026 results, with higher sales, revenue and net income versus a year earlier, raised full year same store growth guidance, and confirmed a US$500 million share repurchase that has now been fully executed.
- Investors gained a clearer picture of Extra Space Storage's playbook as management paired cost control and same store NOI guidance upgrades with a CEO transition that signals continuity in the existing operating and growth approach.
- We will now look at how Extra Space Storage's investment narrative could be influenced by the stronger Q3 earnings and raised guidance.
Compare Extra Space Storage's earnings-driven story with other real estate and income-focused plays by scanning the hand picked 5 dividend fortresses that investors are watching after this update.
Extra Space Storage Investment Narrative Recap
To own Extra Space Storage, you need to be comfortable with a self storage REIT that leans heavily on steady occupancy, disciplined pricing technology and fee income from third party management. The Q3 update, with higher sales, revenue and net income versus a year earlier, plus firmer same store guidance, points to an operating backdrop that currently supports that thesis.
The near term swing factor is whether same store revenue and NOI hold up in softer markets like Houston, Tampa and Phoenix while acquisition cap rates stay tight. Raised guidance suggests near term pressure is not the dominant force right now. The main risk remains that elevated deal pricing or prolonged regional softness caps FFO progress.
The clearest announcement to focus on is the higher full year same store revenue and NOI guidance for 2026. Management now expects same store revenue growth of 2% to 2.5% and same store NOI growth of 2.5% to 3.5%. That guidance sits alongside Q3 same store revenue growth of 2.7% and same store NOI growth of 4.6%.
For investors, the link is straightforward. If Extra Space Storage can keep occupancy around the recent 94% level while its pricing systems and ancillary income continue to contribute, the upgraded outlook becomes an anchor for the near term story. If regional headwinds spread or acquisition returns weaken, that same store guidance range will likely be the first place to reflect the strain.
Extra Space Storage's current analyst narrative points to forecast revenue of US$3.3b and earnings of US$1.1b by 2029. These projections are built on an assumed yearly revenue decline of 2.3% and an earnings increase of about US$144m from current earnings of US$956.1m.
Uncover why Extra Space Storage's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Fair value estimates for Extra Space Storage from 2 private investors in the Simply Wall St Community cluster in a narrow band between US$158.50 and about US$171.88. That tight spread contrasts with risks around elevated acquisition pricing and regional softness. Use those differing views to compare your own expectations and explore alternative angles.
Explore another Extra Space Storage fair value estimate, including one that suggests it could be worth just $158.50.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Extra Space Storage research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Extra Space Storage. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Extra Space Storage's overall financial health at a glance.
Looking for more Extra Space Storage style ideas?
If the Extra Space Storage story has sharpened your thinking, you can widen the lens and test your income and quality filters across a broader set of opportunities using the Simply Wall St Screener.
- For readers hunting for strong balance sheets and resilient fundamentals, start with this curated list of solid balance sheet and fundamentals (25 results) that fit tighter quality checks.
- If value is the priority, benchmark Extra Space Storage against a focused group of 29 high quality undervalued stocks that combine quality metrics with compressed valuations.
- Income focused investors can broaden their watchlist by scanning a 5 dividend fortresses that currently clear a 5% yield hurdle while aiming for stability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com