


EN
We Think Camp4 Therapeutics (NASDAQ:CAMP) Can Afford To Drive Business Growth
There's no doubt that money can be made by owning shares of unprofitable businesses. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. But the harsh reality is that very many loss making companies burn through all their cash and go bankrupt.
So, the natural question for Camp4 Therapeutics (NASDAQ:CAMP) shareholders is whether they should be concerned by its rate of cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Camp4 Therapeutics Run Out Of Money?
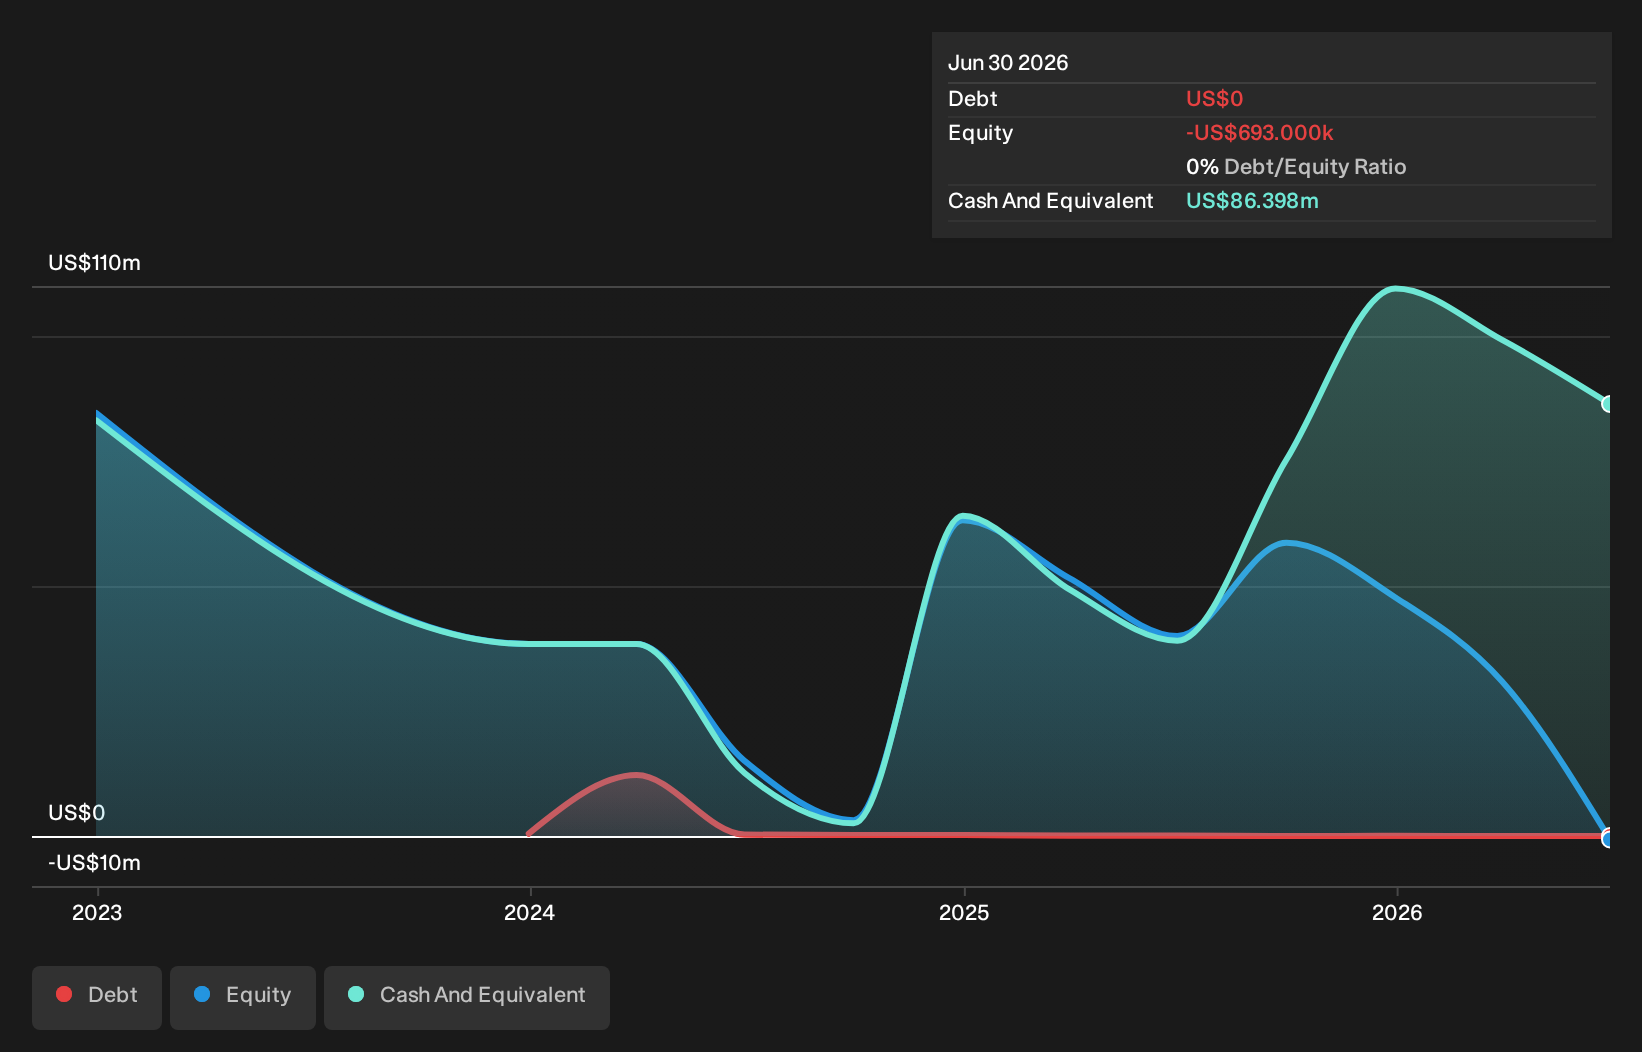
A company's cash runway is calculated by dividing its cash hoard by its cash burn. In June 2026, Camp4 Therapeutics had US$86m in cash, and was debt-free. In the last year, its cash burn was US$29m. Therefore, from June 2026 it had 3.0 years of cash runway. There's no doubt that this is a reassuringly long runway. You can see how its cash balance has changed over time in the image below.
View our latest analysis for Camp4 Therapeutics
How Well Is Camp4 Therapeutics Growing?
We reckon the fact that Camp4 Therapeutics managed to shrink its cash burn by 38% over the last year is rather encouraging. And considering that its operating revenue gained 40% during that period, that's great to see. We think it is growing rather well, upon reflection. While the past is always worth studying, it is the future that matters most of all. So you might want to take a peek at how much the company is expected to grow in the next few years.
Can Camp4 Therapeutics Raise More Cash Easily?
While Camp4 Therapeutics seems to be in a decent position, we reckon it is still worth thinking about how easily it could raise more cash, if that proved desirable. Issuing new shares, or taking on debt, are the most common ways for a listed company to raise more money for its business. Commonly, a business will sell new shares in itself to raise cash and drive growth. By comparing a company's annual cash burn to its total market capitalisation, we can estimate roughly how many shares it would have to issue in order to run the company for another year (at the same burn rate).
Camp4 Therapeutics' cash burn of US$29m is about 12% of its US$245m market capitalisation. As a result, we'd venture that the company could raise more cash for growth without much trouble, albeit at the cost of some dilution.
Is Camp4 Therapeutics' Cash Burn A Worry?
It may already be apparent to you that we're relatively comfortable with the way Camp4 Therapeutics is burning through its cash. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. Its cash burn relative to its market cap wasn't quite as good, but was still rather encouraging! After taking into account the various metrics mentioned in this report, we're pretty comfortable with how the company is spending its cash, as it seems on track to meet its needs over the medium term. On another note, Camp4 Therapeutics has 6 warning signs (and 3 which shouldn't be ignored) we think you should know about.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.