


EN
Is Wyndham Hotels & Resorts (WH) Undervalued As Homes And Havens Expands Its Rewards Reach?
Wyndham Hotels & Resorts (WH) has just reshaped its loyalty pitch with the launch of Homes & Havens, adding nearly 800 vacation rentals where members can earn and redeem Wyndham Rewards points.
Recent moves in Wyndham Hotels & Resorts’ loyalty offering come after a fairly muted stretch for the shares, with a 30 day share price return of 4.68% and a 1 year total shareholder return of 4.74% suggesting only modest momentum building around the story.
Spot opportunities around Wyndham Hotels & Resorts by scanning a curated set of travel and leisure players with resilient fundamentals using the list of solid balance sheet and fundamentals (25 results).Bulls see Homes & Havens as fresh fuel for Wyndham Hotels & Resorts’ fee engine, while bears see a loyalty tweak that leaves earnings flat. Which story fits the current valuation set up?
Most Popular Narrative: 23% Undervalued
Wyndham Hotels & Resorts is trading at $75.20 against a narrative fair value of about $97.59, which frames Homes & Havens inside a broader context of fee-heavy rooms, technology rollouts, and loyalty income doing the heavy lifting over time.
Record net room growth and a development pipeline of about 261,000 rooms with roughly a 30% FeePAR premium over the current system create ongoing mix uplift toward higher fee hotels, which can support faster growth in fee-related revenue and EBITDA for Wyndham Hotels & Resorts.
See why 2 investors see Wyndham Hotels & Resorts as 23% undervalued.
Result: Fair Value of $97.59 (UNDERVALUED)
Still, the Wyndham Hotels & Resorts story can crack if U.S. RevPAR softens for longer, or if legal and reputational issues around trafficking allegations escalate.
Find out about the key risks to this Wyndham Hotels & Resorts narrative.
Another View: What The P/E Says About Wyndham Hotels & Resorts
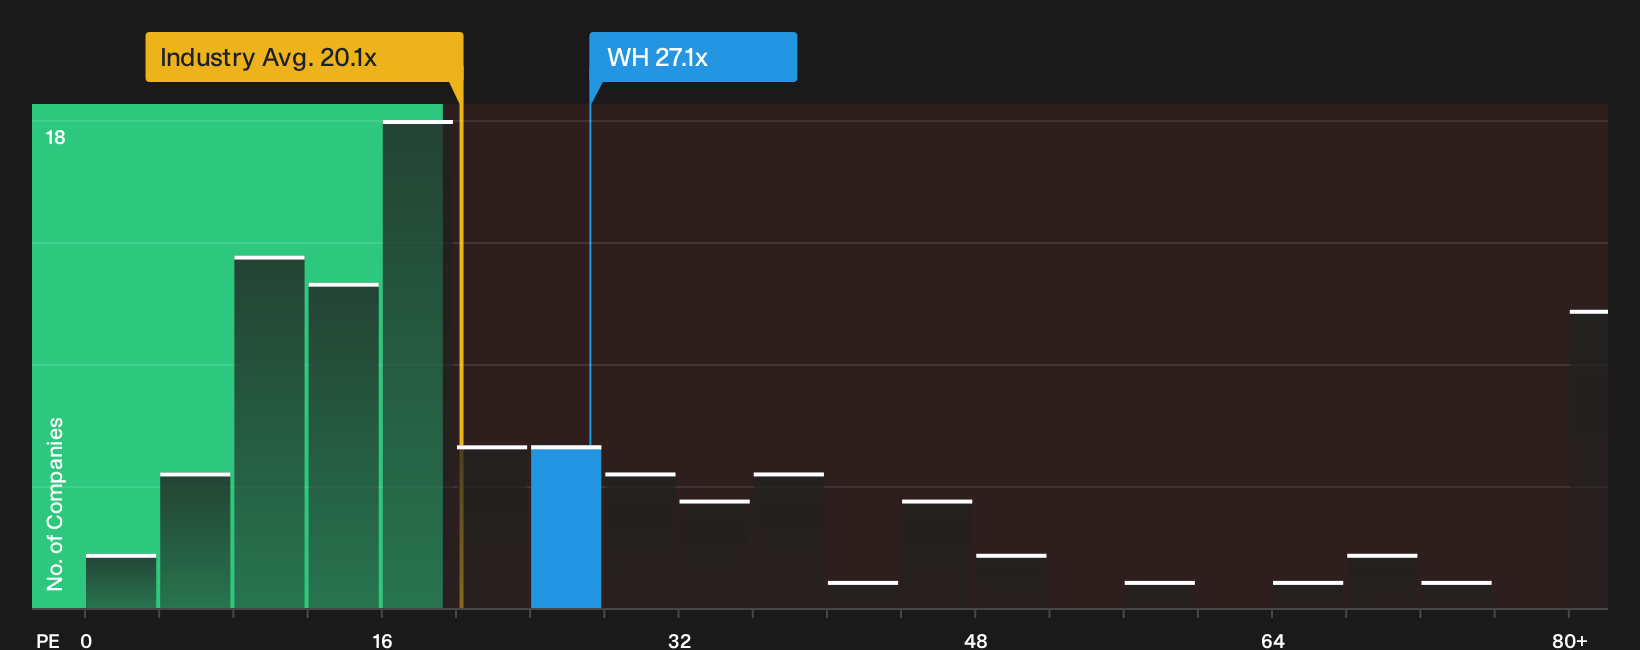
The narrative fair value paints Wyndham Hotels & Resorts as undervalued, yet the plain P/E math points in the opposite direction. At 27.1x earnings, the stock trades well above the US Hospitality sector on 20.7x and also above its own fair ratio of 21.5x, even though it sits below a 34.9x peer average. That gap suggests investors are already paying a premium for the fee-based story, which raises a simple question: Is the current price giving you enough margin for error if the growth narrative cools?
See what the numbers say about this price in more detail by reviewing See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Wyndham Hotels & Resorts can either indicate a warning or present an opening, so move quickly, review the data, and weigh the 3 key rewards and 4 important warning signs
Looking for more ideas beyond Wyndham Hotels & Resorts?
If Wyndham Hotels & Resorts raises fresh questions, broaden your watchlist and pressure test your thesis by comparing it with other opportunities on the Simply Wall Street Screener.
- Target resilience by scanning a curated set of companies with sturdy financial footing using the 30 resilient stocks with low risk scores.
- Hunt for mispriced quality and see which businesses look compelling on fundamentals through the 18 high quality undiscovered gems.
- Zero in on potential value candidates that pair solid operations with attractive pricing using the 29 high quality undervalued stocks.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com