


EN
Meritage Homes (MTH) After Soft Q3 Results Is The Stock Fully Valued
Meritage Homes (MTH) just posted softer third quarter numbers, with revenue, earnings and sales orders all declining as higher mortgage rates pressured buyer affordability and pushed management toward a more defensive playbook.
At around US$64.47, Meritage Homes has seen its short term share price momentum cool, with the 90 day share price return down 8.16%, while the 5 year total shareholder return of 22.88% points to a much steadier longer run outcome despite the recent earnings disappointment.
Scan how Meritage Homes compares with other builders under pressure from higher mortgage costs by reviewing the hand picked list of solid balance sheet and fundamentals (25 results).
Meritage Homes now trades below recent levels after softer orders and earnings. For investors considering housing exposure, is this post-result reset already enough compensation for the risks, or is patience on entry price still the better ally?
Most Popular Narrative: 9% Overvalued
Meritage Homes closed at $64.47 while the most followed narrative pegs fair value near $59. The story being told is that the current price already bakes in more optimism than the bearish camp is comfortable with, especially given softer housing demand and margin pressure.
The numbers imply the share price already reflects a fairly valued, bullish outcome in which Meritage Homes sustains solid community growth, maintains an investment-grade balance sheet, and continues returning substantial capital to shareholders despite current earnings pressure.
See why 1 investors see Meritage Homes as 9% overvalued.
Result: Fair Value of $59 (OVERVALUED)
Still, if the 21st Century ROAD to Housing Act meaningfully trims build friction and Meritage Homes continues to emphasize its ENERGY STAR reputation, demand could differ from this cautious script.
Find out about the key risks to this Meritage Homes narrative.
Another View: Meritage Homes Through The P/E Lens
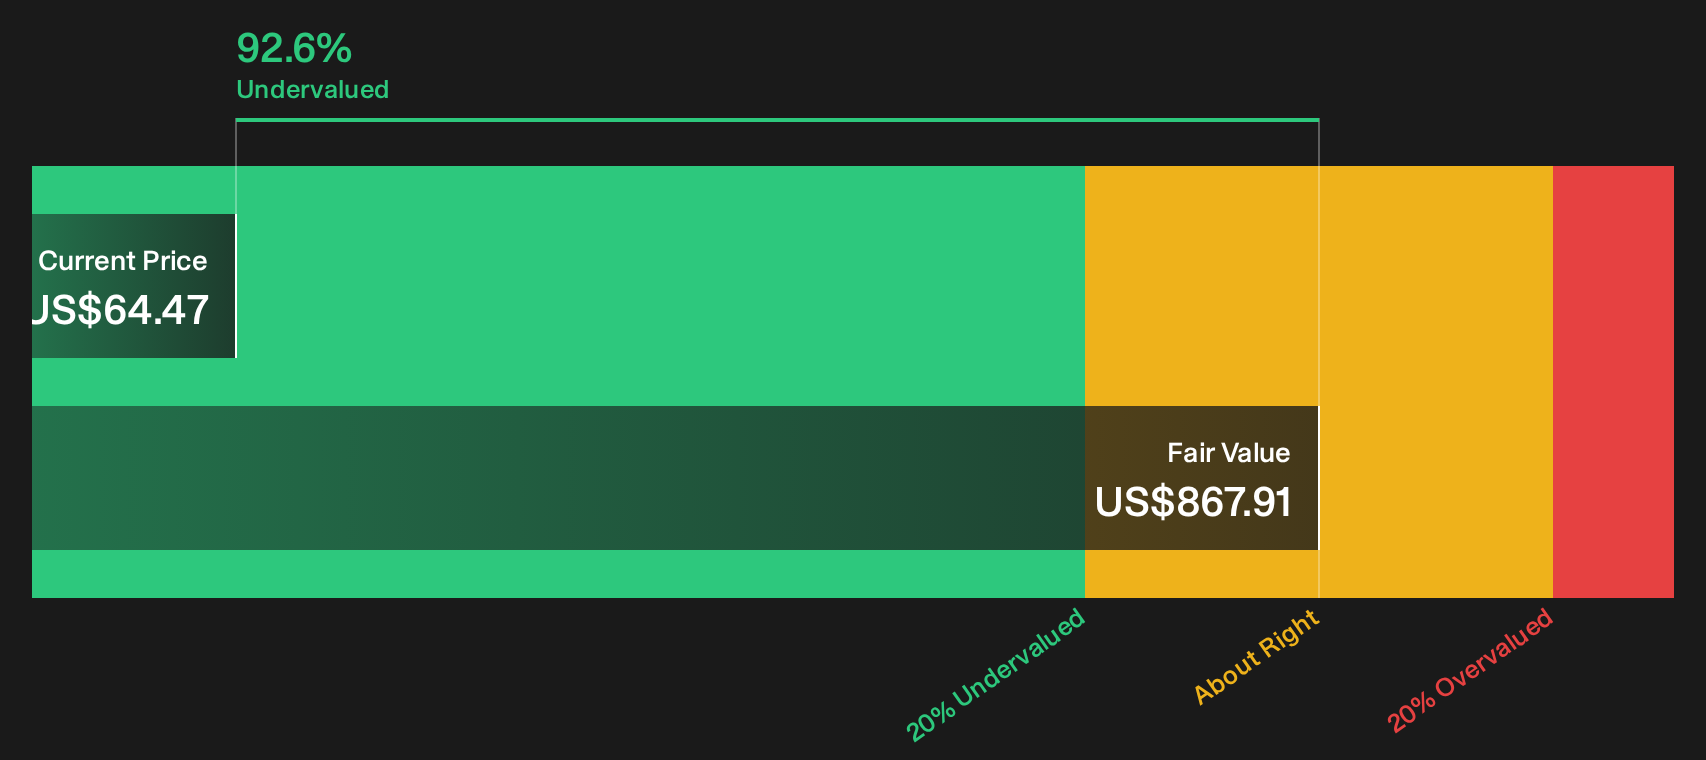
The SWS DCF model flags Meritage Homes as materially undervalued, with an estimated future cash flow value of $867.91 against a share price of $64.47. By contrast, the market P/E of 13.9x sits just above the US Consumer Durables average of 13.7x and below the 17x fair ratio the model suggests the multiple could move toward, which points to meaningful valuation upside if those earnings assumptions hold. The question is whether you trust the cash flow model or the more cautious earnings multiple that investors are actually paying for today.
For a closer look at how this cash flow view is built, and how sensitive it is to the inputs that matter most, Look into how the SWS DCF model arrives at its fair value.
Next Steps
With mixed signals around Meritage Homes, you do not need to wait for consensus to form before checking the numbers yourself and weighing the trade off between weaker orders and potential upside. To see how the positives and pressure points stack up in one place, review the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Meritage Homes?
If Meritage Homes has your attention, do not stop there. Broaden your watchlist with a few targeted idea lists that surface different types of opportunities.
- Target resilient potential compounders by scanning a 29 high quality undervalued stocks that filters for quality fundamentals at prices that still look reasonable.
- Lock in income focused ideas through a curated set of high yield payers using the 5 dividend fortresses before the next round of payouts approaches.
- Protect your capital first and hunt for consistency second by reviewing a 30 resilient stocks with low risk scores designed to prioritize sturdier balance sheets and steadier performance.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com