


EN
First Bancorp (FBNC) Posts Stronger Q3 Results, Is The Valuation Already Rich?
First Bancorp (FBNC) just posted third quarter 2026 results that highlight higher net interest income and net income for investors, along with a relatively small US$2.1 million in net charge-offs.
The stronger third quarter showing lands on a stock that has already been on a solid run. First Bancorp’s year to date share price return of 24.93% and 1 year total shareholder return of 33.19% have been supported by improving earnings updates and only modest recent pullbacks.
Scan beyond First Bancorp’s strong quarter and see how other banks with resilient earnings quality line up across our hand picked 30 resilient stocks with low risk scores.
First Bancorp’s strong earnings and double digit returns raise a simple tension. Is the recent climb mainly about a healthier banking franchise, or a mood shift around the stock as it approaches valuation estimates?
Preferred P/E Of 16.1x For First Bancorp: Is It Justified?
First Bancorp now trades on a P/E of 16.1x, which sits above both the US banks industry average of 11.4x and its closest peer set at 12.1x. That premium attaches to a share price of $63.6 despite earnings forecasts that are not flagged as significantly higher than the broader US market.
The P/E ratio compares what investors are paying for each dollar of earnings and is a common yardstick for banks that already earn steady profits. For a lender like First Bancorp, this measure links directly to expectations around future earnings quality, loan growth, and the sustainability of its 36.1% net margin.
At 16.1x, the market is paying materially more for First Bancorp earnings than for the typical US bank. The SWS fair P/E estimate of 13.2x sits well below the current ratio. This indicates that the prevailing price level appears rich relative to the modelled fair multiple the market could gravitate toward over time.
Explore the SWS fair ratio for First Bancorp.
Result: Price-to-Earnings of 16.1x (OVERVALUED)
Still, a richer P/E for First Bancorp can quickly look fragile if credit costs rise from current levels, or if loan demand softens and limits earnings power.
Find out about the key risks to this First Bancorp narrative.
Another View On First Bancorp’s Valuation
The P/E looks stretched, but the SWS DCF model points in the opposite direction. At $63.6, First Bancorp trades at a 36.6% discount to an estimated future cash flow value of $100.38. That suggests investors are either being cautious or missing something. Which side are you on?
Look into how the SWS DCF model arrives at its fair value.
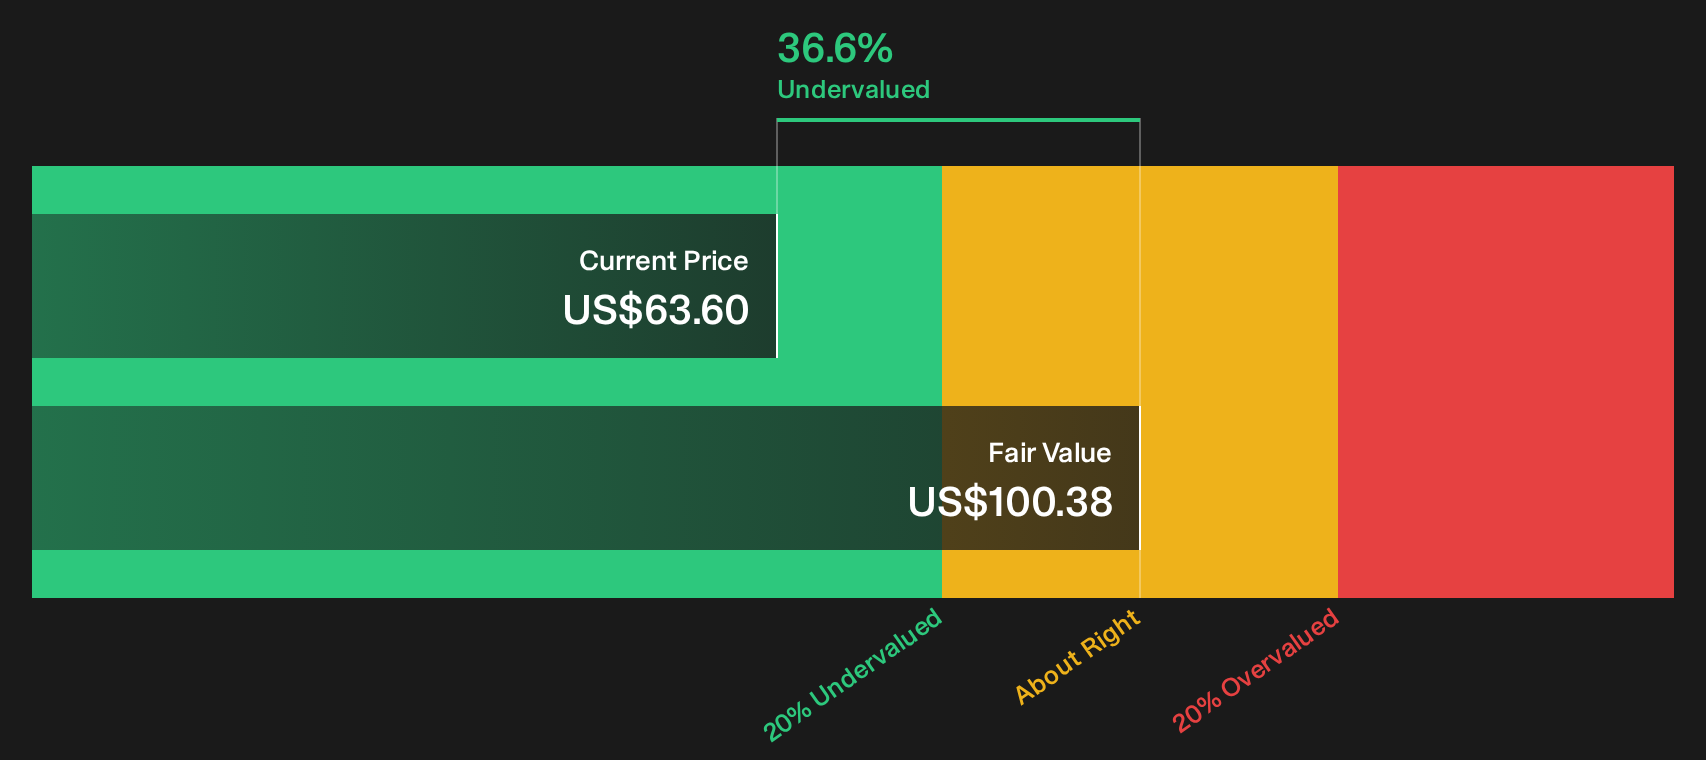
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out First Bancorp for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on First Bancorp’s value case so far. If you want to move past the headline metrics and timing anxiety, consider the full picture by checking the 4 key rewards and 1 important warning sign.
Hunting For Your Next Idea Beyond First Bancorp?
If First Bancorp has caught your attention, do not stop here. Use Simply Wall Street’s screener to quickly surface fresh ideas that fit your risk and income goals.
- Target resilient balance sheets and steady fundamentals by scanning our list of solid balance sheet and fundamentals (25 results).
- Hunt for mispriced opportunities by running a filter across 29 high quality undervalued stocks.
- Build a cash flow focused portfolio by zeroing in on income ideas within 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com