


EN
Earnings Beat Could Reset The Case For Flex Stock
- Flex reported fiscal Q2 2027 sales of US$8.49b and net income of US$263m, with higher diluted EPS from continuing operations than a year earlier, and raised full year 2027 net sales guidance to a range of US$34.9b to US$35.9b.
- The Cloud and Power Infrastructure segment, supported by AI and data center demand and slated for a future spin off as Axiom, is emerging as a key earnings engine within Flex's broader manufacturing and services portfolio.
- We will look at how Flex's investment narrative aligns with these stronger AI driven infrastructure results and the raised full year guidance.
Scan beyond Flex and its Axiom spin off story to spot other AI infrastructure beneficiaries in our hand picked 54 AI infrastructure stocks.
Flex Investment Narrative Recap
To own Flex, you need to be comfortable with a story built around AI driven infrastructure demand, heavier capital spending and the Axiom spin off. The big swing factor near term is whether Cloud and Power Infrastructure keeps absorbing strong AI data center orders without major disruption from customer concentration. The latest quarter, with higher sales, net income and EPS from continuing operations, supports that operating backdrop.
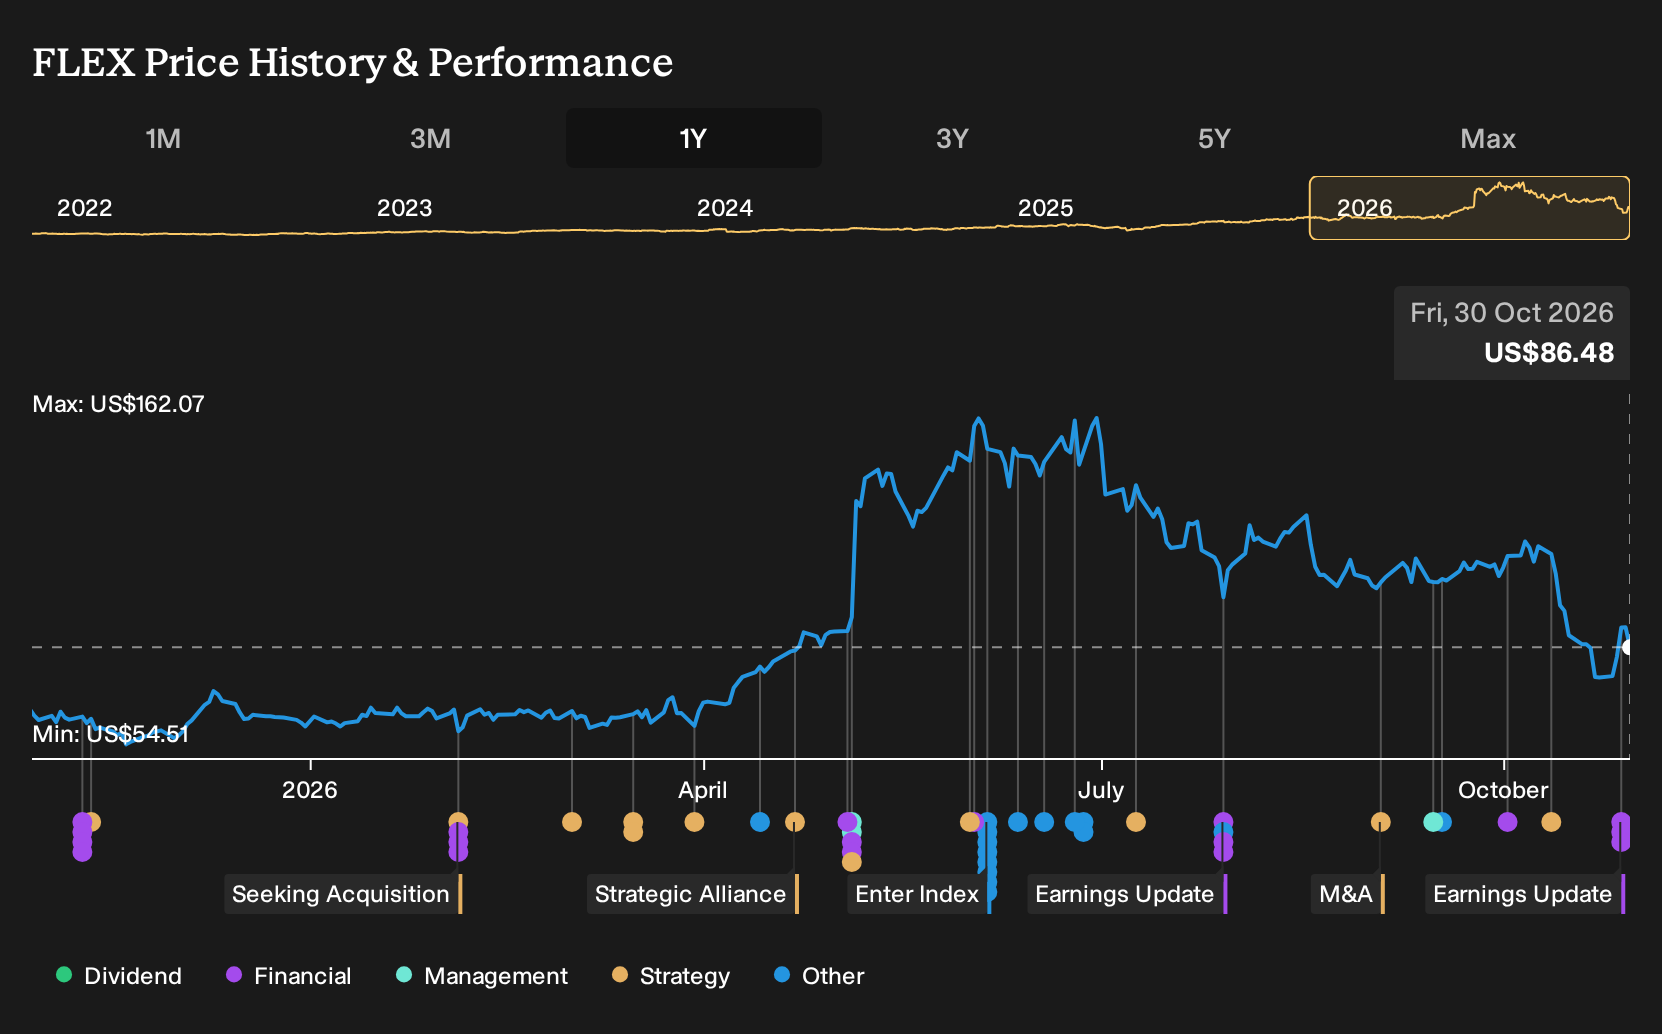
The main risk has barely changed. Flex is still tying a lot of its fortunes to a concentrated set of hyperscale and colocation customers while committing sizeable capex and spin related cash outflows. The share price drop after earnings shows how quickly sentiment can shift if investors worry that spending plans get ahead of dependable program wins and free cash flow.
The raised fiscal 2027 net sales outlook to US$34.9b to US$35.9b is the key announcement for this earnings print. Management signalled more revenue than previously guided, with Q2 figures already showing US$8.49b of sales and US$263m of net income. For you, the question is whether this updated range still feels grounded in AI power and cooling demand, rather than stretch.
That higher target keeps the spotlight firmly on execution in Cloud and Power Infrastructure and on the coming Axiom separation. It raises the stakes on two fronts. First, Flex needs AI data center projects to stay on track with existing customers. Second, it has to keep spin off costs, capital intensity and integration of EPC Power from squeezing the very cash flows investors want that higher revenue base to eventually support.
Flex's narrative connects analyst expectations to projected revenues of US$62.3b and earnings of US$5.2b by 2029. This implies forecast revenue growth of 26.3% per year and an earnings increase of about US$4.2b from current earnings of US$1.0b.
Uncover why Flex's fair value indicates an 81% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some bullish analysts frame the Axiom spin off as a potential upside surprise for you. They were already pencilling in about US$60.0b of revenue and US$4.4b of earnings by 2029, before this Flex guidance jump. You can treat this quarter as a fresh data point that might push those optimistic narratives to evolve.
Explore 5 other Flex fair value estimates, including one that suggests as much as 108% upside from the current price!
The Verdict Is Yours
Do not just follow the ticker; dig into the data and build a conviction that is truly your own.
- A great starting point for your Flex research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Flex. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Flex's overall financial health at a glance.
Looking For More Ideas Beyond Flex?
Once you have a view on Flex and the Axiom spin off story, it can help to compare that thesis with other opportunities that line up with your risk tolerance, income needs and time horizon.
- If you want potential mispricings with quality still front and center, scan our curated set of 29 high quality undervalued stocks that pair fundamentals with attractive pricing signals.
- For a focus on resilience and capital preservation, look through a 30 resilient stocks with low risk scores that aims to keep balance sheets and risk scores in tighter ranges.
- When you are hunting for under followed opportunities rather than the usual tickers, cast a wider net with a 18 high quality undiscovered gems that surfaces high quality businesses flying under many radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com