


EN
How Investors Are Reacting To Crown Castle (CCI) Raised 2026 Guidance
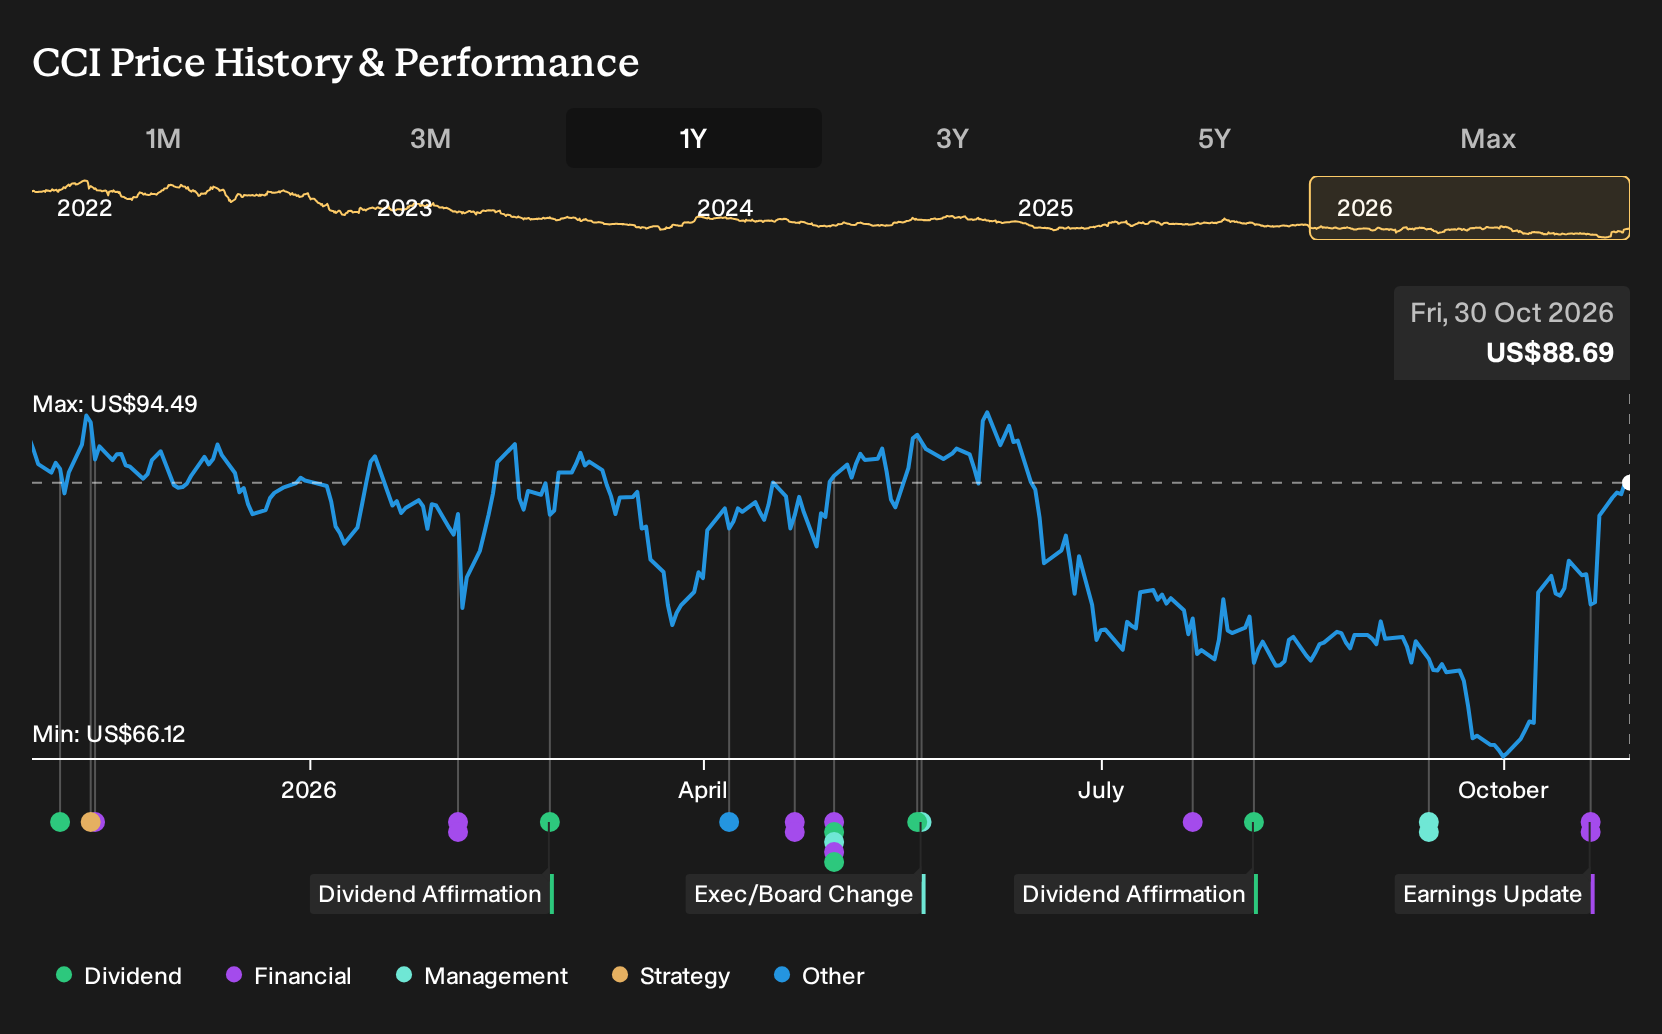
- Crown Castle reported Q3 2026 revenue of US$995 million and net income of US$283 million, then raised full year earnings guidance and widened its projected net income range.
- The tower owner is buying out ground leases and residual revenue interests on select sites to secure longer term rental cash flows and lower site level costs.
- This article examines how Crown Castle's tower focused investment narrative is influenced by the guidance upgrade tied to ground lease buyouts.
Scan how other tower and wireless infrastructure owners are positioned around similar cash flow stories by reviewing the hand picked 54 AI infrastructure stocks that could benefit from rising data and carrier demand.
Crown Castle Investment Narrative Recap
To own Crown Castle, you need to believe the pure tower REIT model can absorb churn from Sprint and DISH, rely on long leases and eventually turn modest revenue trends into healthier cash earnings. The Q3 2026 print showed lower revenue and net income than a year ago, yet still supported a guidance lift for full year profit.
The near term swing factor is whether cost actions and ground lease buyouts offset carrier churn and softer pre construction work. The biggest risk is that reduced services demand and lost tenant contracts keep weighing on tower level revenue, which would make it harder to support interest costs and the current dividend profile.
The raised 2026 net income guidance, with a midpoint of US$895 million and a wider range from US$755 million to US$1.035 billion, is the update that ties directly to the quarter. Management also nudged midpoint diluted EPS guidance from US$2.02 to US$2.08, which reflects confidence in earnings delivery despite lower year on year revenue.
That upgrade sits alongside the push to buy out ground leases and residual revenue interests on select sites. This initiative is aimed at lowering future site costs and firming up rental cash flows. For you as a shareholder, execution on those lease economics is a key catalyst, while any disappointment on churn, services activity or funding costs remains front and center as the main operational risk.
Crown Castle Consensus Targets And Implied Lift
Crown Castle's analyst narrative points to forecast revenue of US$4.3b and projected earnings of US$1.4b by 2029. That outlook assumes revenue growth of 1.3% per year, with earnings rising by about US$300m from US$1.1b today to the US$1.4b consensus level.
Uncover why Crown Castle's fair value identifies a 7% potential upside to its current price that may not last much longer.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$94.82 to about US$121.37 per share, so you are seeing a wide personal range even in a tiny sample. When you layer that against Crown Castle’s Sprint and DISH churn risk, tower focused capital plans, and potential SpaceX tower demand, you get sharply different performance storylines.
Explore another Crown Castle fair value estimate, including one that suggests there could be as much as 37% upside from the current price!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment results rarely come from following the herd, so trust your own research and judgment.
- A great starting point for your Crown Castle research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Crown Castle. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate Crown Castle's overall financial profile at a glance.
Looking For More Investment Ideas Beyond Crown Castle?
Once you have a working view on Crown Castle, it can help to widen the lens and compare it with other businesses that share similar quality, income, or risk profiles. The Simply Wall St Screener offers several focused stock shortlists that can give you a broader field of candidates to research next.
- If capital preservation is your top priority, start with a list focused on stability and lower risk profiles through the 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, put valuation front and center by reviewing the 29 high quality undervalued stocks.
- If you want to pair solid fundamentals with the possibility of under followed stories, broaden your watchlist using the 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com