


EN
How Investors May Respond To Church & Dwight Stock After Earnings Beat
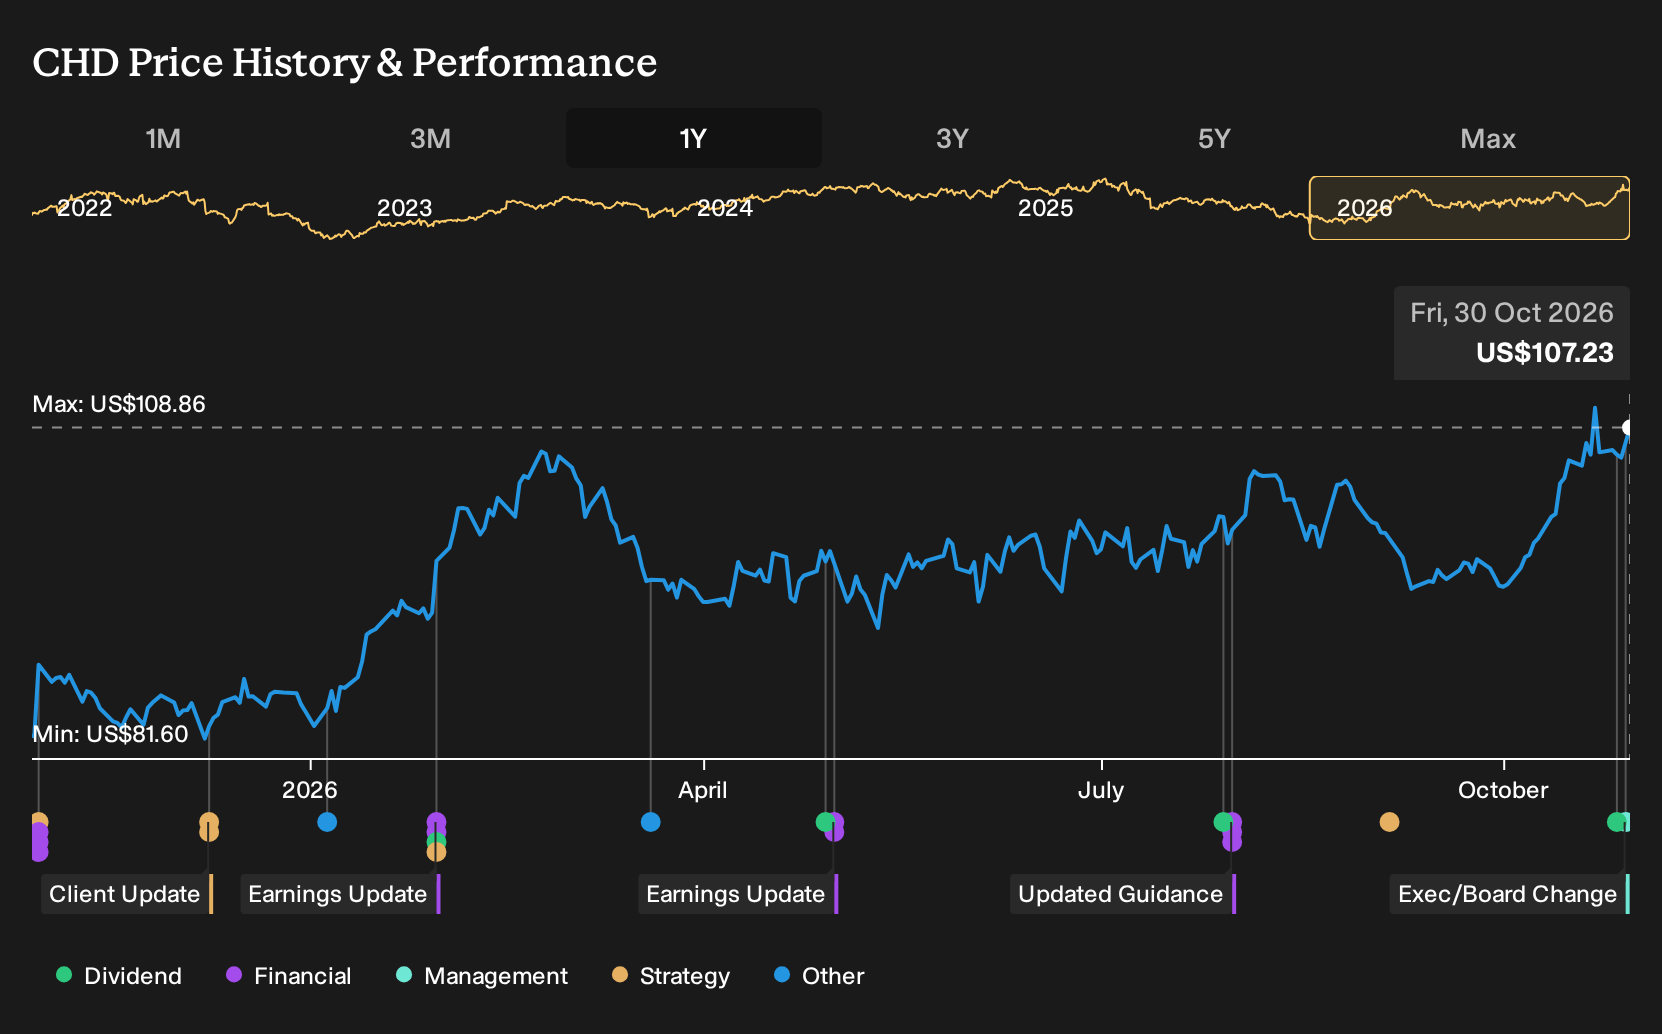
- Church & Dwight reported past third quarter 2026 sales of US$1,602.1 million and net income of US$212.2 million, alongside full year guidance that now points to roughly 0.5% net sales growth and about US$3.63 in EPS.
- The business paired this tighter outlook with a new US$1b share repurchase authorization and ongoing dividend payments, indicating a continued focus on cash generation, capital returns and portfolio reshaping after prior exits.
- This raises the question of how Church & Dwight's upgraded full year guidance could influence the broader investment narrative around the stock.
Scan how Church & Dwight's mix of earnings resilience, capital returns and modest top line guidance compares with other cash generative defensives in our hand picked 30 resilient stocks with low risk scores.
Church & Dwight Investment Narrative Recap
To own Church & Dwight, you need to be comfortable with a slow top line and a focus on margins, brands and cash generation. The latest quarter shows sales and earnings from continuing operations ahead of last year, while full year guidance now points to about 0.5% net sales growth and roughly US$3.63 in EPS.
The key short term catalyst is execution on higher margin brands and channels, despite flatish reported sales, supported by productivity and mix. The biggest risk remains drag from underperforming categories and higher SG&A after portfolio exits. On that front, the new outlook and Q3 delivery look supportive rather than game changing.
The most relevant update for this story is the new US$1b share repurchase authorization. It sits alongside ongoing dividends and together they signal that Church & Dwight expects solid cash generation while absorbing portfolio clean up and modest sales guidance around 0.5% growth for 2026.
For you as a shareholder, the buyback frames how capital returns interact with the main catalysts. Execution on e commerce, health and wellness brands and international rollouts needs to support earnings and cash flows for that program to run comfortably, particularly with higher SG&A and the vitamin gummy weakness still a live risk.
Church & Dwight's analyst narrative points to revenues of US$6.9b and earnings of US$997.4 million by 2029, based on revenue growth of about 3.4% a year and an earnings increase of roughly US$252.6 million from current earnings of US$744.8 million.
Uncover why Church & Dwight's fair value indicates a value that is roughly in line with its current price.
Exploring Other Perspectives
Some of the most optimistic analysts lean hard into Church & Dwight’s capital deployment story. Before this earnings print and the fresh US$1b buyback plan, they were pencilling in revenue of about US$7.0b and earnings of roughly US$1.1b by 2029. That is a much more upbeat take than consensus. You can compare today’s guidance with those prior assumptions and decide which perspective feels closer to your own view.
Explore 3 other Church & Dwight fair value estimates, including one that suggests as much as 24% potential increase from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Church & Dwight research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Church & Dwight. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Church & Dwight's overall financial health at a glance.
Looking For More Ideas Beyond Church & Dwight?
Once you have a handle on Church & Dwight's story, it can help to widen the lens and compare it with other businesses that fit different portfolio roles, from income generators to potential mispriced opportunities.
- If you want potential value opportunities with quality fundamentals, start by scanning our curated 29 high quality undervalued stocks that could complement a position like Church & Dwight.
- For investors who care most about resilience and capital preservation, it can be useful to compare Church & Dwight alongside a wider universe of 30 resilient stocks with low risk scores that score well on stability metrics.
- If income is your anchor, line up Church & Dwight next to a focused set of 5 dividend fortresses that offer higher yields and different payout profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com