


EN
Shanghai Junshi Biosciences Could Be 75% Below Fair Value As Losses Narrow
Shanghai Junshi Biosciences (SEHK:1877) just paired a new earnings update with fresh clinical news. Nine-month sales reached CNY 2,513.41 million, while the reported net loss narrowed to CNY 149.2 million.
Despite the fresh clinical updates and narrowing nine month loss, Shanghai Junshi Biosciences’ share price has come under pressure, with a 30 day share price return down 20.93% and a year to date share price return down 31.51% at HK$15.26. The longer view also reflects investor caution, with a 1 year total shareholder return down 42.59% and a 5 year total shareholder return down 62.09%. As a result, recent earnings and trial milestones are landing against a backdrop of fading momentum and reassessment of risk.
Spot under-pressure biopharma stories like Shanghai Junshi Biosciences and compare them with 125 healthcare AI stocks shaping the next wave of drug development.Shanghai Junshi Biosciences now trades at a steep discount to both analyst targets and intrinsic value estimates after this selloff. Is the market correctly pricing clinical and earnings risk, or has caution gone too far?
Preferred Price-to-Sales of 4.1x: Is it justified?
On Simply Wall St’s checks, Shanghai Junshi Biosciences screens as inexpensive on its preferred metric, with a P/S ratio of 4.1x while the share price sits at HK$15.26. That low multiple lines up with broader signals that the stock is trading well below various fair value markers.
The P/S ratio compares the market value of the equity to its revenue base, which is often a useful yardstick for loss making biopharma groups where earnings are still negative. For Shanghai Junshi Biosciences, investors are paying roughly 4.1 times recent sales, which reflects how the market is weighing the current product portfolio against the broader late stage pipeline.
Context matters. The business is assessed as good value versus its peer group. The 4.1x P/S sits below the Hong Kong Biotechs industry average of 7.8x and also below a peer average of 8.2x. The Simply Wall St fair ratio analysis points to an estimated “fair” P/S closer to 8.1x, a level the market could move towards if sentiment and fundamentals re align.
Explore the SWS fair ratio for Shanghai Junshi Biosciences.
Result: Price-to-Sales of 4.1x (UNDERVALUED)
Still, Shanghai Junshi Biosciences faces real pressure if late stage trials stumble or if ongoing net losses persist and require fresh equity funding at weaker prices.
Find out about the key risks to this Shanghai Junshi Biosciences narrative.
Another View: What the SWS DCF Model Says
The P/S check paints Shanghai Junshi Biosciences as cheap, but the SWS DCF model goes even further. On Simply Wall St’s estimate, the shares at HK$15.26 trade well below an implied future cash flow value of HK$60.99, which points to a very wide valuation gap.
A model is not a crystal ball. It does signal that a large part of future expectations is priced out of the stock, which can mean opportunity if forecasts prove realistic or prolonged disappointment if the pipeline and earnings story fall short. Which side of that equation do you believe?
Look into how the SWS DCF model arrives at its fair value.
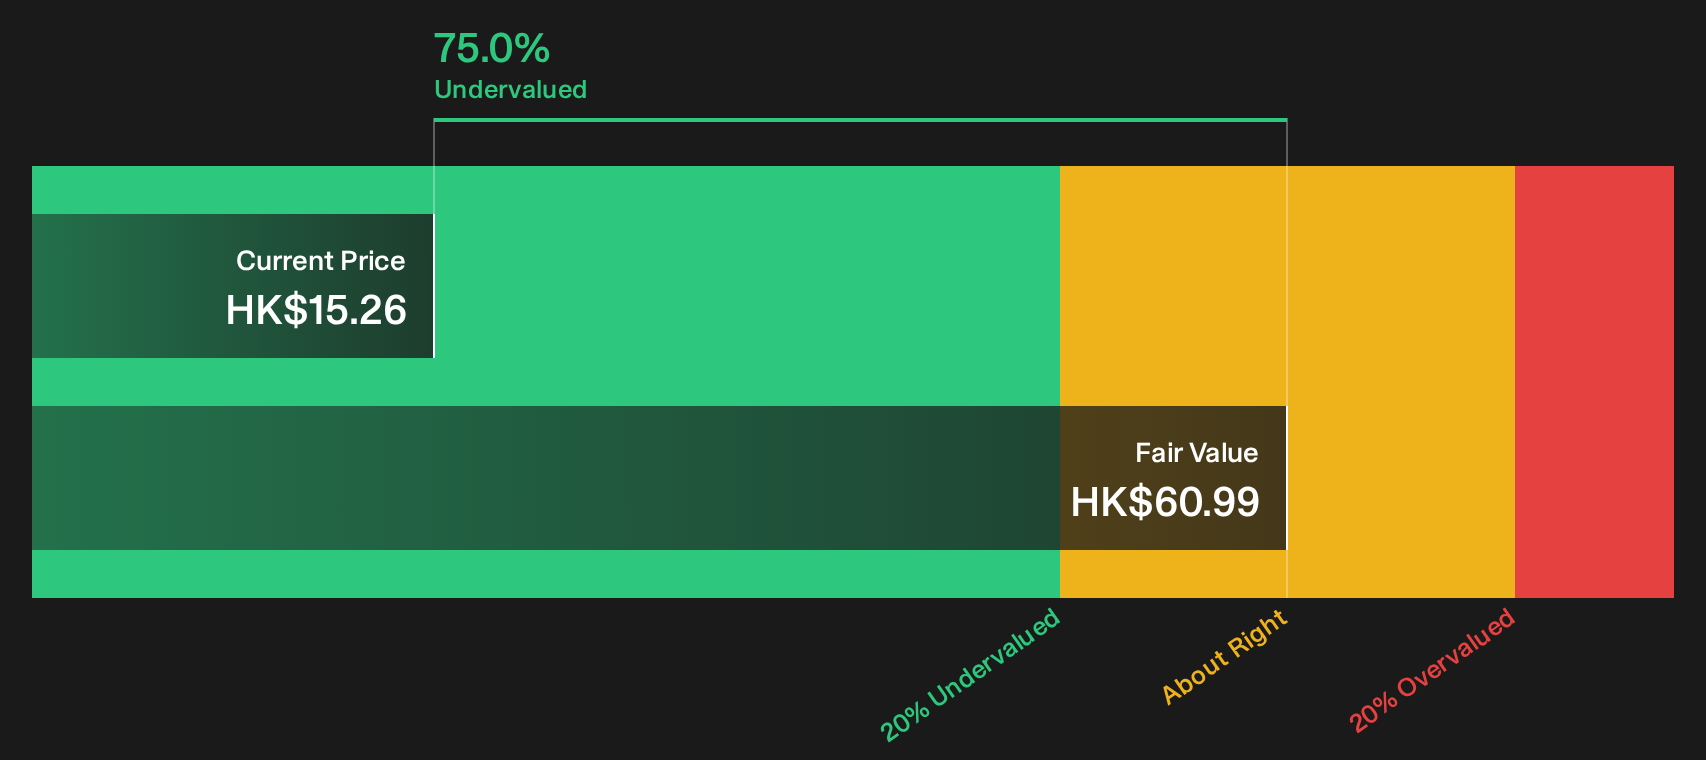
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Shanghai Junshi Biosciences for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 199 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Feeling torn between the discounts and the risks around Shanghai Junshi Biosciences is natural, especially with clinical outcomes and funding needs still in focus. Act while the data is fresh, stress test the numbers against your own expectations, then pressure test the upside case through the 4 key rewards
Looking for more ideas beyond Shanghai Junshi Biosciences?
When a single stock raises more questions than answers, casting a wider net can sharpen your thinking and reveal options you might otherwise miss.
- Hunt for mispriced quality and pressure test your value instincts with the 199 high quality undervalued stocks.
- Prioritise resilience and sleep easier by reviewing a list of solid balance sheet and fundamentals (203 results).
- Tap into underfollowed potential before the crowd notices through the 603 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com