


EN
Should PRAME Trial Update Require Action From Immatics (IMTX) Investors?
- Immatics reported updated Phase 1b and Phase 1 data at ESMO 2026 for its IMA402 bispecific and IMA203CD8 cell therapy programs targeting PRAME, showing manageable safety profiles and measurable anti tumor activity in heavily pretreated patients across multiple solid tumor types.
- The data highlight how Immatics is advancing two distinct PRAME targeted platforms, with both a bispecific antibody and a T cell therapy showing disease control in difficult melanoma and gynecologic cancer settings that had already exhausted several prior treatments.
- Attention now turns to how the PRAME focused IMA402 and IMA203CD8 results could shape the broader investment narrative for Immatics.
What Is Immatics' Investment Narrative?
To own Immatics, you need to believe its focused bet on PRAME can translate early clinical signals into a real therapeutic franchise. The fresh ESMO 2026 readouts on IMA402 and IMA203CD8 speak directly to execution. Management is showing it can run complex, capital intensive trials in heavily pretreated solid tumor settings while keeping safety broadly manageable. That matters for near term catalysts, because the story hinges on clean progression of these studies into later stage development and on keeping large partners engaged.
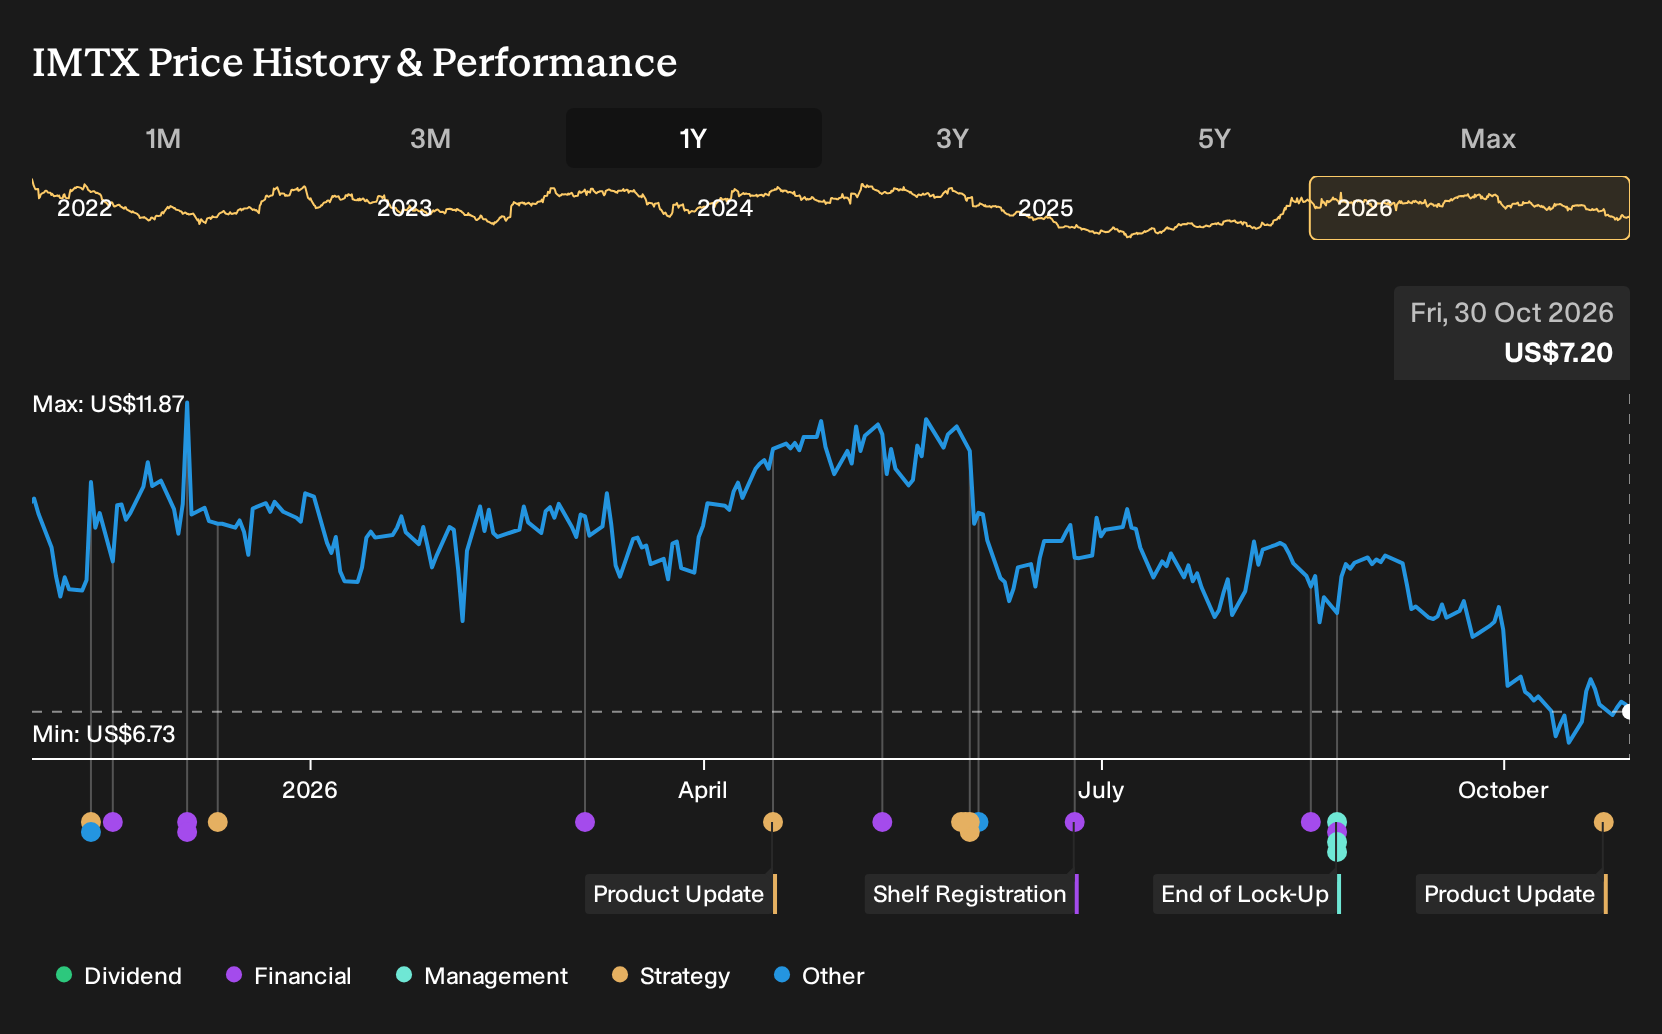
On the flip side, this is still a roughly US$1.0b clinical stage biotech with €41.7m of revenue and a net loss of €206.5m. The stock is down 31% year to date and has lagged both the US market and US biotech peers, even with analyst targets sitting well above the current US$7.20 share price. The new data may help sentiment, but it does not remove the core risk that Immatics is forecast to remain unprofitable for at least the next three years while it funds pricey trials and depends on higher risk external financing.
That said, there is a less obvious pressure point in the story once you factor in how those PRAME programs rely on ...
There's only one way to know the right time to buy, sell or hold Immatics. Head to Simply Wall St's company report for the latest analysis of Immatics's Fair Value.
Exploring Other Perspectives
Across just 2 fair value submissions from the Simply Wall St Community, estimates span from 0.06 to 16.40, so retail views on Immatics are anything but aligned. Those opinions were formed before the latest PRAME data at ESMO 2026, meaning you are weighing fresh clinical signals against community models that do not yet reflect them.
Explore another Immatics fair value estimate, including one that suggests as much as 99% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Immatics research is our analysis highlighting 1 key reward and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Immatics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Immatics' overall financial health at a glance.
Looking For More Investment Ideas Beyond Immatics?
Once you have a view on Immatics, it often helps to set it against a few very different opportunities. That way you are comparing it with other businesses on income potential, balance sheet strength, and upside, not just on headlines.
- If you want income to do more of the work for you, scan for resilient payers through 5 dividend fortresses.
- If capital preservation ranks higher on your list than chasing the next big biotech swing, check out a curated 30 resilient stocks with low risk scores.
- If you are hunting for quality that has not yet attracted broad attention, widen your net with a 18 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com