


EN
Raised Guidance Could Be A Big Moment For Shionogi Stock (TSE:4507)
- Shionogi raised full year revenue, profit and EPS guidance for the year ending March 31, 2027, and increased interim and annual dividend forecasts after reporting stronger than expected interim performance across rare disease, infectious disease and HIV products.
- The company links its higher earnings and dividend outlook directly to prior growth investments, including the RADICAVA rare disease platform and the planned IntraBio acquisition. Together, these are intended to deepen overseas cash generation while keeping domestic earnings less exposed to swings in infectious disease trends.
- This article examines how Shionogi's investment narrative is being reshaped by the upgraded earnings guidance and the shift in dividend policy.
What Is Shionogi's Investment Narrative?
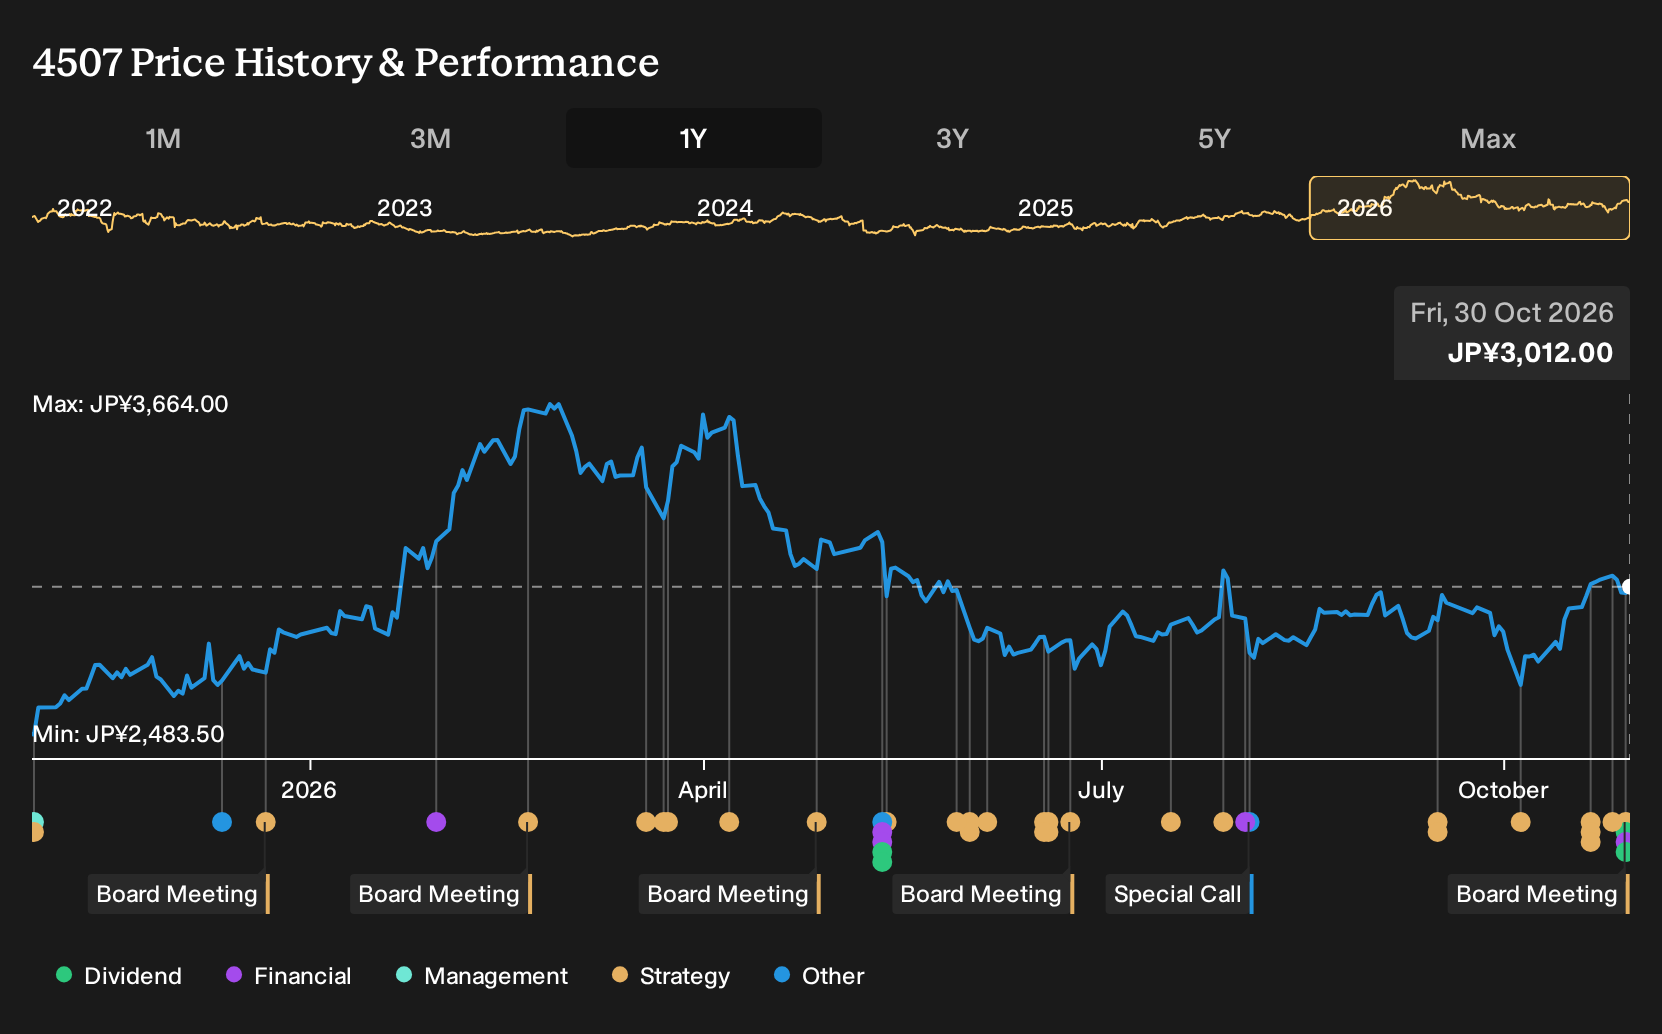
To own Shionogi, you need to believe the drug portfolio can keep throwing off solid cash while management recycles that into targeted growth areas like rare diseases, HIV and complex infections. The raised guidance for revenue of ¥720,000m and profit attributable to owners of parent of ¥212,500m, alongside higher EPS guidance, points to that story leaning on execution rather than broad market luck. The richer dividend outlook, with an annual forecast of ¥86 per share, signals confidence in cash generation even as the firm absorbs IntraBio and continues to invest in the U.S. platform.
In the short term, the key swing factors are very operational. RADICAVA, cefiderocol, XOCOVA and HIV royalties need sustained demand and pricing discipline, while SG&A and R&D stay under control despite heavier spending. The upgraded dividend plan, discussed at the October 29 board meeting, tightens the link between that operating performance and shareholder cash returns. The biggest risk highlighted by prior analysis, that earnings are forecast to decline on average over the next three years, now has to be weighed against this firmer guidance and a track record of earnings growth over the past five years.
That said, the story gets more complicated once you look closely at how much of recent strength is tied to ...
There's only one way to know the right time to buy, sell or hold Shionogi. Head to Simply Wall St's company report for the latest analysis of Shionogi's Fair Value.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly ¥3,354 to ¥7,203 per share, so private investors looking at Shionogi clearly do not agree on where the stock belongs. Those opinions were set before the October guidance and dividend updates. Treat them as a pre-upgrade snapshot and explore several alternative viewpoints.
Explore another Shionogi fair value estimate, including one that suggests as much as 139% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that is truly your own.
- A great starting point for your Shionogi research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Shionogi. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Shionogi's overall financial health at a glance.
Looking For More Investment Ideas Beyond Shionogi?
Once you have a view on Shionogi, it helps to widen the lens and compare it with other companies that match your preferred mix of quality, resilience and income. The Simply Wall St Screener can surface a focused shortlist so you spend time researching candidates that already fit your rough criteria rather than starting from scratch with a universe of thousands.
- If resilience and capital preservation sit at the top of your checklist, start by scanning a group of companies that our models flag as having relatively lower risk profiles through the 24 resilient stocks with low risk scores.
- For investors who care most about robust finances and clean balance sheets, look across a list of solid balance sheet and fundamentals (22 results) that can help you focus on businesses with stronger financial footing.
- If you want to get ahead of the crowd and spend time on underfollowed opportunities, sort through a curated pool of 71 high quality undiscovered gems that already score well on fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com