


EN
Fleetwood Shares Slid Even Though Sales Rose
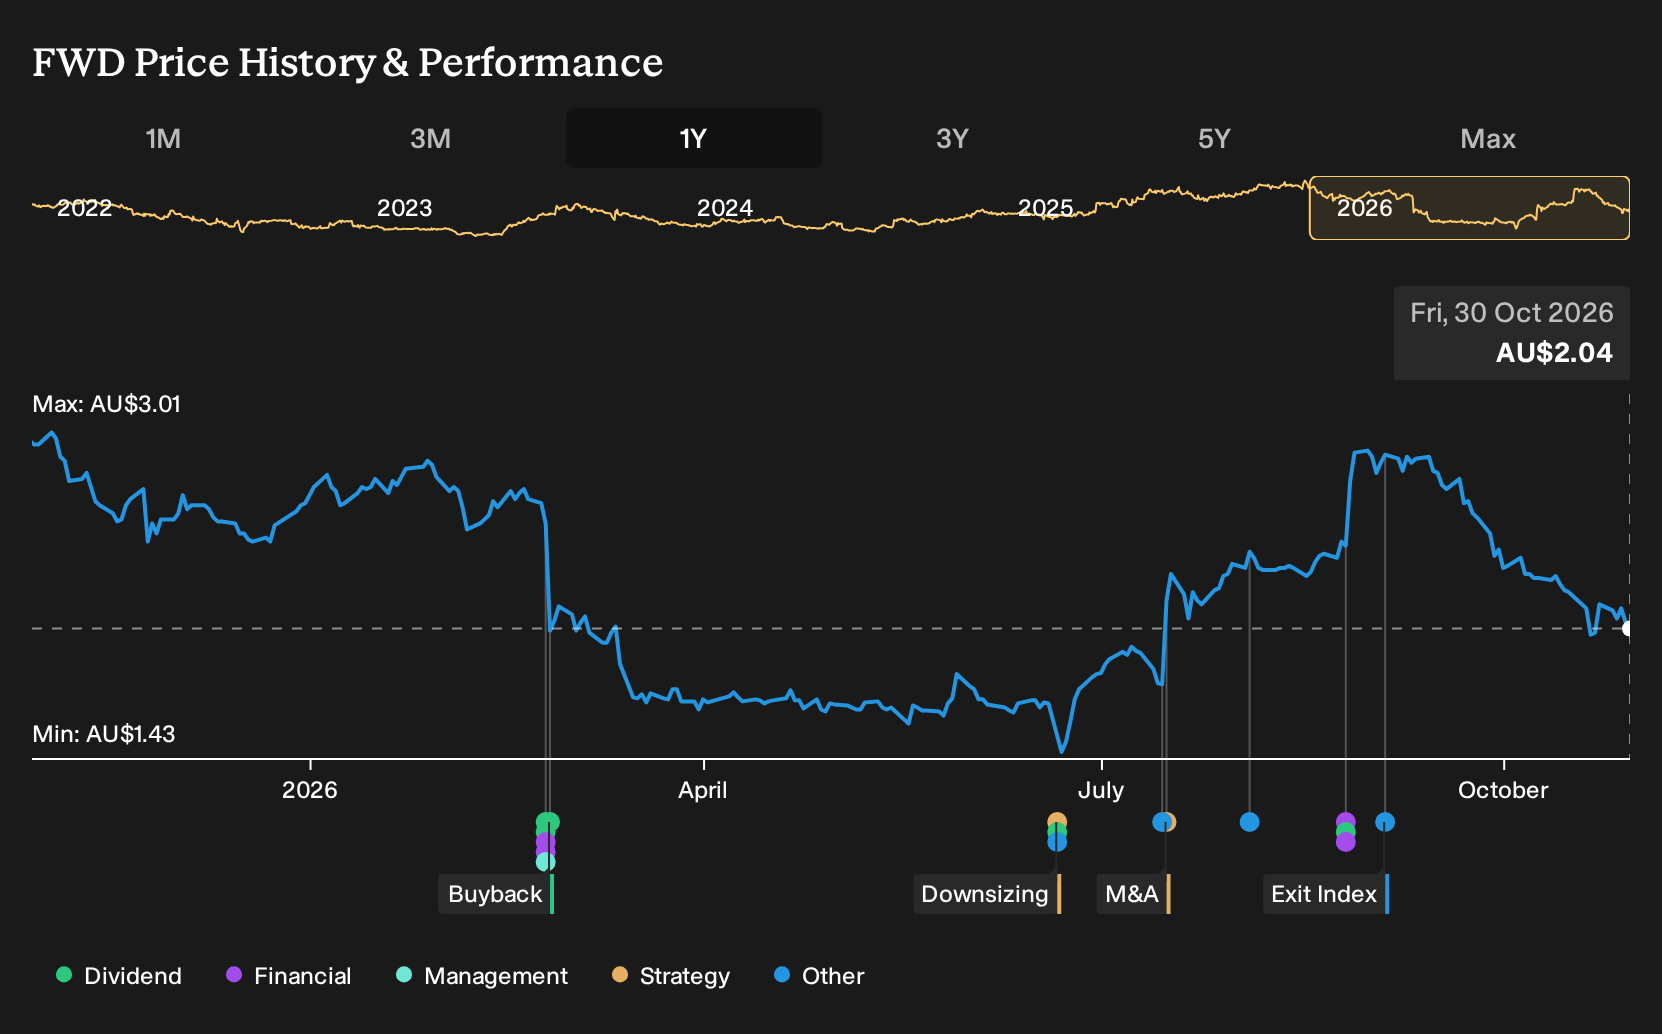
Fleetwood just reported rising revenue but a swing from profit to loss as net margin moved from positive to negative over the latest half year. For Fleetwood shareholders, the loss over the past year was 24.9%, including dividends. If you had been weighing an investment decision back in October 2025, with bullish and bearish analysts mostly debating upside, what clues were already on the table that this kind of setback was a real possibility?
Fleetwood has already moved. See which of 1 high quality undervalued stocks still trade below our estimates.
The Argument You Would Have Been Weighing Up On Fleetwood
The shares cost A$2.95 at the start of the period, and Fleetwood sat between two very different but credible stories about what might come next.
The bullish view saw a Fair Value of A$3.46, a price implied by expectations of about 3.4% annual revenue growth and profit margins lifting to 5.9% over three years. That camp leaned on modular construction demand and deeper government relationships.
The cautious camp anchored to a Fair Value of A$2.79, based on more restrained assumptions and concern that RV Solutions headwinds could keep dragging on group profitability.
What The Results Changed For Fleetwood
The clearest new fact was the H2 2026 result. Fleetwood reported revenue of A$245.5m and an underlying net loss of A$6.1m, which directly challenged the bullish profit-margin uplift story. Net margin moved from 4.3% in H2 2025 to a loss-making 2.5%, so the profitability leg of the optimistic case was still unproven.
The lesson is simple. When a thesis leans heavily on margin expansion, you check net margin first and then absolute earnings, before focusing on revenue or any headline about contract wins.
What You Are Being Asked To Believe About Fleetwood Now
Fleetwood trades at A$2.04 today, after the share price fell 24.9% over the past year. This Narrative’s Fair Value sits above the current price, based on the view that cash, free cash flow and the balance sheet together point to stronger earning power than the market implies.
The distinctive argument turns on Pilbara accommodation utilisation and cleaner execution in Building Solutions, rather than top line growth alone. For that higher figure to make sense, a buyer today would have to assume Red Dog Village and Searipple stay well occupied while cost savings in Building Solutions flow through without fresh contract missteps.
"The current numbers, including A$35.6 million of underlying EBIT, A$35.9 million of free cash flow, A$61.5 million of cash with no debt, ongoing dividends and buybacks, and guidance for Building Solutions to move to at least breakeven EBIT in 1H FY27, imply the share price treats Fleetwood as a business with weaker long-term earnings power than these metrics suggest."
Not everyone reads the same price the same way. → See the higher figure this Narrative lands on, and how it gets there
Looking One Step Beyond Fleetwood
Fleetwood gets you thinking about accommodation and physical assets. AI data centres raise a different challenge altogether.
They must stay powered and cool every hour, under relentless computing loads. As equipment packs tighter, traditional air systems struggle to remove heat quickly enough.
That strain is steering operators toward liquid cooling that moves heat more efficiently. One specialist manufacturer designs the power gear and thermal hardware behind these setups.
Its engineers even sit alongside chip teams on fresh cooling concepts. If AI infrastructure keeps intensifying, this kind of quiet hardware supplier could become far more central.
One Narrative has already put a figure on it. → Uncover the company trading 43% below one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com