


EN
Coloplast (CPSE:COLO B) Opens Portugal Plant As Fair Value Debate Stays In Focus
Why Coloplast’s Portugal expansion matters for shareholders
Coloplast (CPSE:COLO B) has switched on its largest factory yet: a 50,000 m2 continence care site in Felgueiras, Portugal, after investing about €100 million to support its 2030 growth plan.
Coloplast’s Portugal move comes after a mixed run in the market, with a 1-month share price return of 15.41% and a 90-day gain of 12.32%, but a year-to-date share price decline of 10.09% and a 5-year total shareholder return that has fallen 47.50%.
Scan beyond Coloplast and explore other healthcare manufacturers that are expanding capacity with our curated list of solid balance sheet and fundamentals (203 results) for potential ideas that combine operational scale and financial resilience.
The Portugal buildout reflects Coloplast’s push to expand its real world capacity even as long term shareholders have seen weaker returns. Does the current valuation lean more on sentiment swings or on the underlying business at work?
Most Popular Narrative: 35% Undervalued
Coloplast’s most followed narrative pegs fair value at DKK737 per share, compared with the last close of DKK482.3, framing the stock as materially undervalued even after its recent rebound.
Coloplast is a rare thing, a genuinely high quality, non cyclical compounder available at a genuinely cheap price. It is considered cheap for reasons that, on inspection, do not touch the part of the business that matters. The market is reacting to a Kerecis acquisition that disappointed and has been partly written down, a run of guidance cuts, regulatory upheaval in the United States, weakness in China, and a currency drag. These factors have compressed the multiple from close to 40 times earnings to about 17, halving the valuation while the underlying earnings stayed flat.
See why 8 investors see Coloplast as 35% undervalued.
Result: Fair Value of DKK737 (UNDERVALUED)
Still, if Coloplast’s Medicare exposed Kerecis unit stalls again, or if management pursues another large debt funded deal, this 35% undervalued pitch can unravel fast.
Find out about the key risks to this Coloplast narrative.
Another view on Coloplast’s valuation
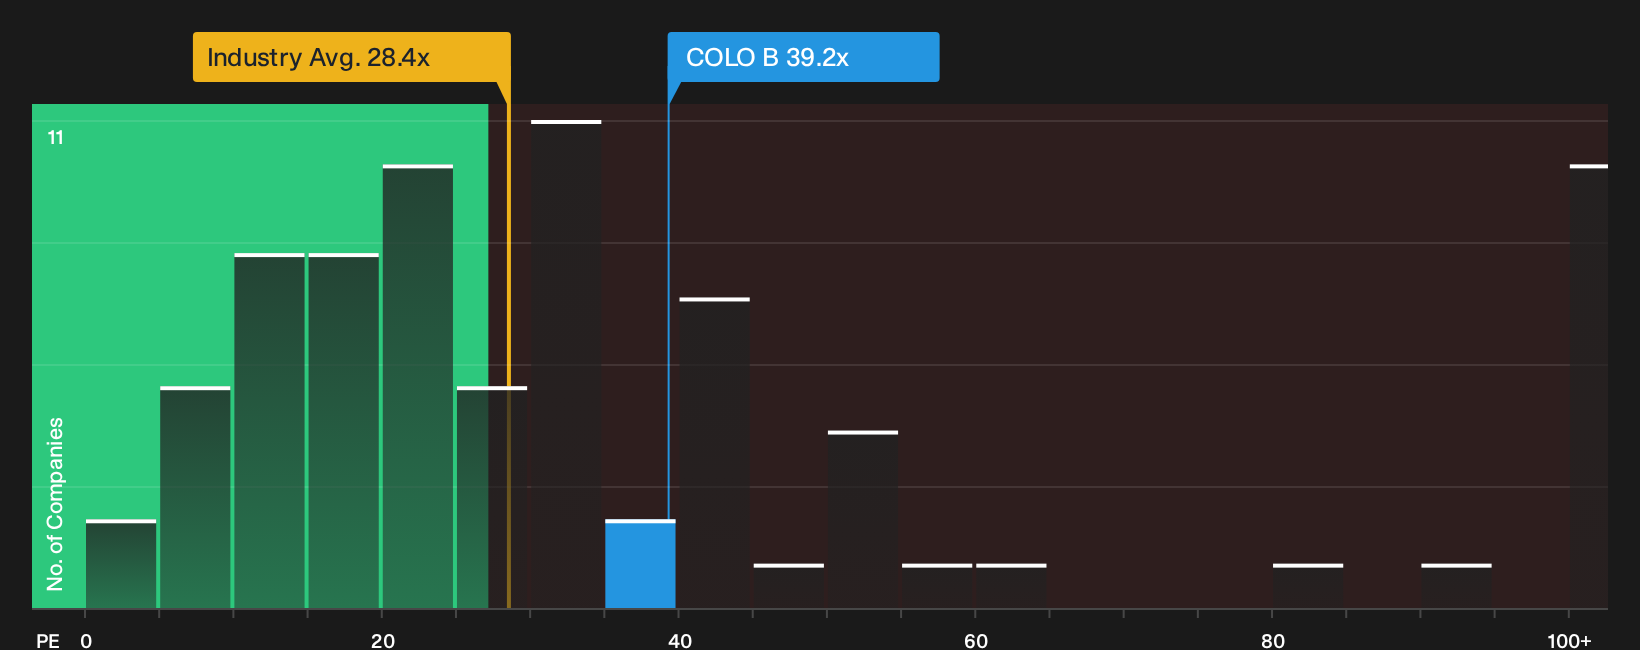
On simple multiples, Coloplast screens as expensive. Its P/E of 39.3x sits well above both the European medical equipment group on 28.4x and its peer set on 25.3x, and even above a fair ratio of 32.7x that our regression work suggests the market could drift toward, which means a real risk of de-rating if sentiment cools.
That leaves investors with a genuine puzzle, because the stock screens cheap on fair value models yet rich on earnings multiples, so which crowd is misreading Coloplast?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this split verdict on Coloplast leaves you unsure, act while the facts are fresh and compare the data yourself with 2 key rewards and 4 important warning signs
Looking for more investment ideas beyond Coloplast?
Do not stop with a single stock view. Broaden your watchlist using targeted screeners that surface different types of opportunities other investors might be ignoring.
- Target resilient balance sheets and steady fundamentals by reviewing the list of solid balance sheet and fundamentals (203 results) that filters for financially robust businesses built to handle shocks.
- Hunt for pricing gaps by scanning the 199 high quality undervalued stocks that highlights companies where market expectations and business quality may be out of sync.
- Prioritise income and staying power through the 221 dividend fortresses that focuses on higher yielding payers aiming to combine cash returns with durability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com